Legal & Finance
Copropiedad y patrimonio: impuestos y herencia
Descubra cómo ser propietario de una parte real de una vivienda en copropiedad facilita la planificación sucesoria, la diversificación de su cartera y el ahorro de costes, y qué comprobar en materia fiscal antes de comprar.
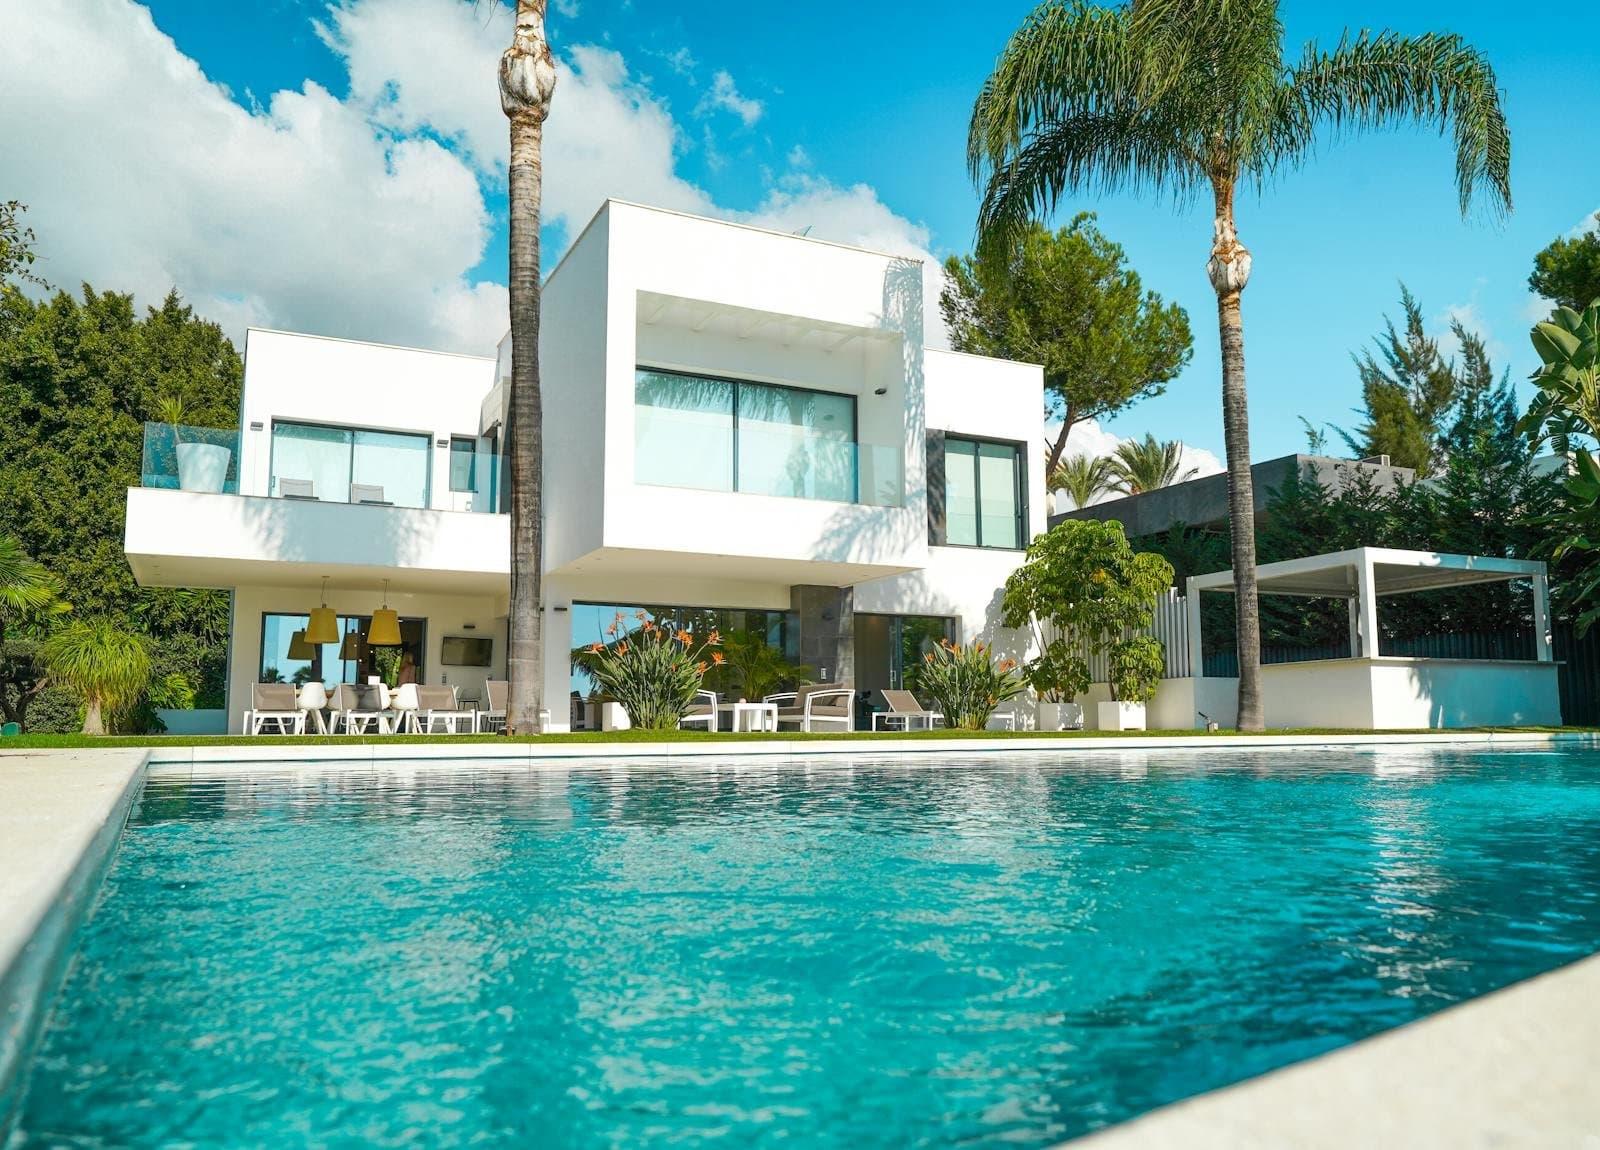
When most people think about the appeal of co-ownership property, they focus on the lifestyle benefits — 45 days a year in a stunning villa in Mallorca, a ski chalet in the French Alps, or a beach house in Florida, without the burden of full ownership costs. What gets far less attention is what you actually own: a real share of the home, not a right to use it. And for high-net-worth buyers thinking carefully about tax and wealth planning, that may be the most compelling advantage of all.
In 2026, with property taxes rising across Europe, inheritance rules shifting, and international buyers navigating increasingly complex cross-border regulations, the question of how you own property matters as much as what you own. Our guide to fractional ownership explained sets out the basics; this article looks at what owning a share means for your finances and your long-term planning.
This guide explains what owning a share actually means for your finances, where it delivers advantages that outright property ownership simply cannot, and how buyers across the US, UK, and Europe are using co-ownership properties to build diversified portfolios of luxury real estate without the traditional headaches.
The Foundation
What You Actually Own as a Co-Owner
You own a real share of the home — an eighth, a quarter — not a right to use it. You can sell it, pass it on to your heirs, and it rises and falls in value with the house. The legal set-up is arranged by our partner for each home and walked through with you before you buy. This distinction matters enormously. You are not buying a right to use a property for a certain number of weeks, as you would with a timeshare.
What co-ownership has done is make prime holiday property available to individual buyers at a fraction of the price, professionally managed — something that was previously only practical for those who could afford to buy the whole property themselves.
According to research from Knight Frank’s Wealth Report 2026, real estate accounts for an average of 27% of ultra-high-net-worth individual portfolios globally. Co-ownership — see fractional ownership explained — allows buyers to access this asset class with dramatically lower capital outlay while still owning real property.
27%
Average share of real estate in UHNW individual portfolios globally (Knight Frank Wealth Report 2026)
1/8th
Each co-owner’s share of running costs, taxes, and management fees — dramatically reducing total outlay
~45 days
Annual usage entitlement per 1/8th co-ownership share, managed flexibly via the booking app
Resale
Handled through our partner’s resale process — no need to sell the whole house
Tax
Tax: What Changes When You Own a Share
How tax works depends on the country and the home’s legal set-up, which our partner explains before you buy; we recommend independent advice. What does not change from one home to the next is the arithmetic of sharing: every cost of the home is divided between its owners.
The running costs of a co-ownership property are shared in direct proportion to ownership. A 1/8th owner pays 1/8th of all costs. Where a home generates rental income, whether and how those costs can be offset depends on the country and the home’s legal set-up. You can explore the full picture of the running costs of a fractional ownership property to understand exactly what is covered.
Annual Running Cost Comparison: Full Ownership vs. 1/8 Co-Ownership Share
Property Management — Full Ownership
Property Management — 1/8 Share
Maintenance & Repairs — Full Ownership
Maintenance & Repairs — 1/8 Share
Insurance — Full Ownership
Insurance — 1/8 Share
“Owning a real share of the home is not a technicality. It is the reason co-ownership works so well for estate planning and portfolio management — real property you can sell, pass on, and spread across markets.”
Wealth Planning
Estate Planning and Intergenerational Wealth Transfer
One of the most underappreciated aspects of co-ownership is how it fits into estate planning and intergenerational wealth transfer. Passing property directly to heirs typically involves probate processes, inheritance tax assessments on the full property value, and in many jurisdictions, complex procedures for transferring real estate title across borders — a particular challenge for international buyers.
Because you own a real share of the home, you can pass it on to your heirs — and because that share is a fraction of the property, it is a smaller asset to plan around than a whole house. How inheritance, gifts or trusts work in practice depends on the country and the home’s legal set-up, which our partner explains before you buy; we recommend independent advice.
For international buyers — Americans owning in Europe, British buyers in Spain or France, or European buyers with US properties — cross-border inheritance rules make independent tax advice especially important. As part of the co-ownership buying process, our partner walks you through the legal set-up of the home before you buy, so you and your own advisers can plan around your specific nationality, residency, and estate planning goals.
| Ownership Structure | Tax Treatment | Asset Protection | Estate Planning | Exit Liquidity |
|---|---|---|---|---|
| Direct personal ownership | Personal income tax on all rental income | None — personal assets fully at risk | Complex probate; real estate title transfer required | 6–12 months to sell |
| Co-ownership (1/8th share) | Depends on the country and the home’s legal set-up | Depends on the home’s legal set-up — explained before you buy | A real share you can pass on to your heirs | Through our partner’s resale process |
| Corporate property ownership | Corporation tax + dividend tax on distributions | Good protection, but complex administration | Company shares transfer; moderate complexity | Moderate — depends on share structure |
| Holiday fund / property REIT | Dividend income and capital gains treatment | Strong — no direct property liability | Simple share transfer mechanism | High (listed) or moderate (unlisted fund) |
| Timeshare | No ownership — zero tax deductions | None — no asset to protect | Cannot be inherited or transferred in most cases | Very low — often impossible to resell |
Portfolio Strategy
Fractional Property as an Alternative Asset Class
For high-net-worth individuals thinking about portfolio construction, fractional ownership explained offers something genuinely unusual: direct real estate exposure with a fraction of the capital commitment. According to Savills’ Prime Residential Index 2026, prime holiday property values across key European and US markets have continued to outperform broader real estate indices, with ski and coastal markets showing particularly strong appreciation.
Traditionally, accessing this asset class required committing €500,000 to €2 million or more to a single property — one location, one market, one currency. That level of concentration runs counter to every principle of sound portfolio management. The co-ownership model changes this entirely. For the same total capital outlay, a buyer can diversify across multiple properties in multiple locations, spreading both market risk and currency risk while owning a real share of each home.
A buyer might allocate capital across a ski property in the French Alps, a coastal villa in Spain, and an apartment in Italy — each providing exposure to different market cycles and different rental income streams. This is the co-ownership vs full ownership proposition at its most compelling: fractional ownership enables the portfolio diversification that institutional investors take for granted, available to individual buyers for the first time. You can browse co-ownership destinations to see the breadth of markets available.
Step 1
Select Your Property
Browse available co-ownership properties across Europe and the USA. Each is professionally managed and ready for new co-owners.
Step 2
Legal & Tax Review
Our partner walks you through the home’s legal set-up before you buy; we recommend independent advice on your tax situation, residency status, and estate planning goals.
Step 3
Acquire Your Share
You become a co-owner of the home — a real share, an eighth or a quarter, not a right to use it.
Step 4
Proportionate Cost & Income Flow
Running costs, management fees, local taxes, and any rental income all flow proportionately to your ownership stake — fully transparent and professionally managed.
Step 5
Use, Enjoy, and Appreciate
Enjoy approximately 45 days per year in your luxury property, book via the app, arrive to find everything prepared — while your real estate investment appreciates in the background.
Step 6
Flexible Exit When Ready
When you wish to exit, your share is offered first to existing co-owners, then to market, through our partner’s resale process — without you having to sell the whole house.
Running Costs
The True Financial Efficiency of Proportionate Cost Sharing
One of the most compelling financial arguments for co-ownership is the dramatic reduction in running costs. According to analysis by JLL’s Residential Research team, a full second-home owner using their property for an average of four to six weeks per year is effectively paying 100% of annual running costs for less than 12% utilisation. Every euro spent on maintenance, insurance, management fees, and local taxes applies to a property sitting empty for more than 300 days a year.
Under the co-ownership model, each 1/8 co-owner pays 1/8th of all running costs — maintenance, insurance, cleaning, professional property management, local taxes, community fees, everything. The result is that the effective cost per day of use is dramatically lower than full ownership, even comparing a co-owned property of equivalent quality. Unlike the financial shock of unexpected repair bills that catches many second-home owners off guard, the running costs of a fractional ownership property are transparent, predictable, and shared.
This cost efficiency has a direct impact on wealth planning. Capital that would previously have been locked in a high-maintenance second home — or lost to running costs that far exceeded the genuine utility derived from the property — can instead be deployed across a diversified portfolio of co-ownership properties, maintaining real estate exposure while dramatically improving overall capital efficiency. Viewed through the lens of cost-per-day-of-use, the maths is compelling.
Rental Income
Rental Income: How It Works for Co-Owners
Many co-ownership villas and chalets can generate rental income when not occupied by their owners. This rental income — fully managed by the platform, with owners never needing to handle bookings, guests, or logistics — is distributed to co-owners in proportion to their ownership stake. The tax treatment of this income depends on each owner’s individual circumstances and the specific country where the property is located, as well as on the home’s legal set-up, which our partner explains before you buy.
In many jurisdictions, rental income can be offset against relevant deductible expenses — management fees, maintenance costs, local taxes, and in some cases depreciation — though the rules depend on the country and the home’s legal set-up. The net taxable income is typically significantly lower than the gross rental receipts, making the effective yield on a co-ownership investment considerably more attractive than a simple headline rental figure might suggest.
For buyers who hold co-ownership interests in properties across different countries, specialist tax advisors can structure the holdings to take advantage of applicable tax treaties and minimise overall tax liability. It is worth noting that rental income availability depends on local regulations and the specific terms of each property — this should always be confirmed before purchase. Where rental income is available, it is distributed to co-owners in proportion to their share, in a transparent and professionally managed way.
Exit Strategy
Selling Your Share: Flexibility That Full Ownership Cannot Match
The exit flexibility of co-ownership is another major advantage for long-term wealth planning. When you want to exit a full property investment, you must sell the entire asset — a process that can take six months to a year in many prime markets, involves significant transaction costs, and requires all parties to complete simultaneously. The process is slow, expensive, and inflexible, tying up capital that could be redeployed elsewhere.
When you own a share of the home, selling is far simpler. Your share can be sold independently of the other owners and the property itself. Resale is handled through our partner’s resale process, without you having to sell the whole house: the share is first offered to existing co-owners, then listed on the open market. The sell fractional ownership share process is streamlined, professionally managed, and does not require the consent or coordination of co-owners.
From a wealth planning perspective, this flexibility is transformative. You are not locked into a rigid long-term commitment. You can reallocate capital as your lifestyle and financial circumstances change — exiting one market and entering another, reducing real estate exposure as you approach retirement, or realising appreciation that has accrued in a particular property. The best fractional ownership properties listings give a clear picture of the market, and many buyers return to acquire interests in additional properties as they become comfortable with the model. According to Savills Prime Property research, fractional ownership resale liquidity is among the most cited advantages by experienced buyers.
Common Questions
Frequently Asked Questions
Is a co-ownership share the same as a timeshare?
No — they are completely different. A timeshare gives you a contractual right to use a property for a set period; you own nothing and have no equity. With co-ownership you own a real share of the home — an eighth, a quarter — not a right to use it. Your share can appreciate in value and can be sold on the open market at market price. The legal set-up is arranged by our partner for each home and walked through with you before you buy.
How is my share taxed?
How tax works depends on the country and the home’s legal set-up, which our partner explains before you buy. Running costs, local property taxes and any rental income are shared in proportion to your stake; we recommend independent tax advice for your own situation.
Can I pass my co-ownership share to my children or heirs?
Yes. You own a real share of the home, so you can pass it on to your heirs, gift it, or include it in your wider estate planning. How inheritance works in practice depends on the country and the home’s legal set-up, which our partner explains before you buy; we recommend independent advice for your jurisdiction and circumstances.
What happens to my investment if property values increase?
Your share reflects the proportionate value of the underlying property. As the property appreciates, so does the value of your share. When you sell, the sale price reflects the current market value of the property at your proportionate share — exactly as it would for a full property owner, but at your ownership percentage. Rising prime property markets benefit co-owners directly and fully.
Can I own co-ownership shares in multiple properties across different countries?
Yes, and this is one of the most powerful portfolio strategies available. You can hold shares across multiple properties in multiple countries; the legal set-up of each home is arranged by our partner and explained before you buy. This provides geographic diversification, currency diversification, and exposure to different market cycles — a level of real estate portfolio sophistication previously only available to institutional investors.
How is rental income distributed and how is it taxed?
When a co-ownership property generates rental income, it is fully managed by the platform — owners never handle bookings, guests, or payments. Income is distributed to each co-owner in proportion to their ownership stake. The tax treatment varies by jurisdiction and your personal tax circumstances, but your share of net income (after management fees and allowable expenses) is professionally reported and transparent.
Do I need my own legal or tax advisor when purchasing through co-ownership?
We recommend it. Our partner walks you through the legal set-up of each home before you buy, and an independent legal or tax adviser can review your personal situation, nationality, and residency to make sure the purchase fits your circumstances.
Explore Co-Ownership Properties
Speak with our specialists about how owning a share of a home could fit your wealth planning goals — from estate planning to portfolio diversification.
Browse PropertiesMás de Co-Ownership Property
Contáctanos
Habla con un experto
Cuéntanos qué buscas y uno de nuestros especialistas en copropiedad se pondrá en contacto contigo en menos de 24 horas.