Florida · USA
Fractional Ownership & Co-Ownership in Florida
From a Rosemary Beach courtyard house on the white-sand 30A coast to a Brickell Miami penthouse looking out over Biscayne Bay and the downtown skyline — fractional ownership in Florida means a real share of the most established sun-belt second-home state in the United States, around six weeks of personal use a year, and a fully managed home waiting whenever you arrive. Whether you call it fractional ownership or co-ownership, you own a real share of the home.
21 properties · from $68,000
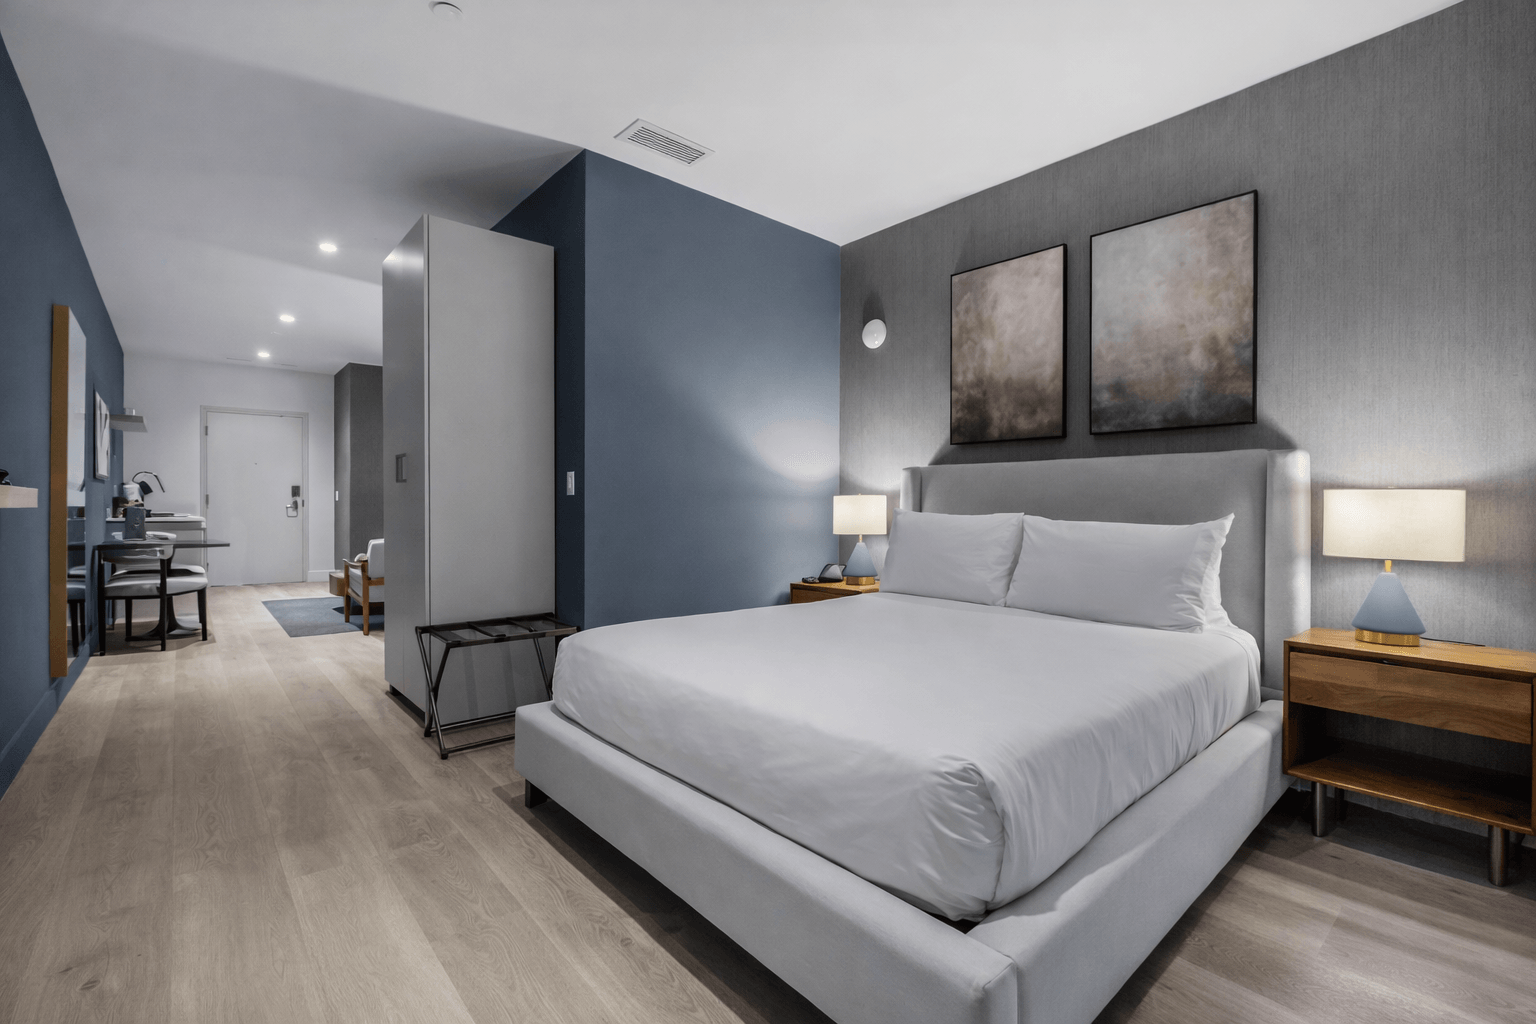
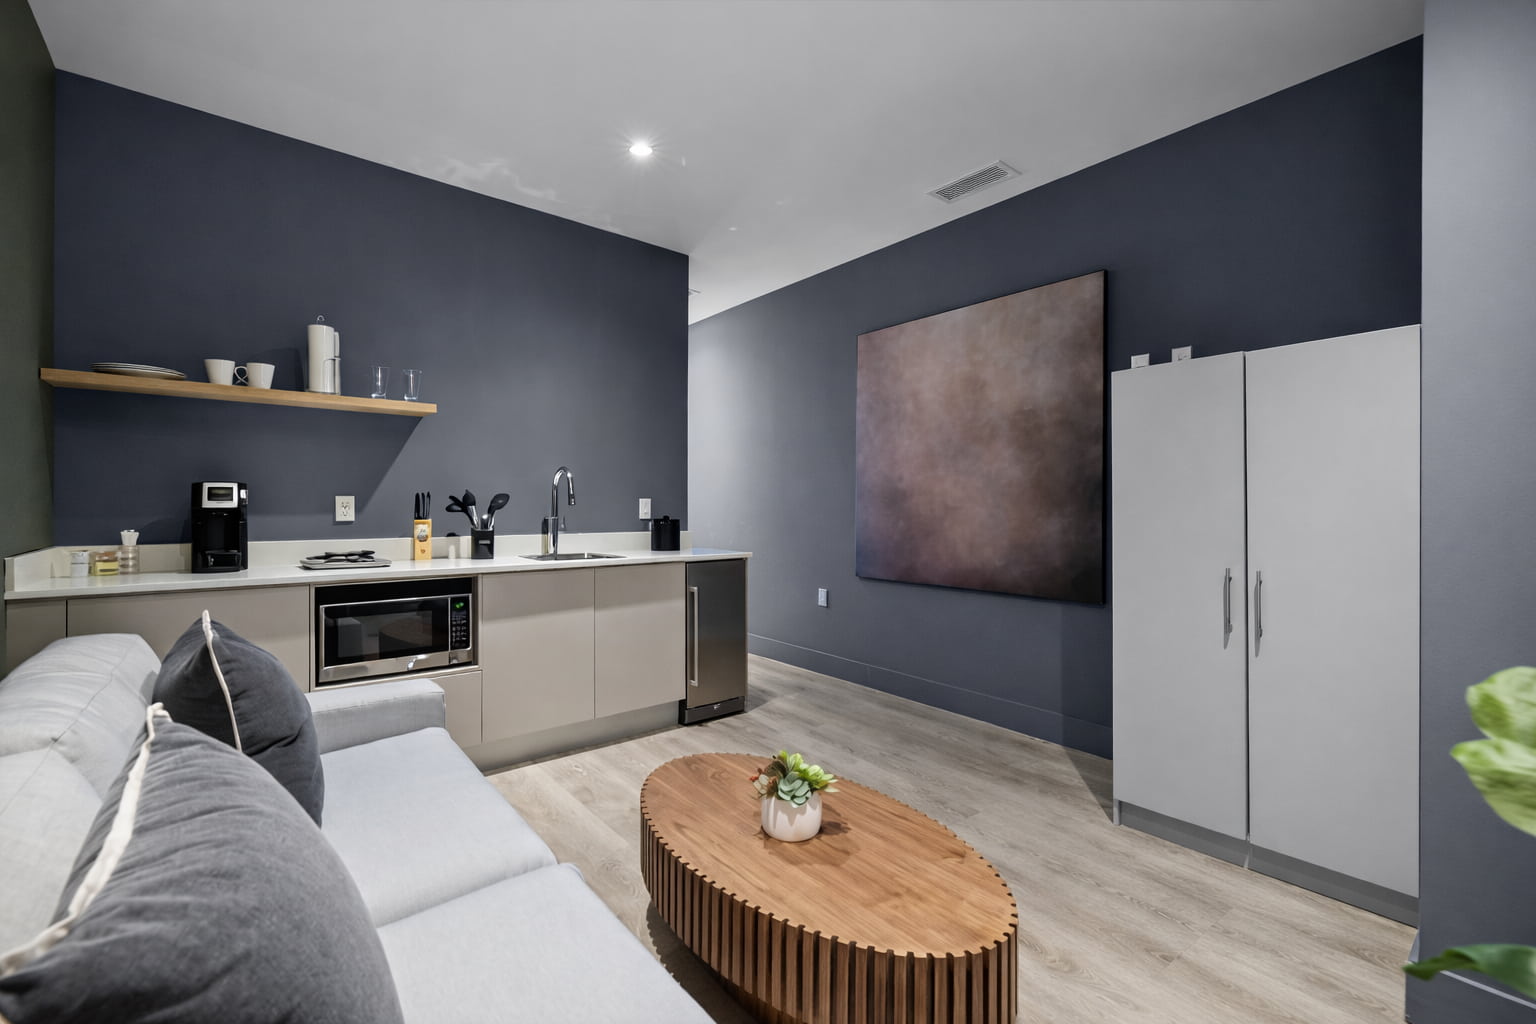
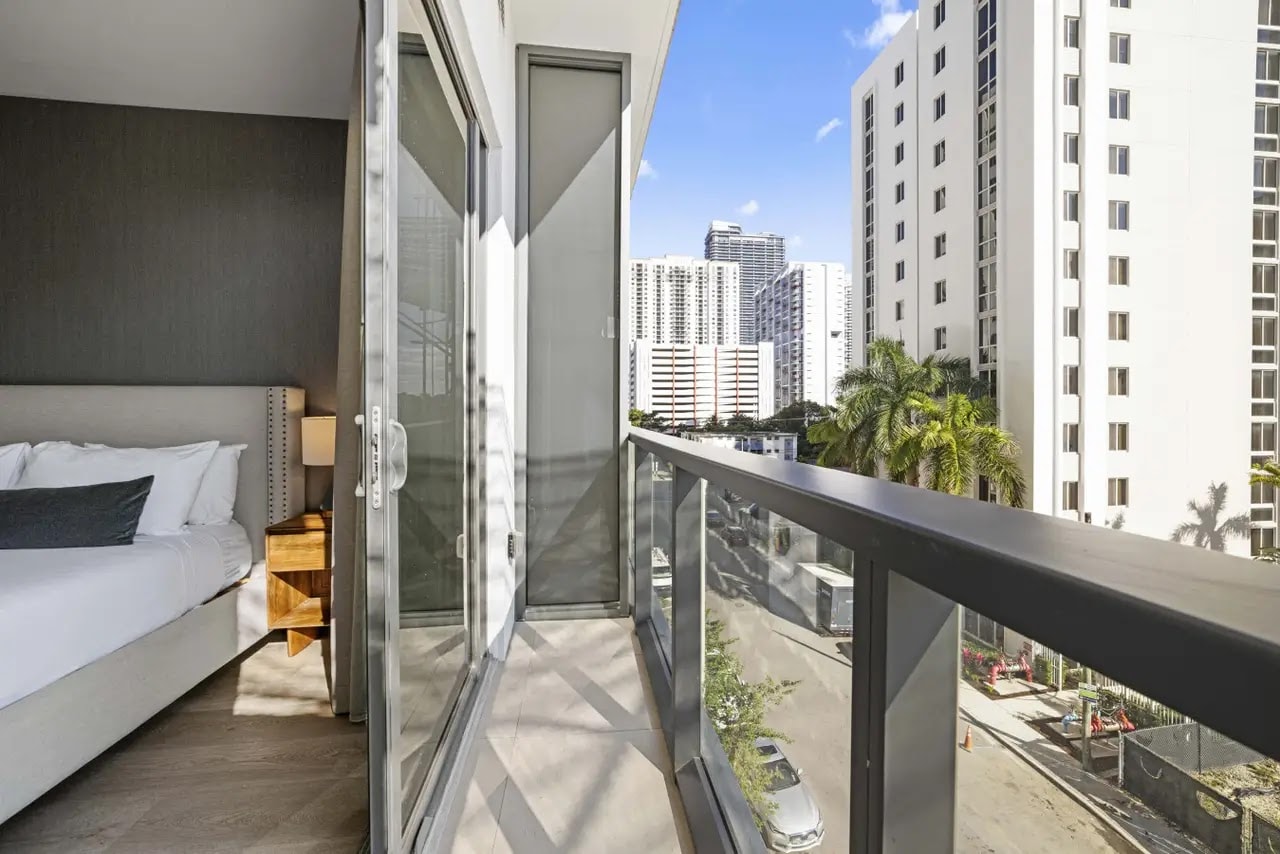
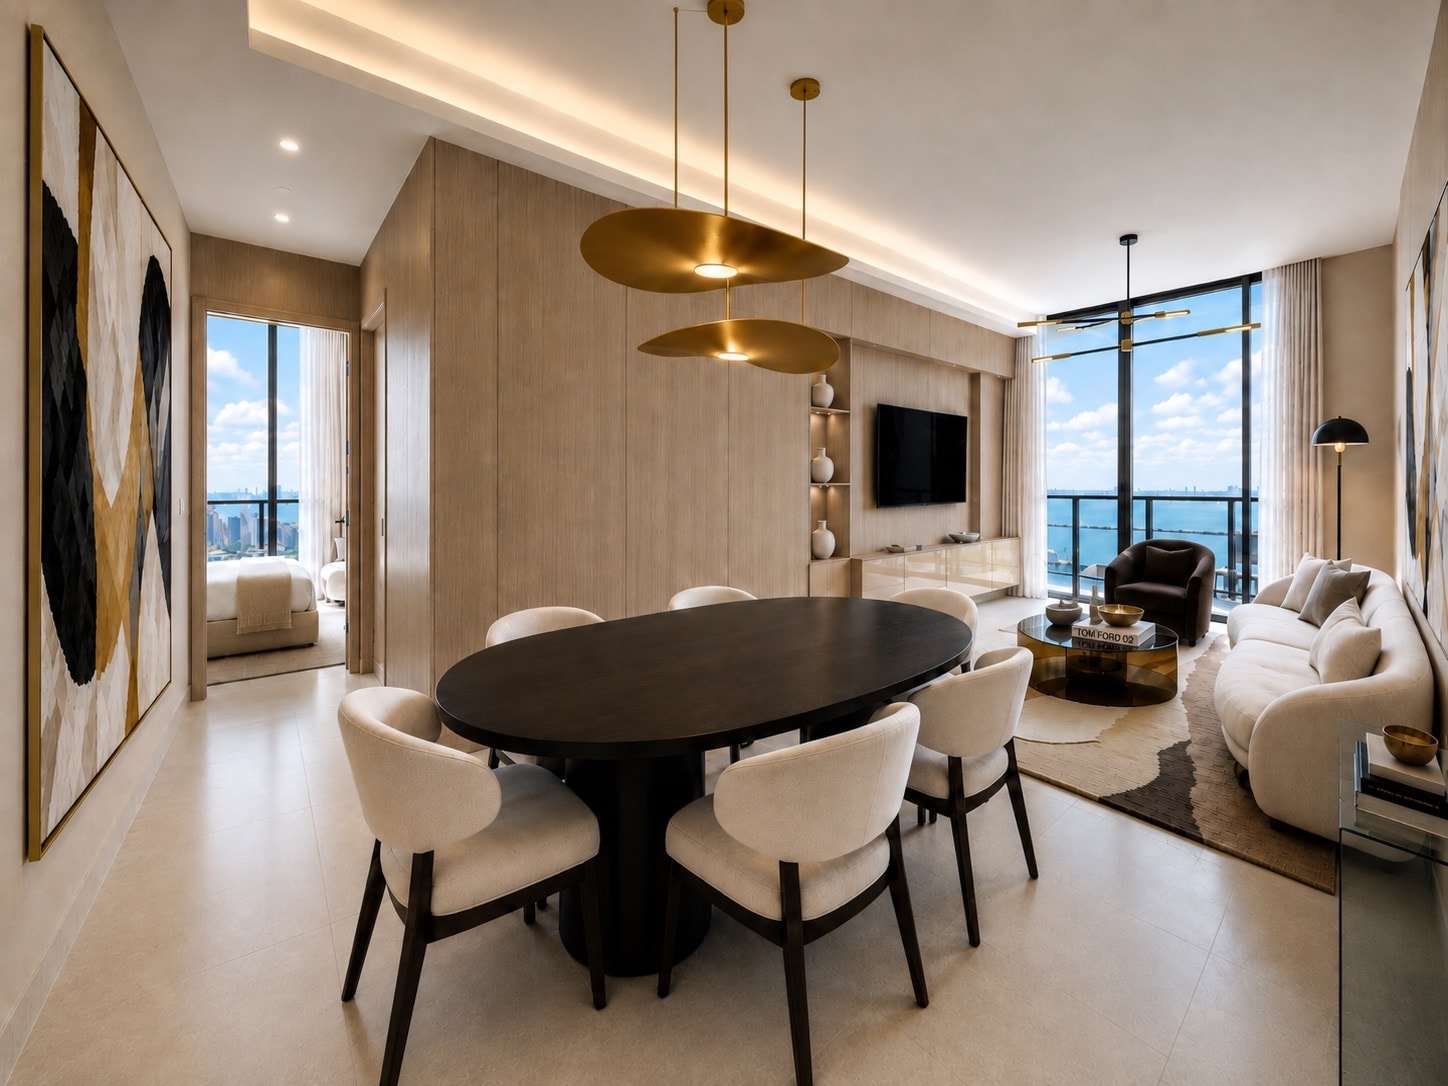
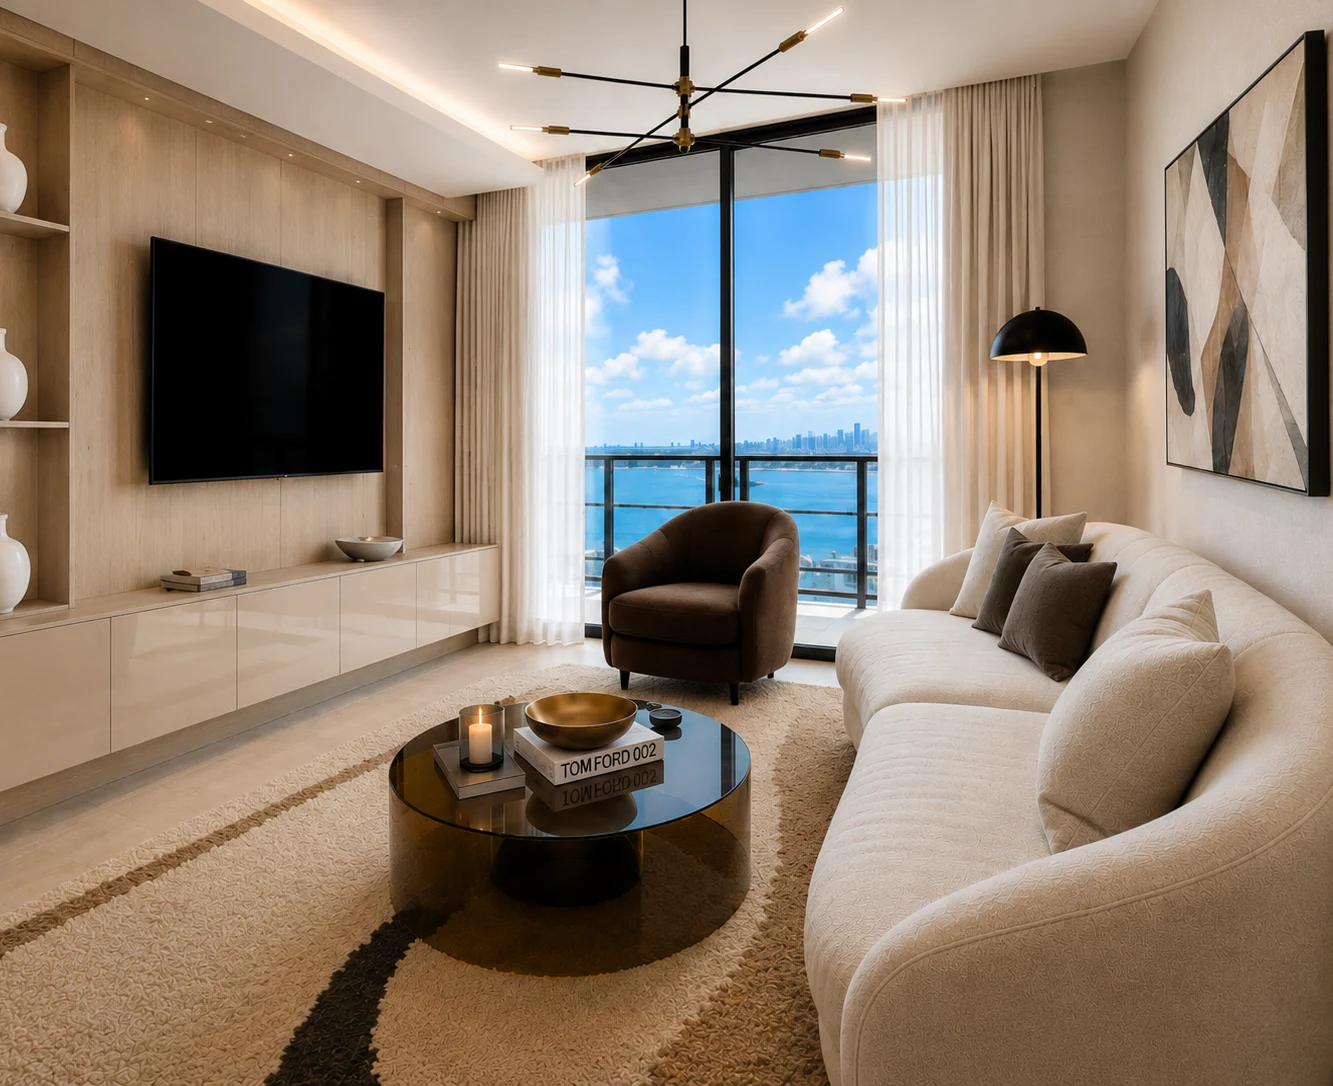
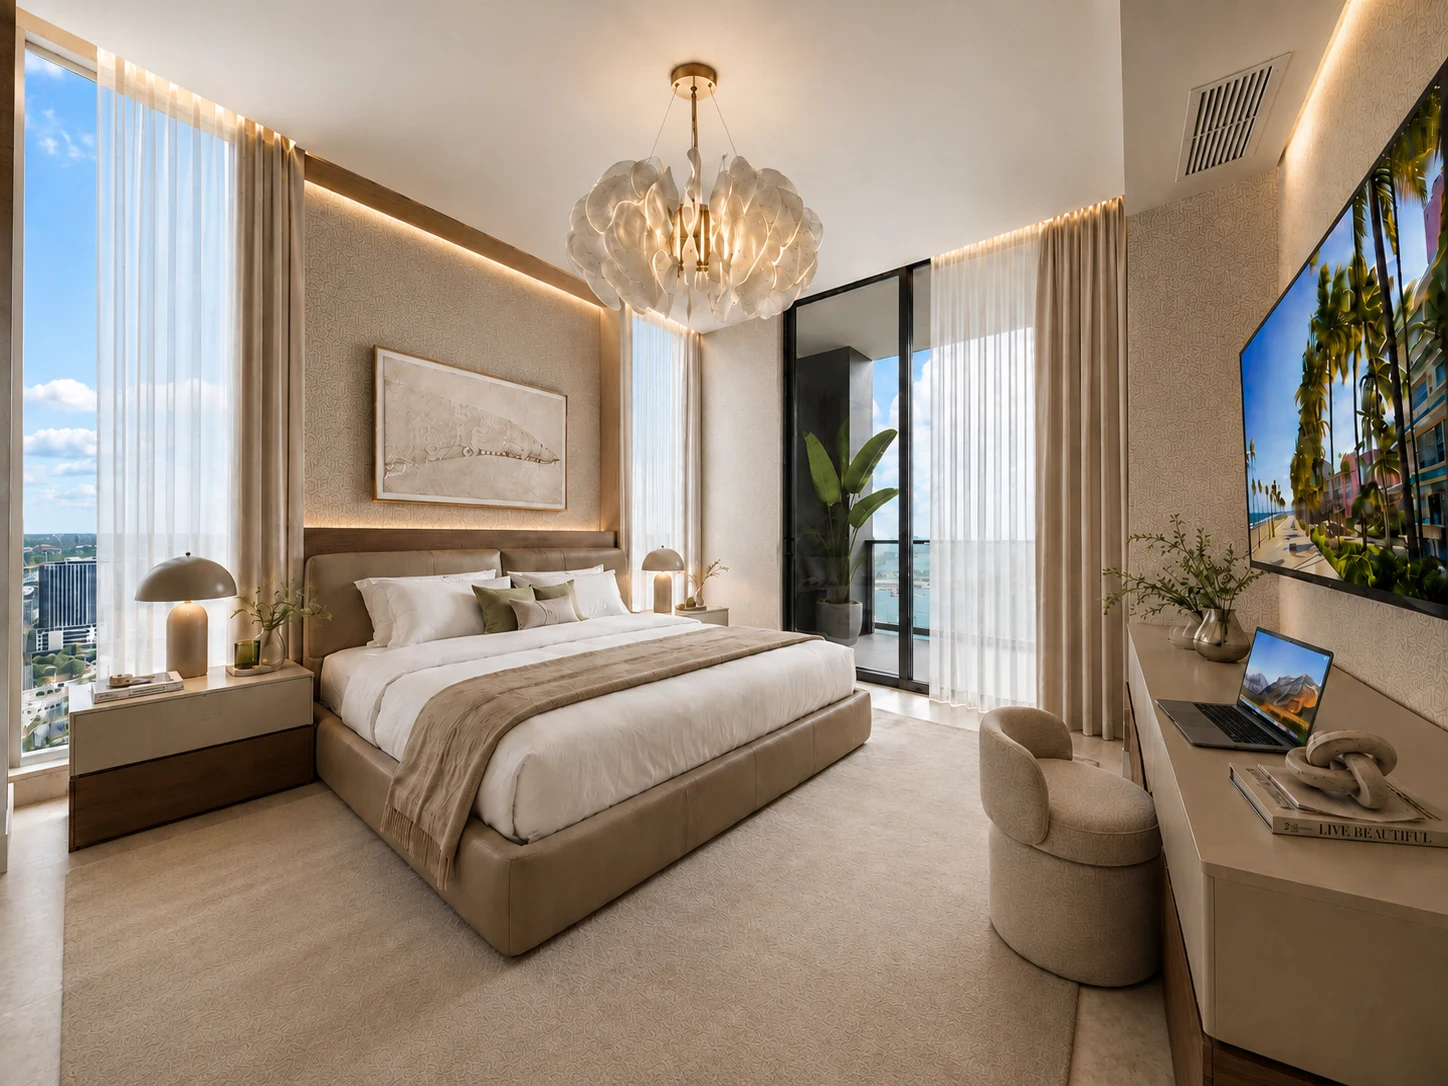
Miami, Florida, USA — 3-Bed Penthouse With Ocean Views
$230,000
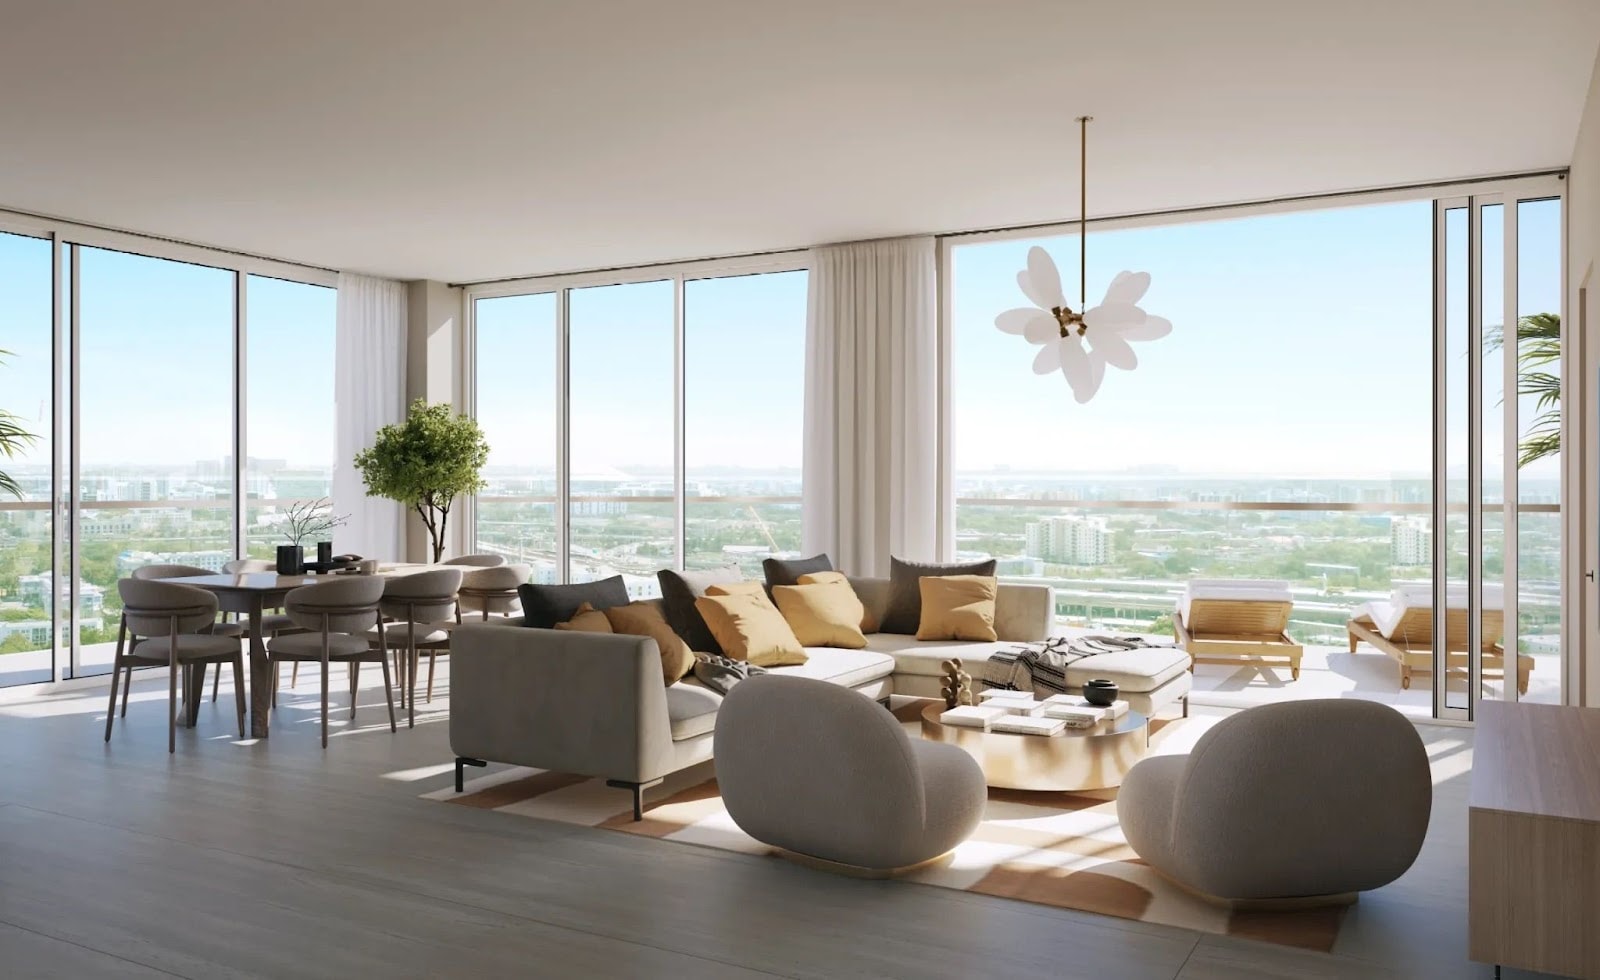
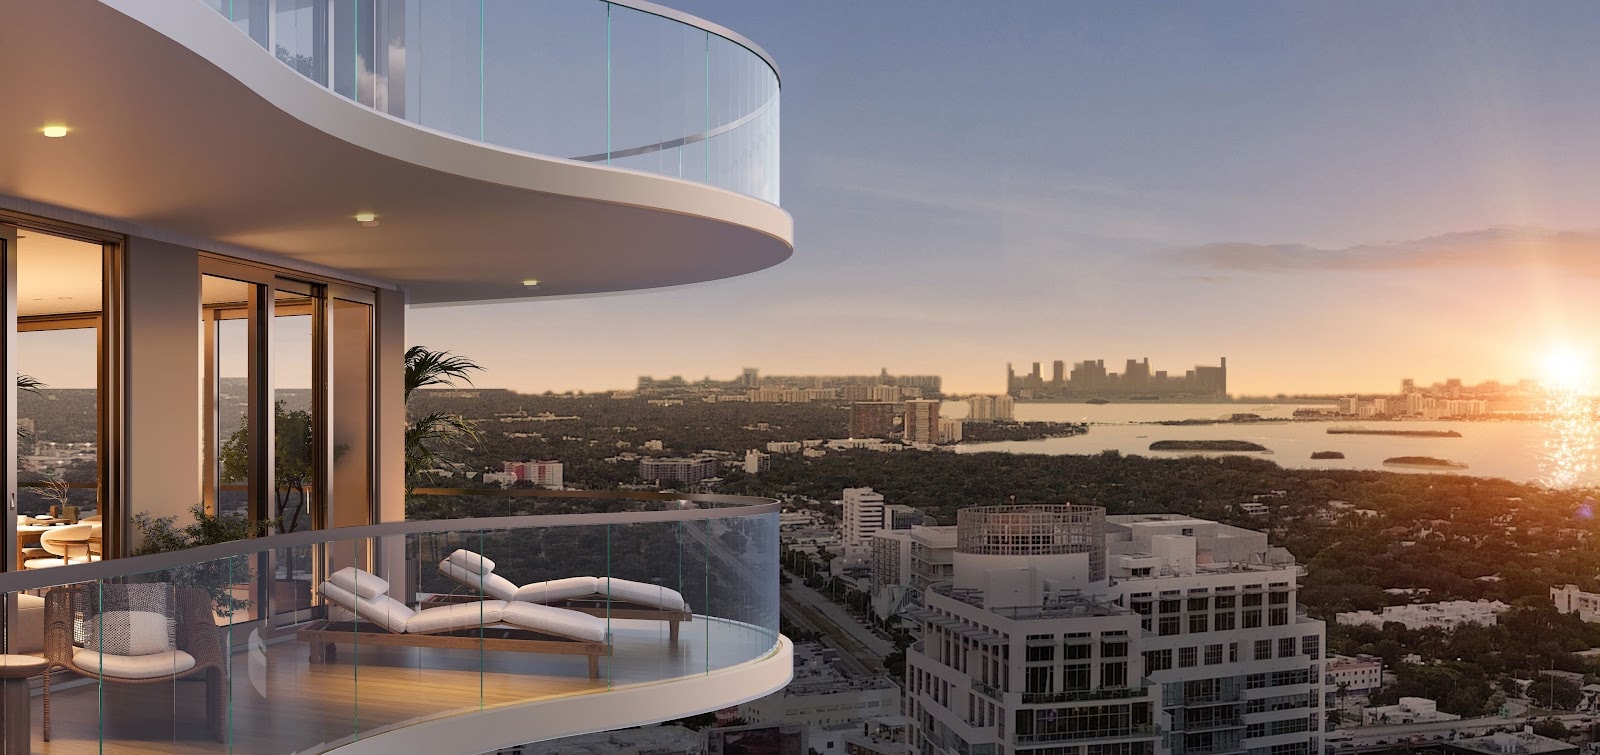
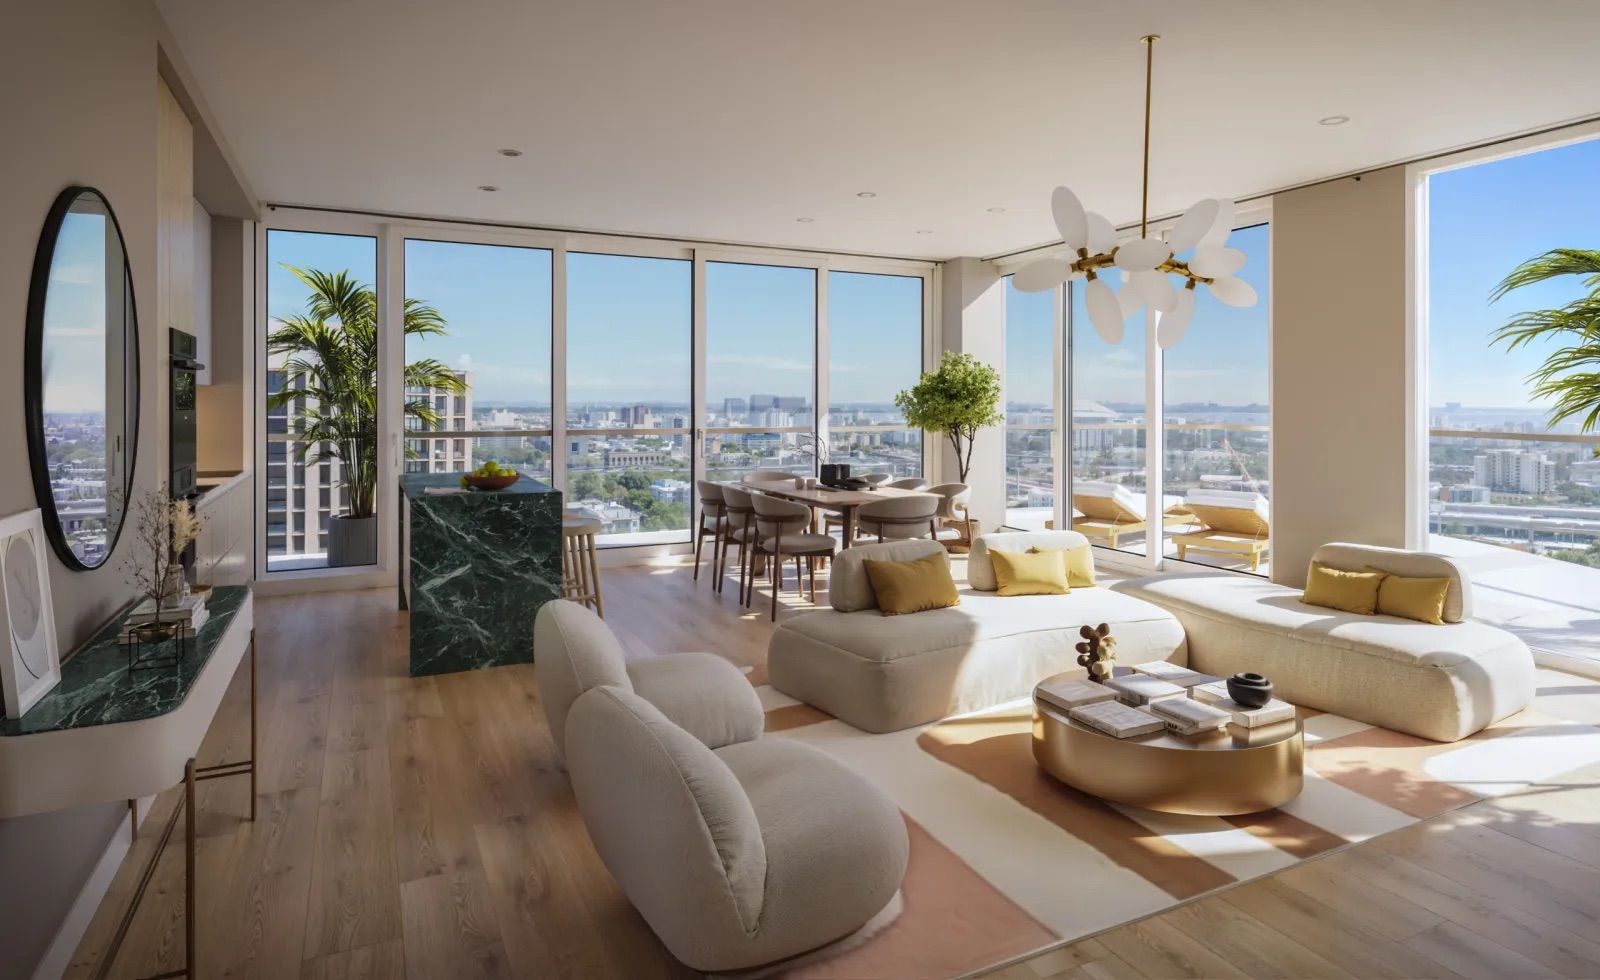
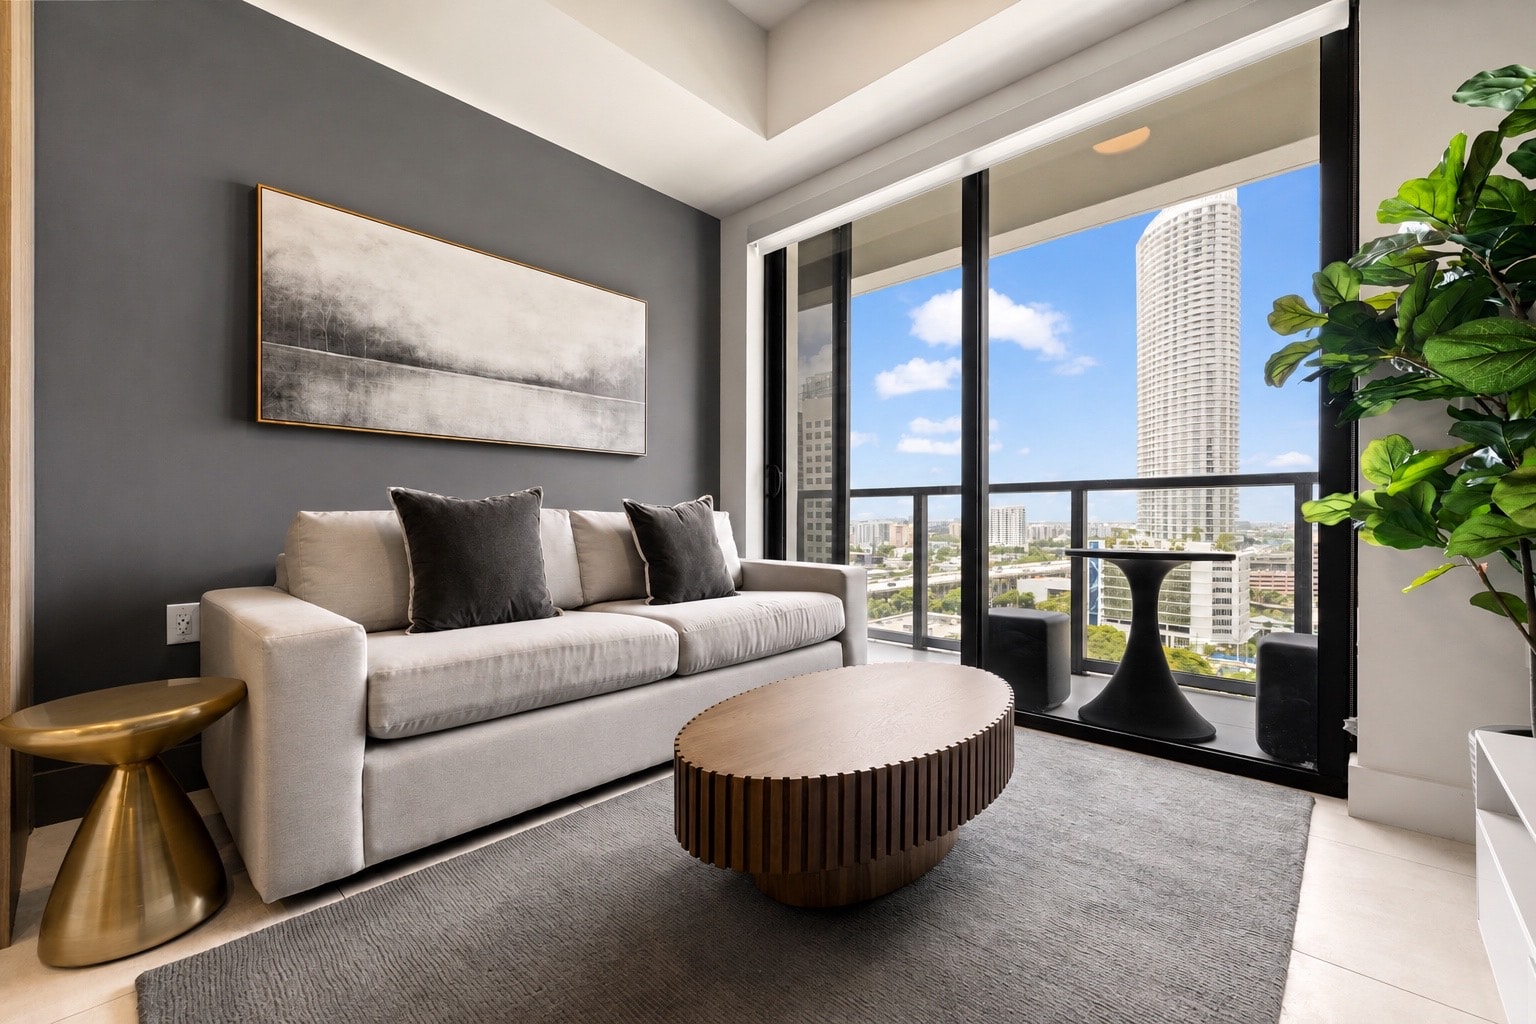
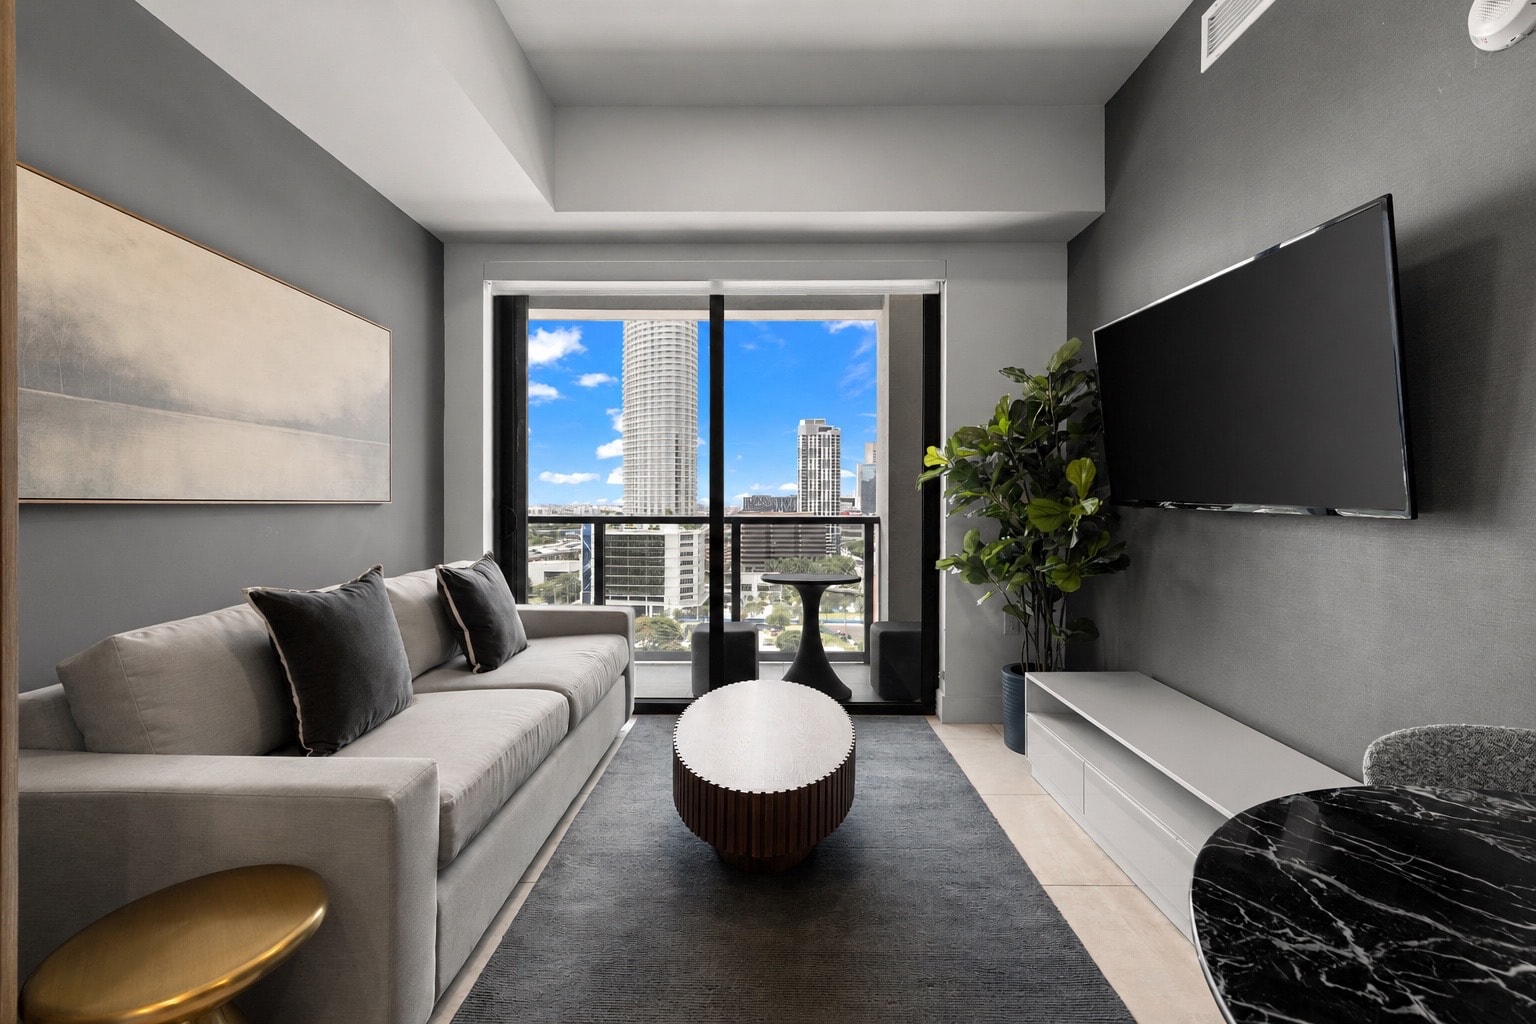
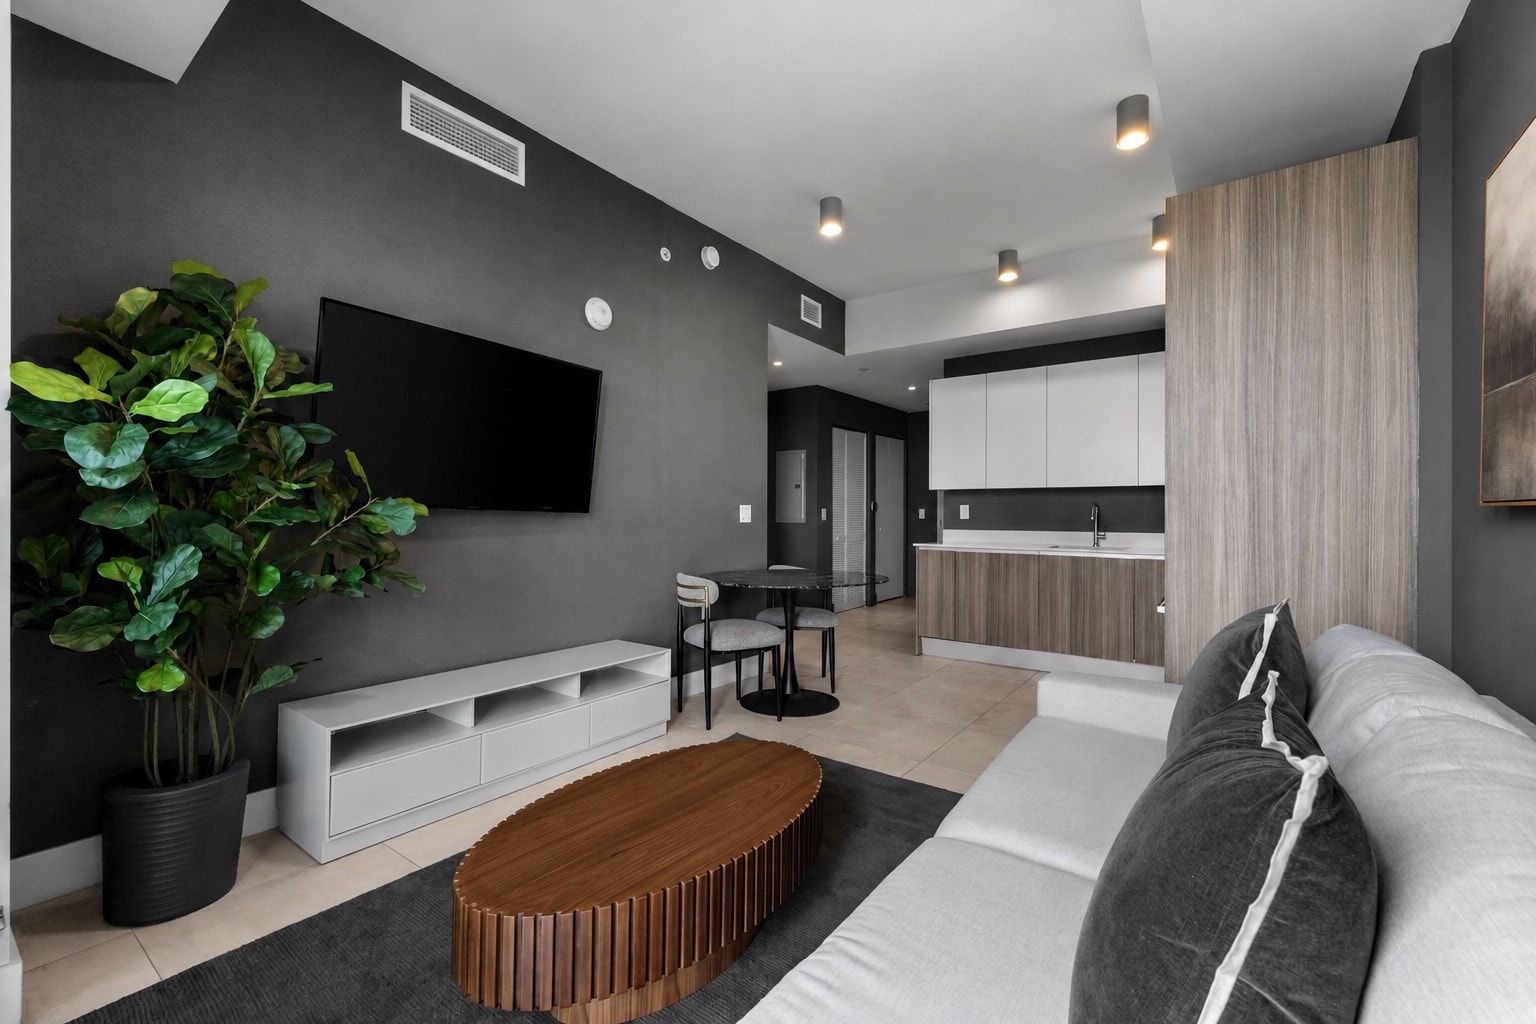
Miami, Florida, USA — 1-Bed Brickell Apartment With Rooftop Pool & Spa
$89,000
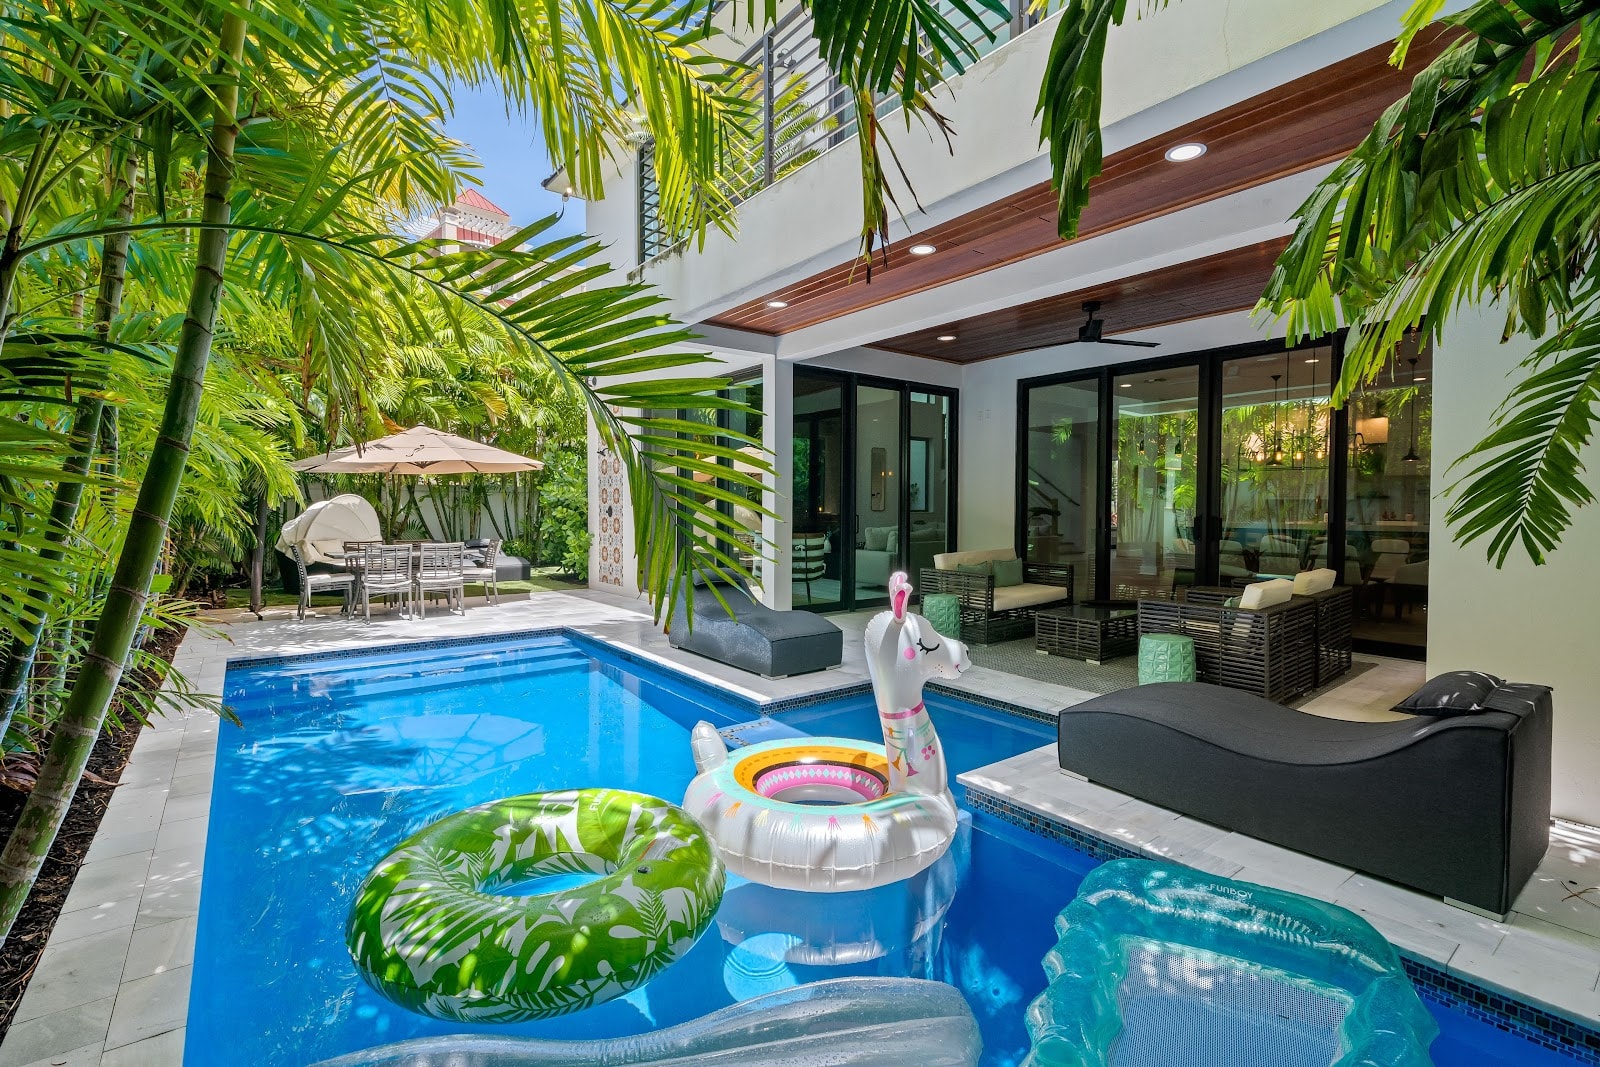
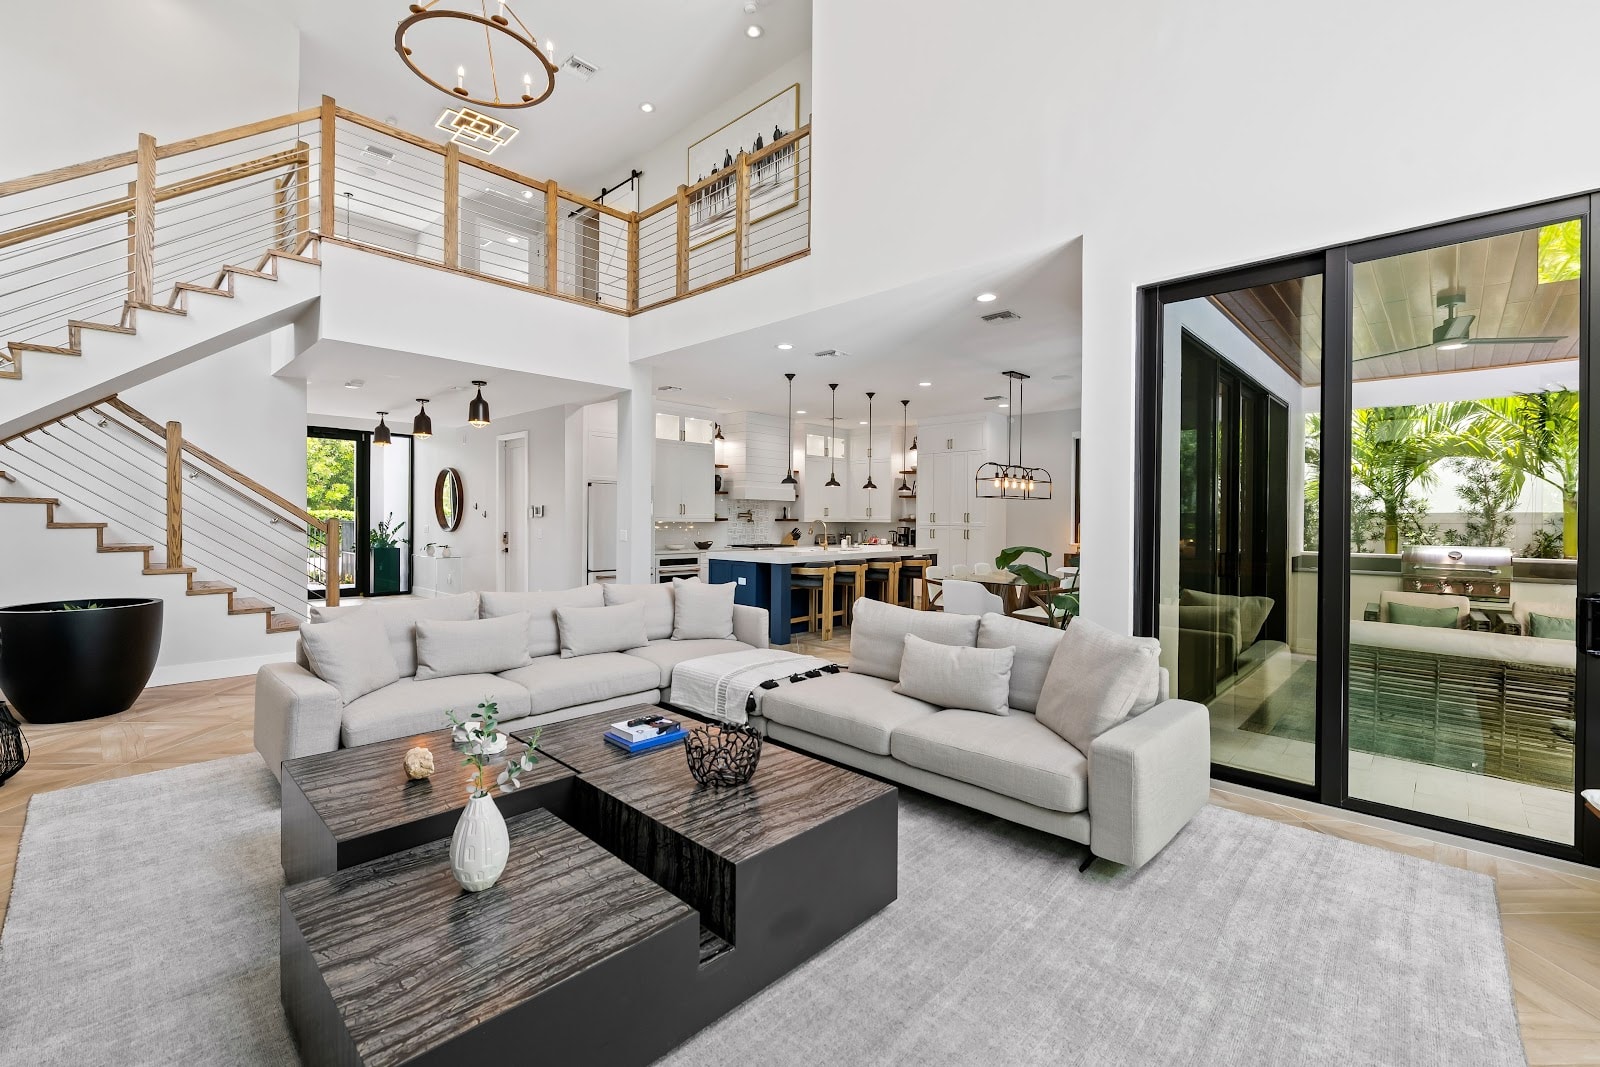
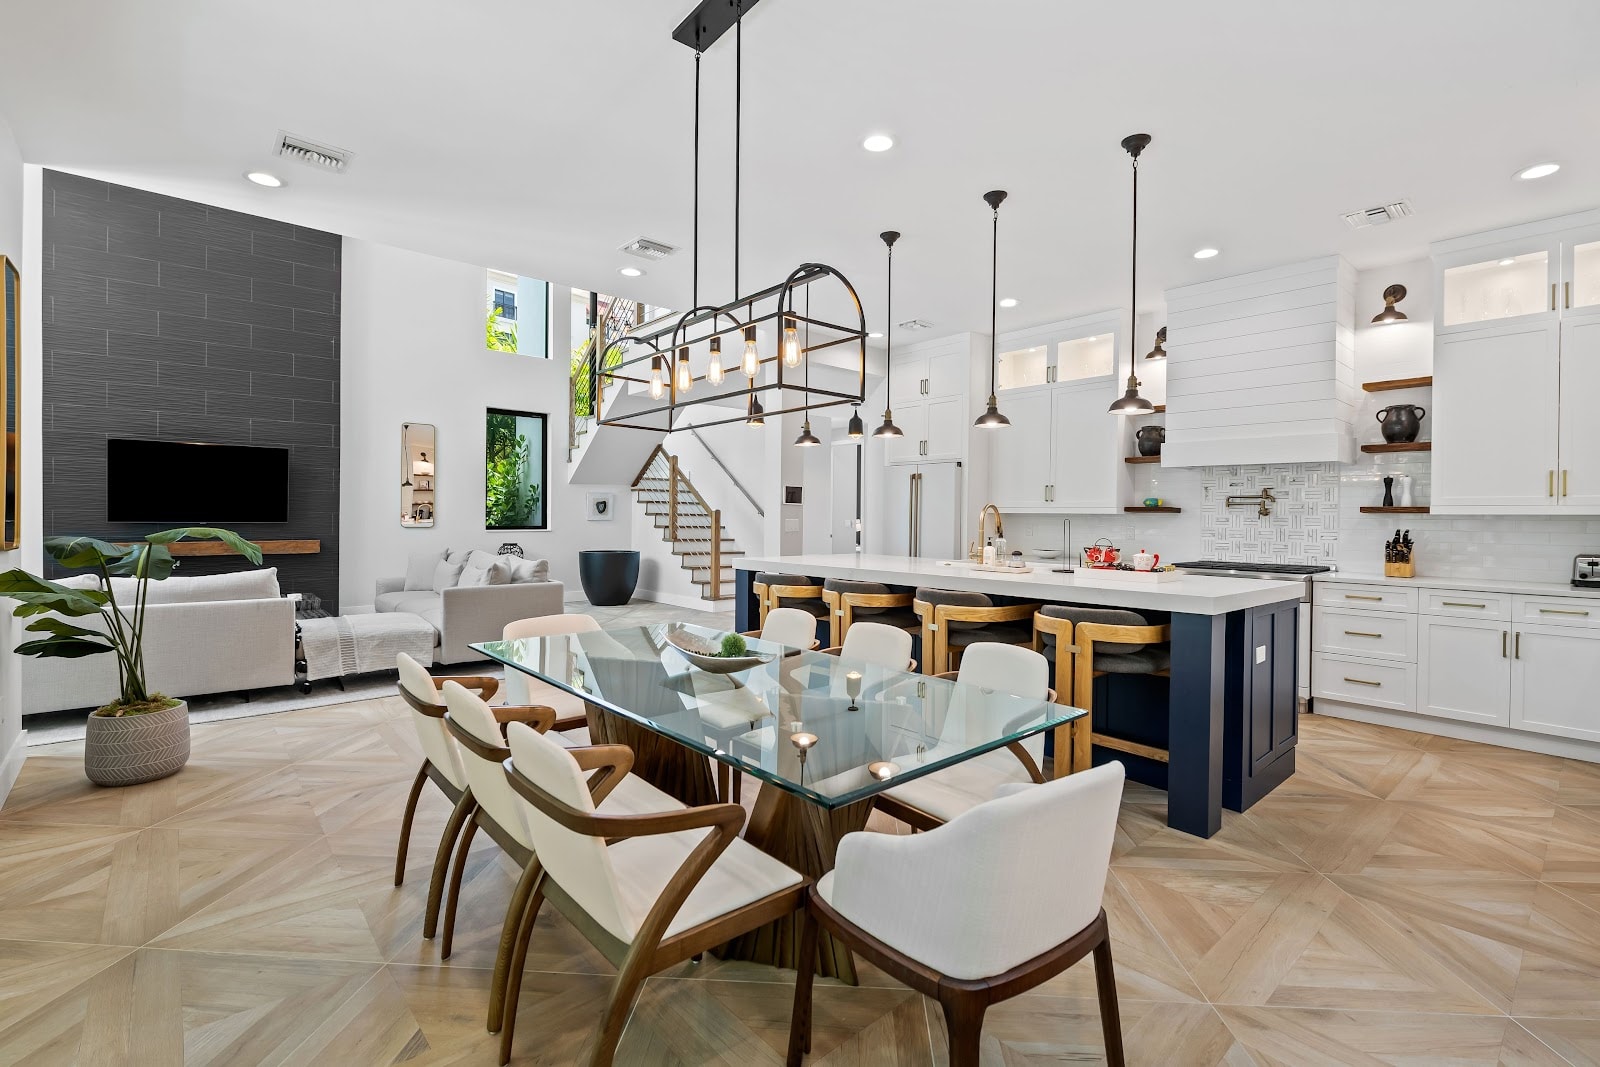
Fort Lauderdale, Florida, USA — 4-Bed House With Beach Access
$450,000
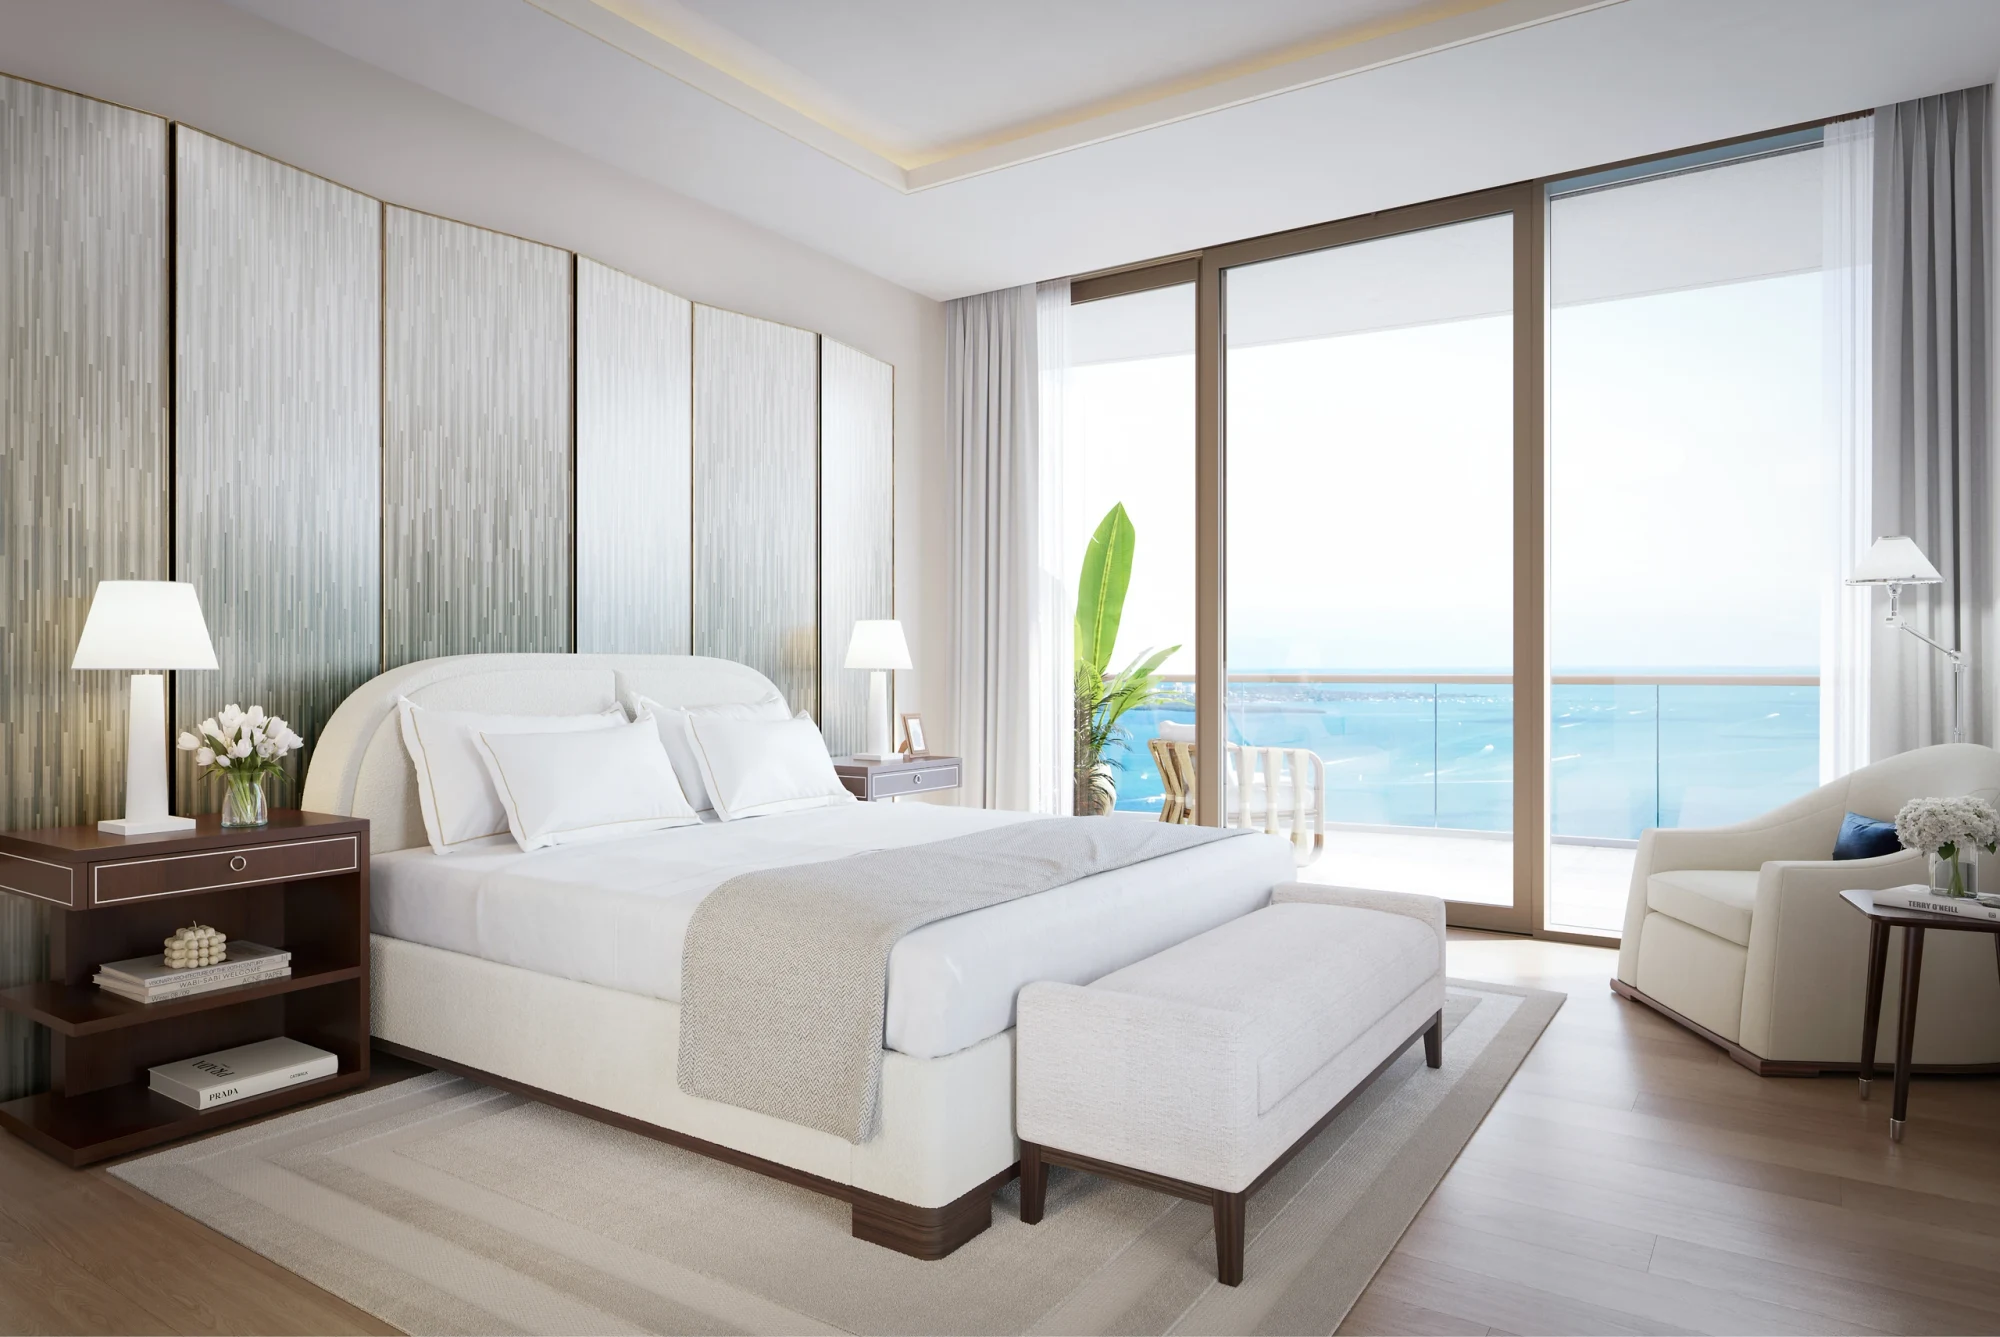
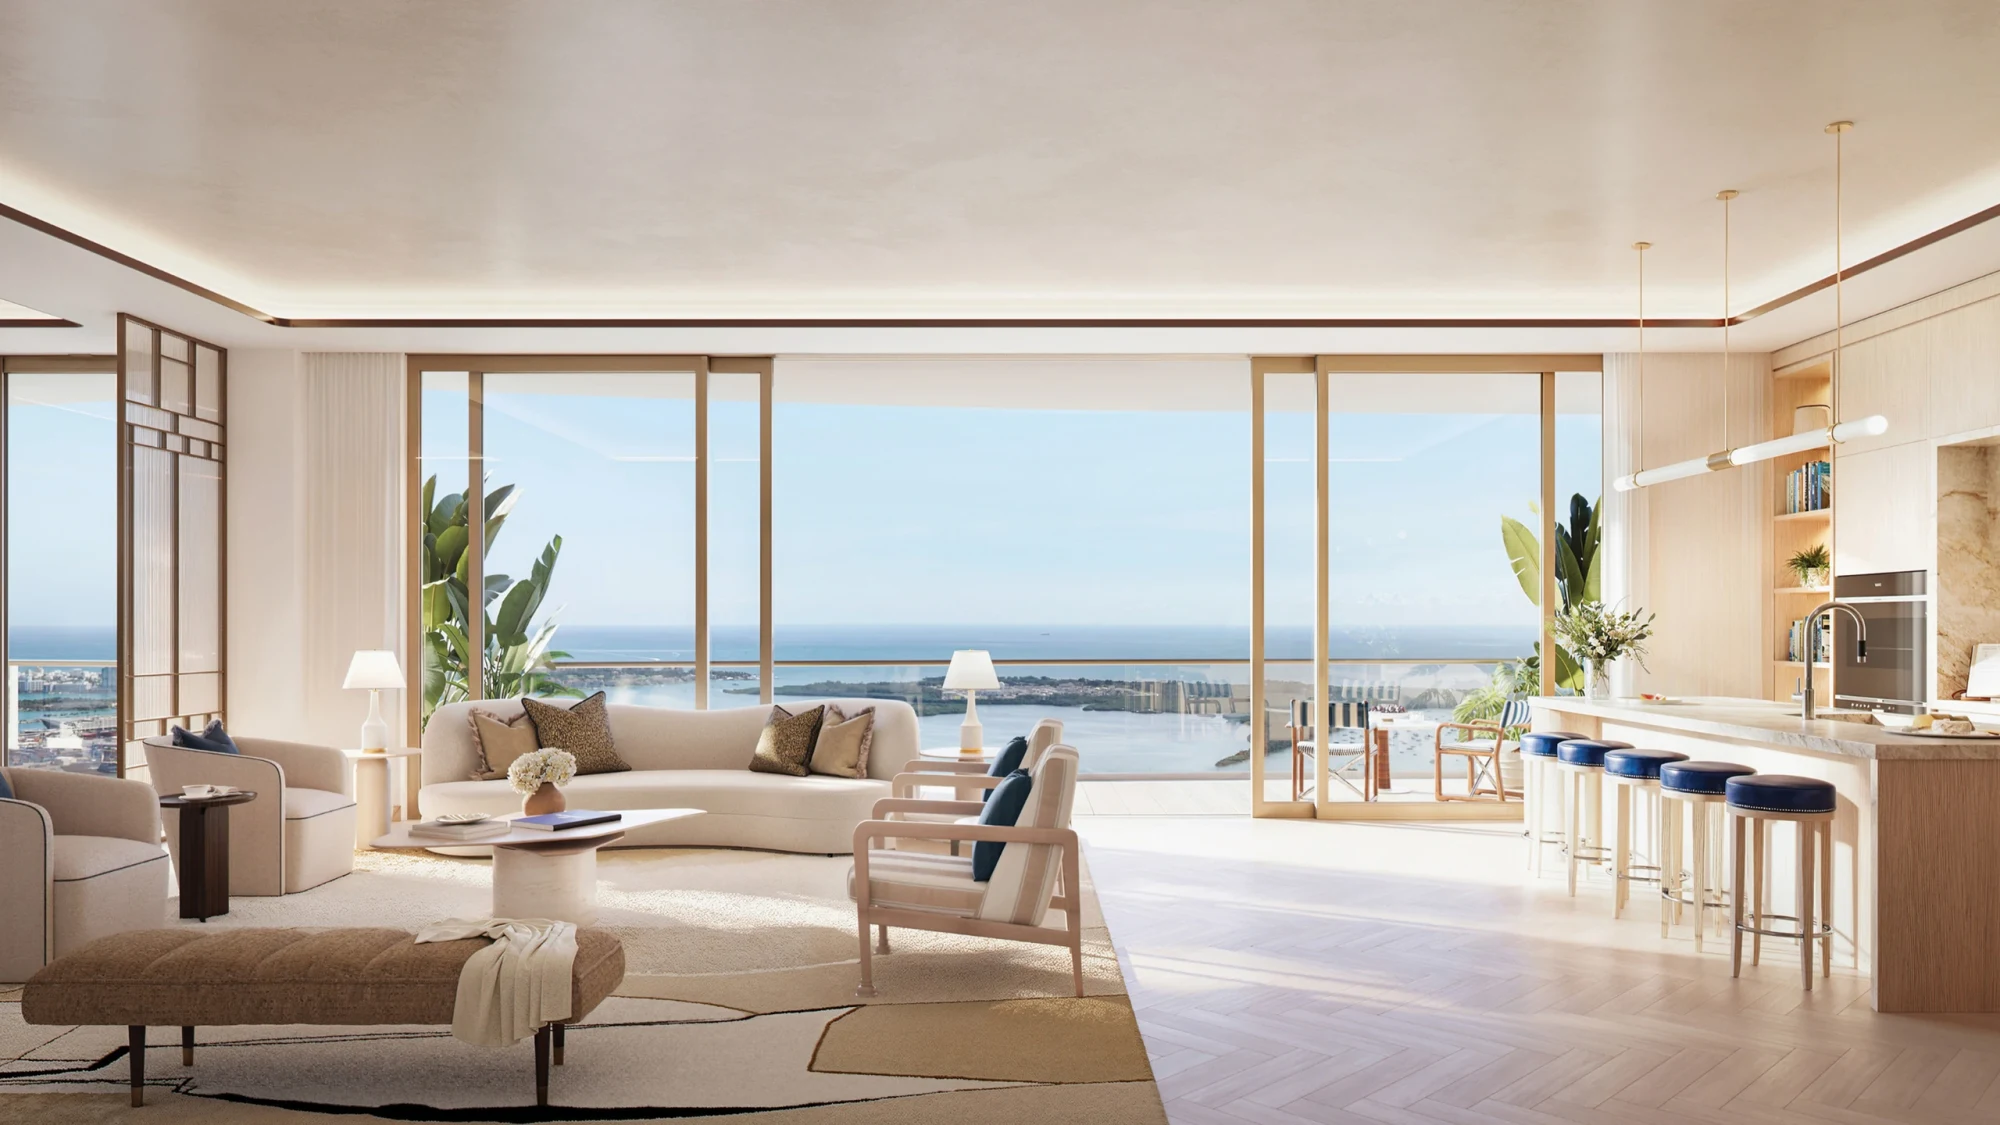
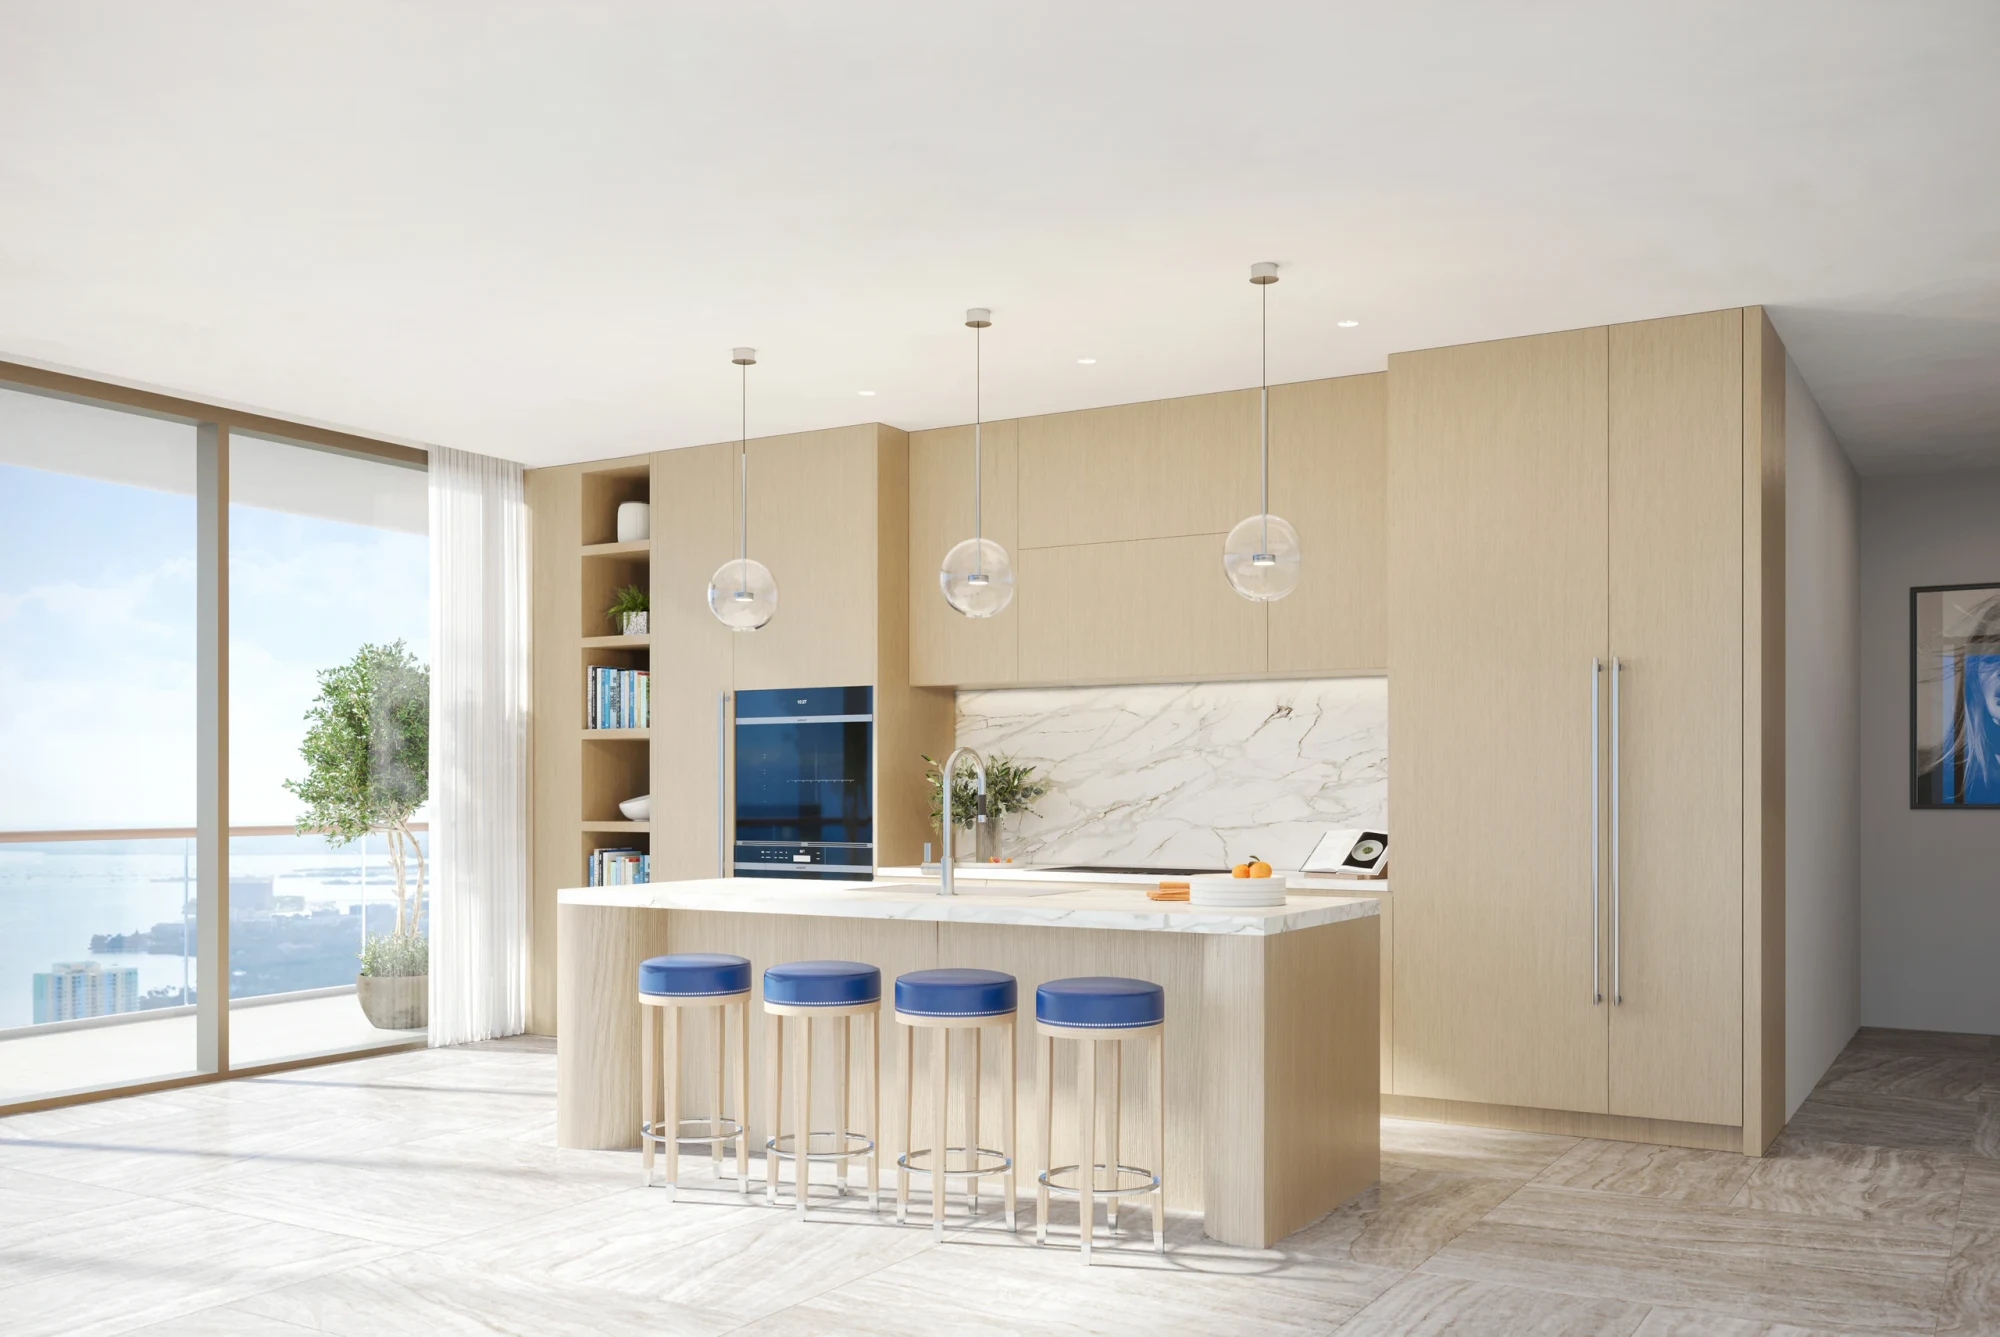
Miami, Florida, USA — 2-Bed Branded Residence With Panoramic Terrace
$444,000
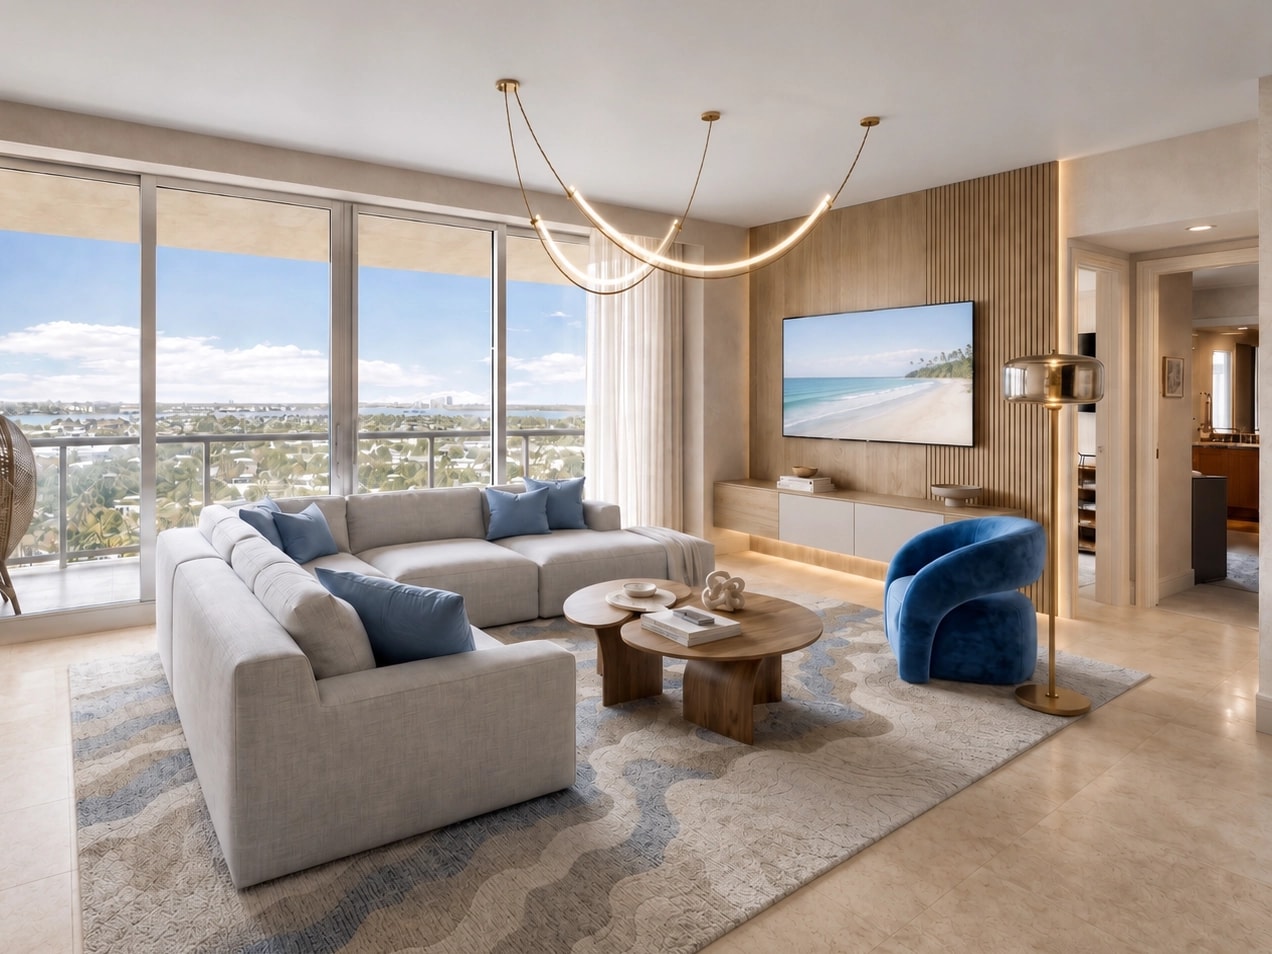
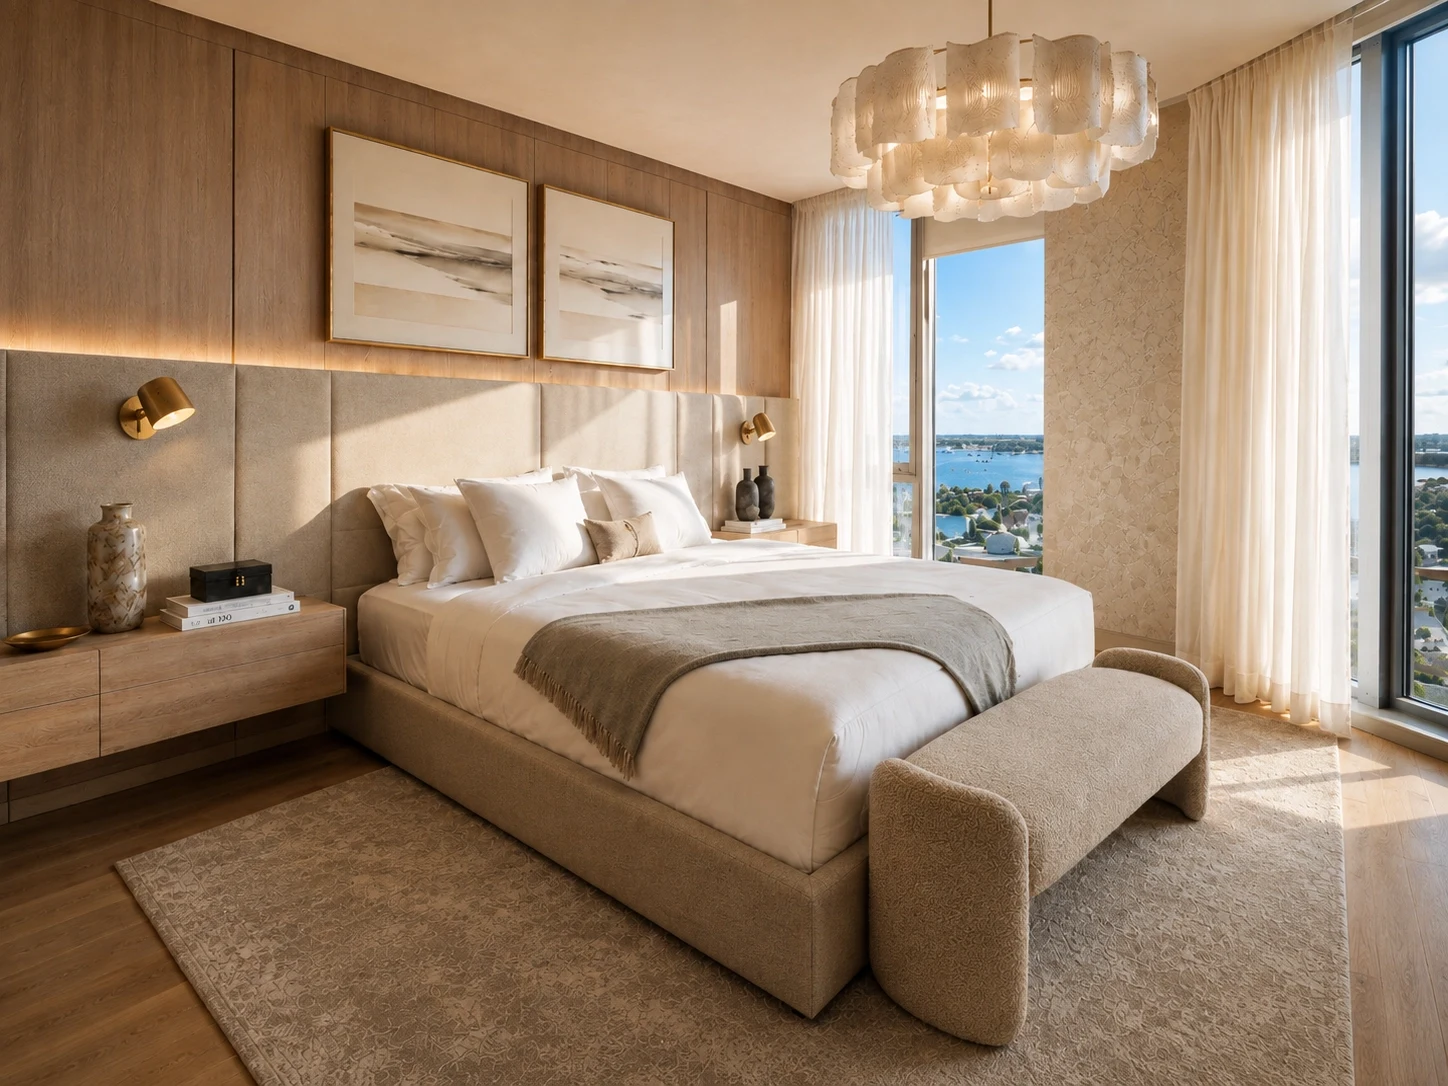
Riviera Beach, Florida, USA — 2-Bed Beachfront Residence With Private Beach
$301,000
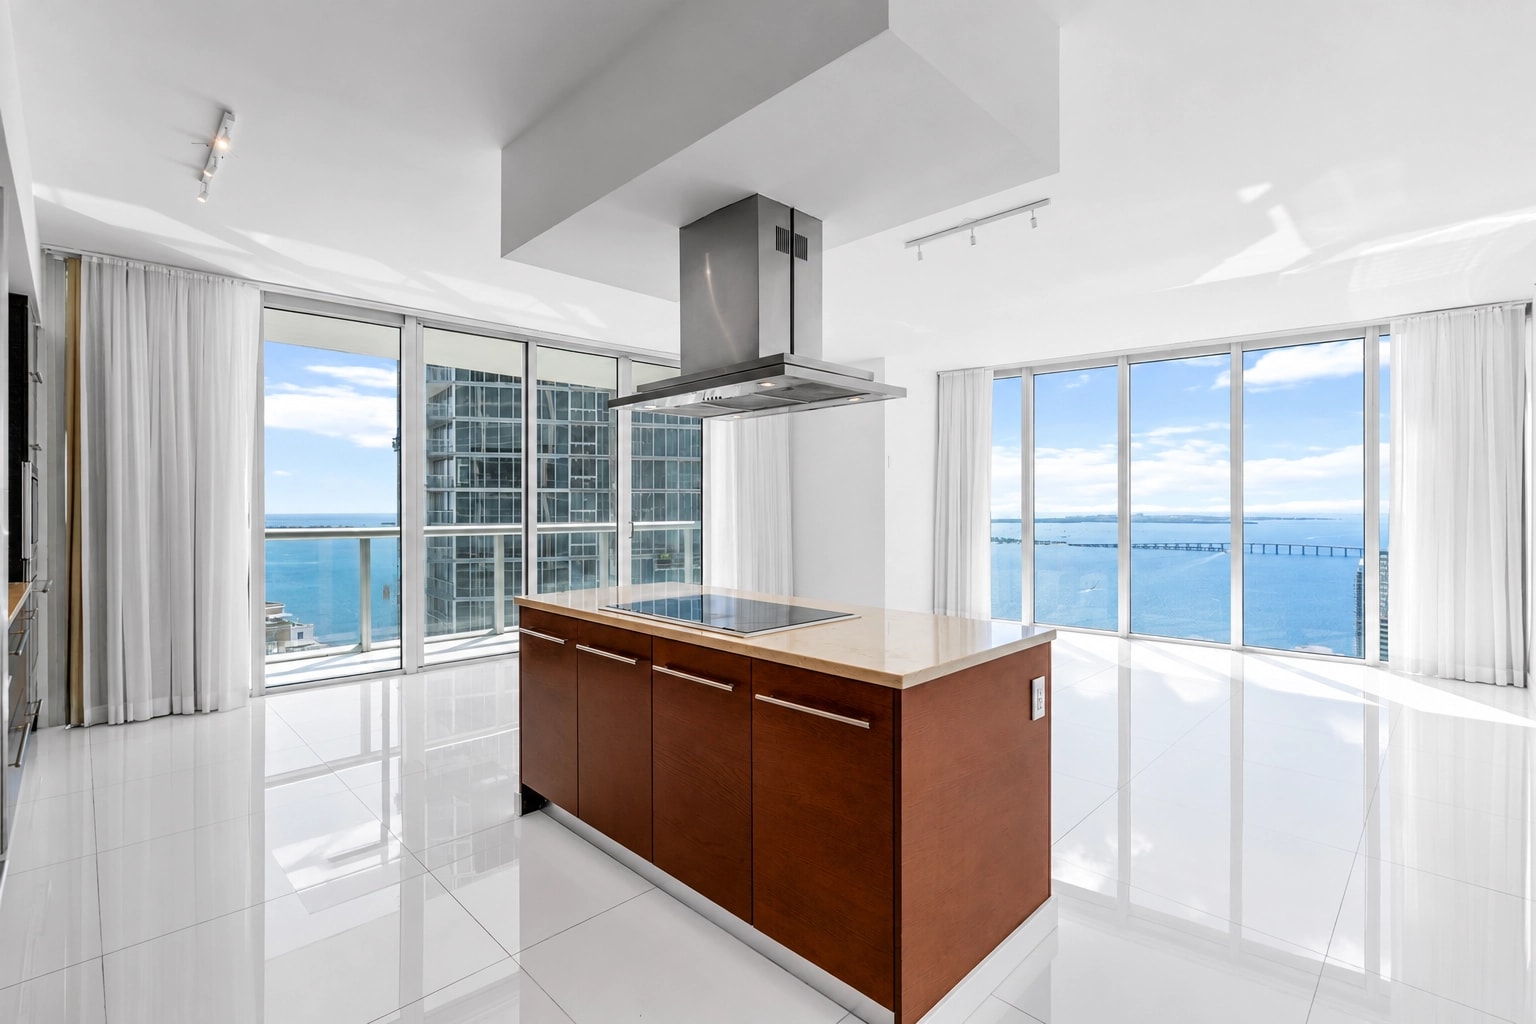
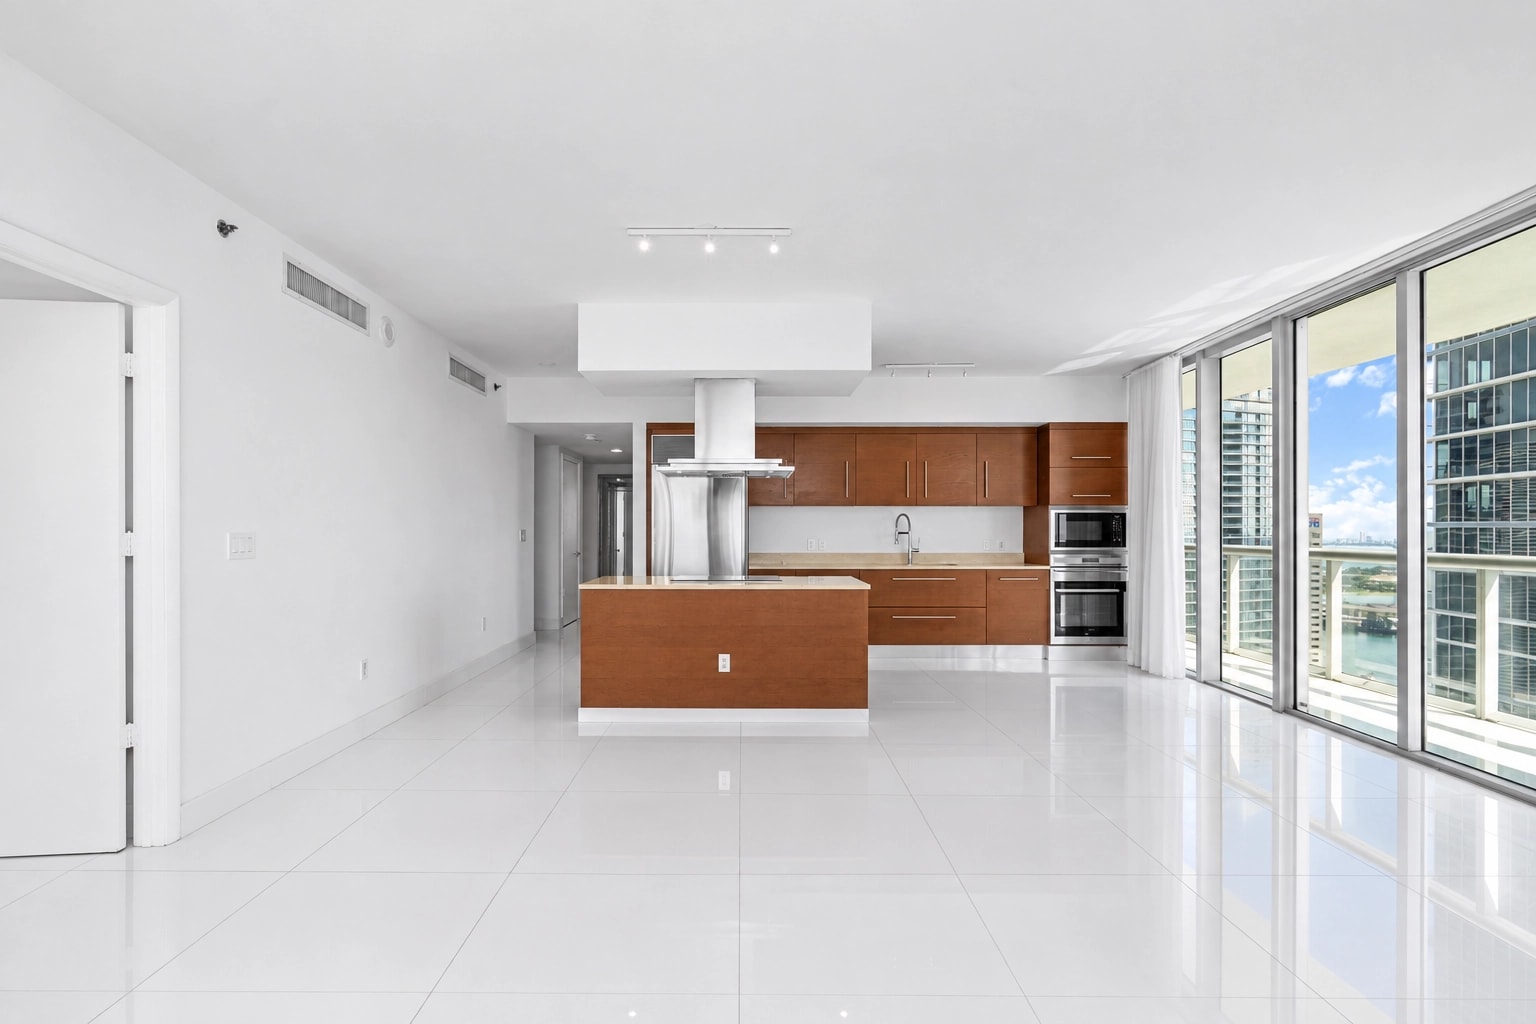
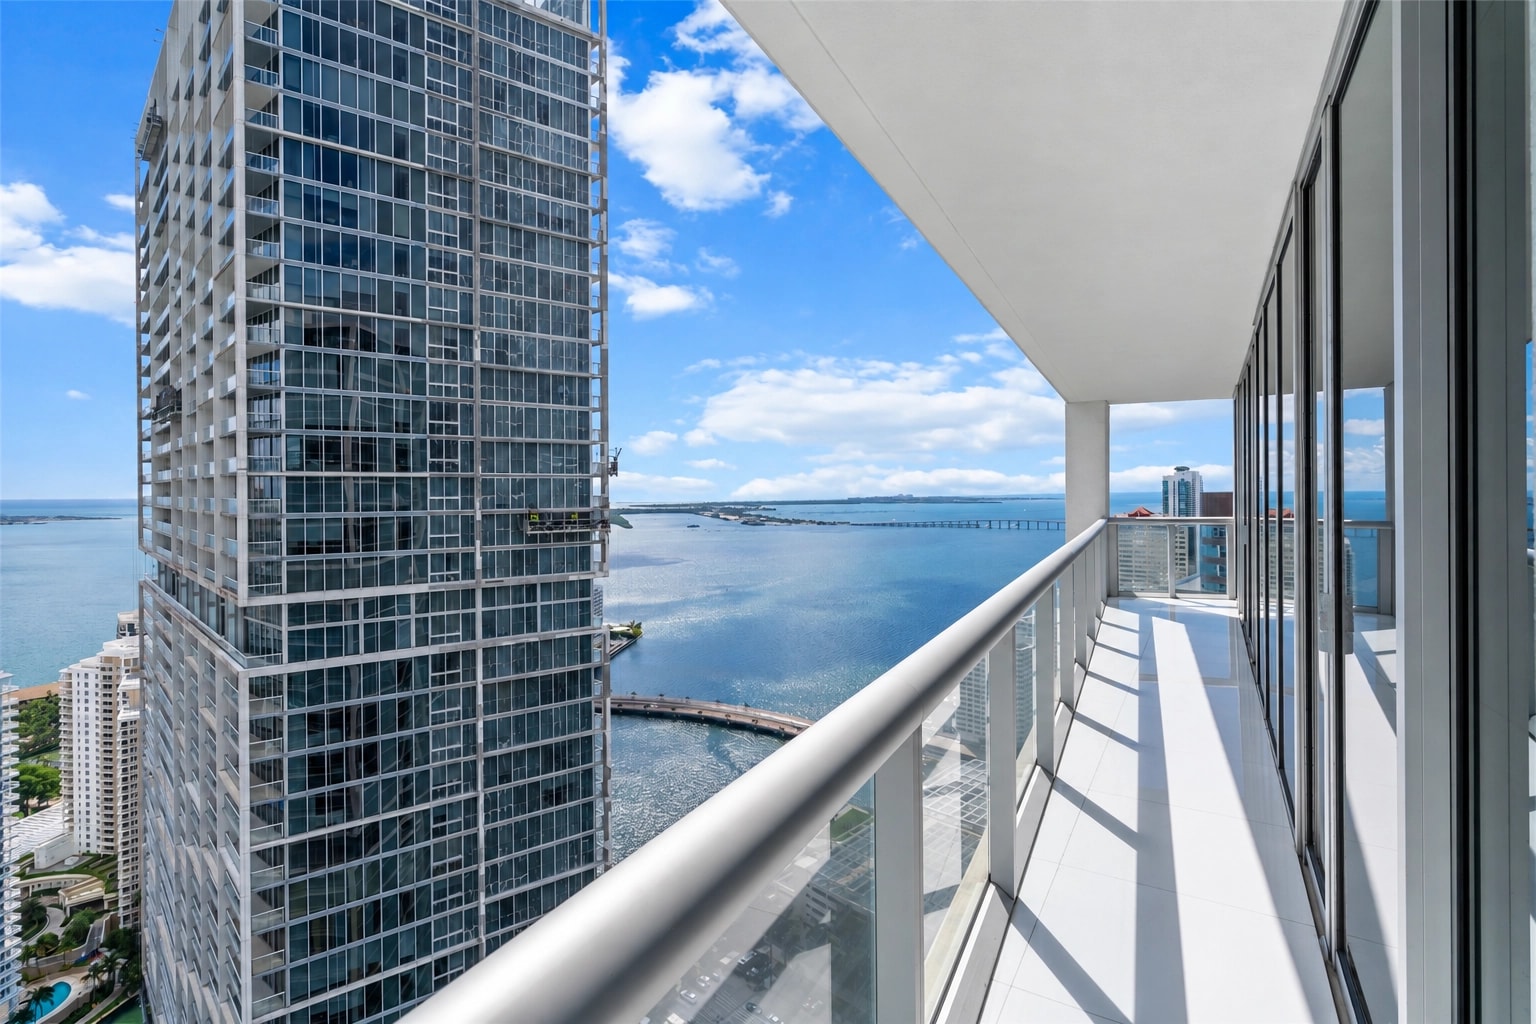
Miami, Florida, USA — 2-Bed Waterfront Apartment With Water & Skyline Views
$173,000
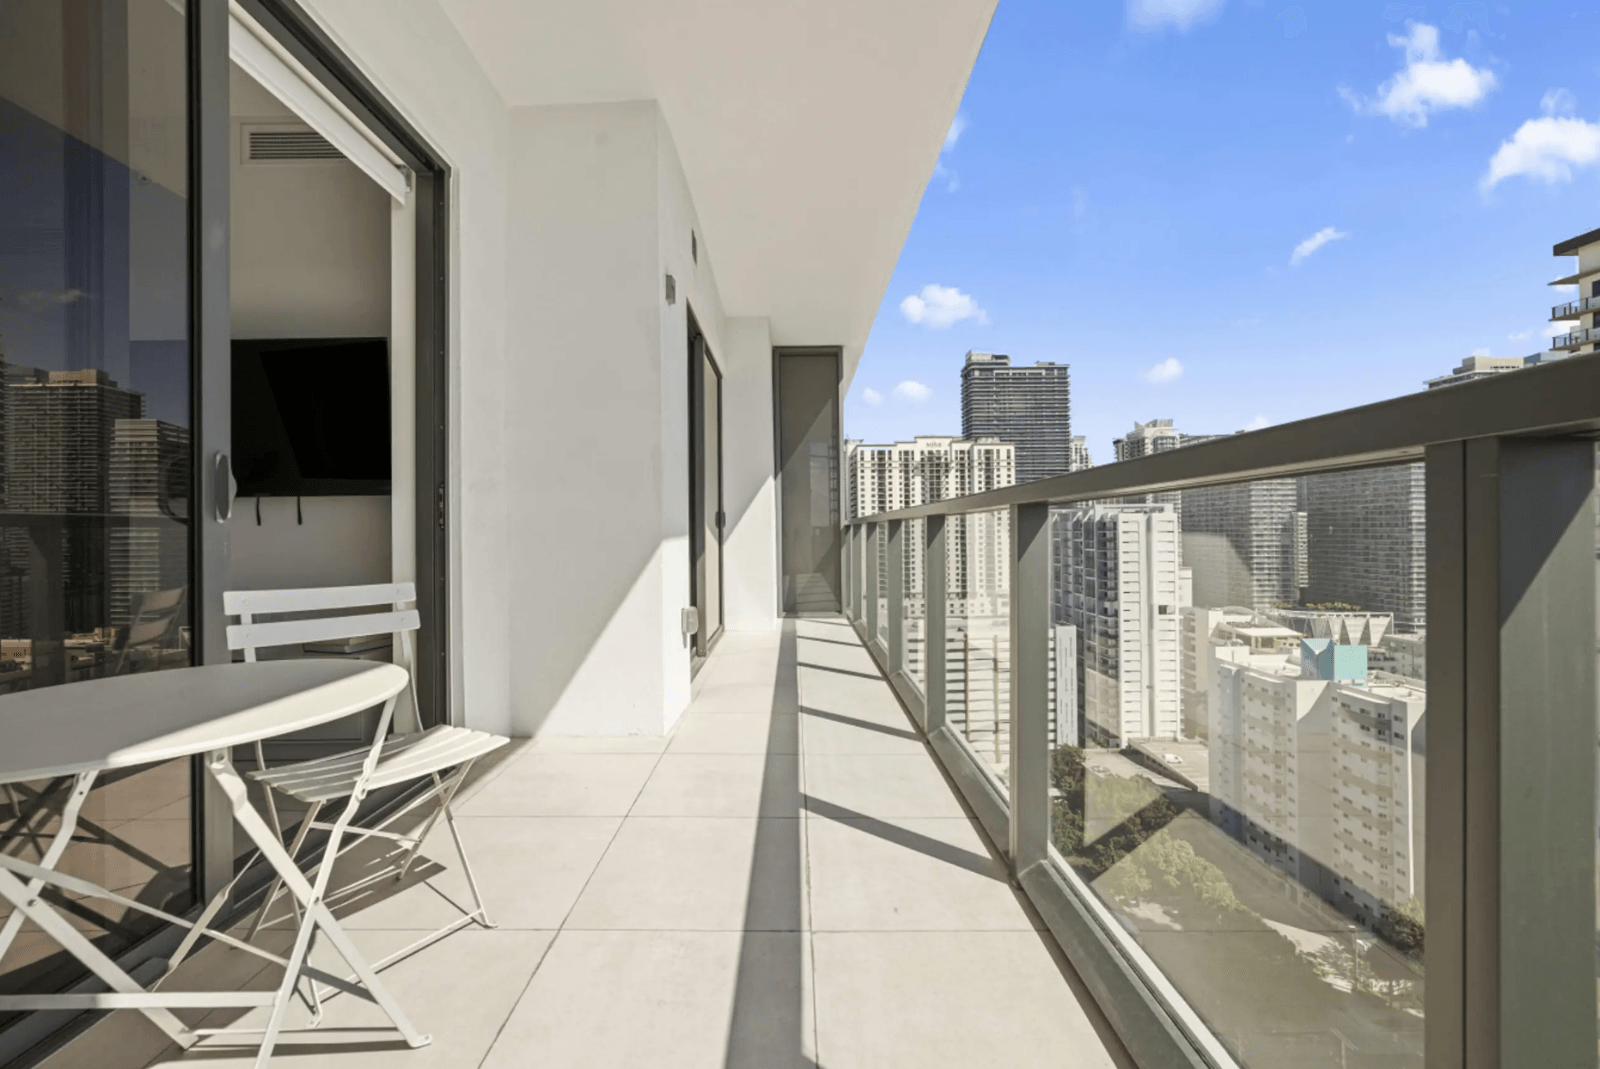
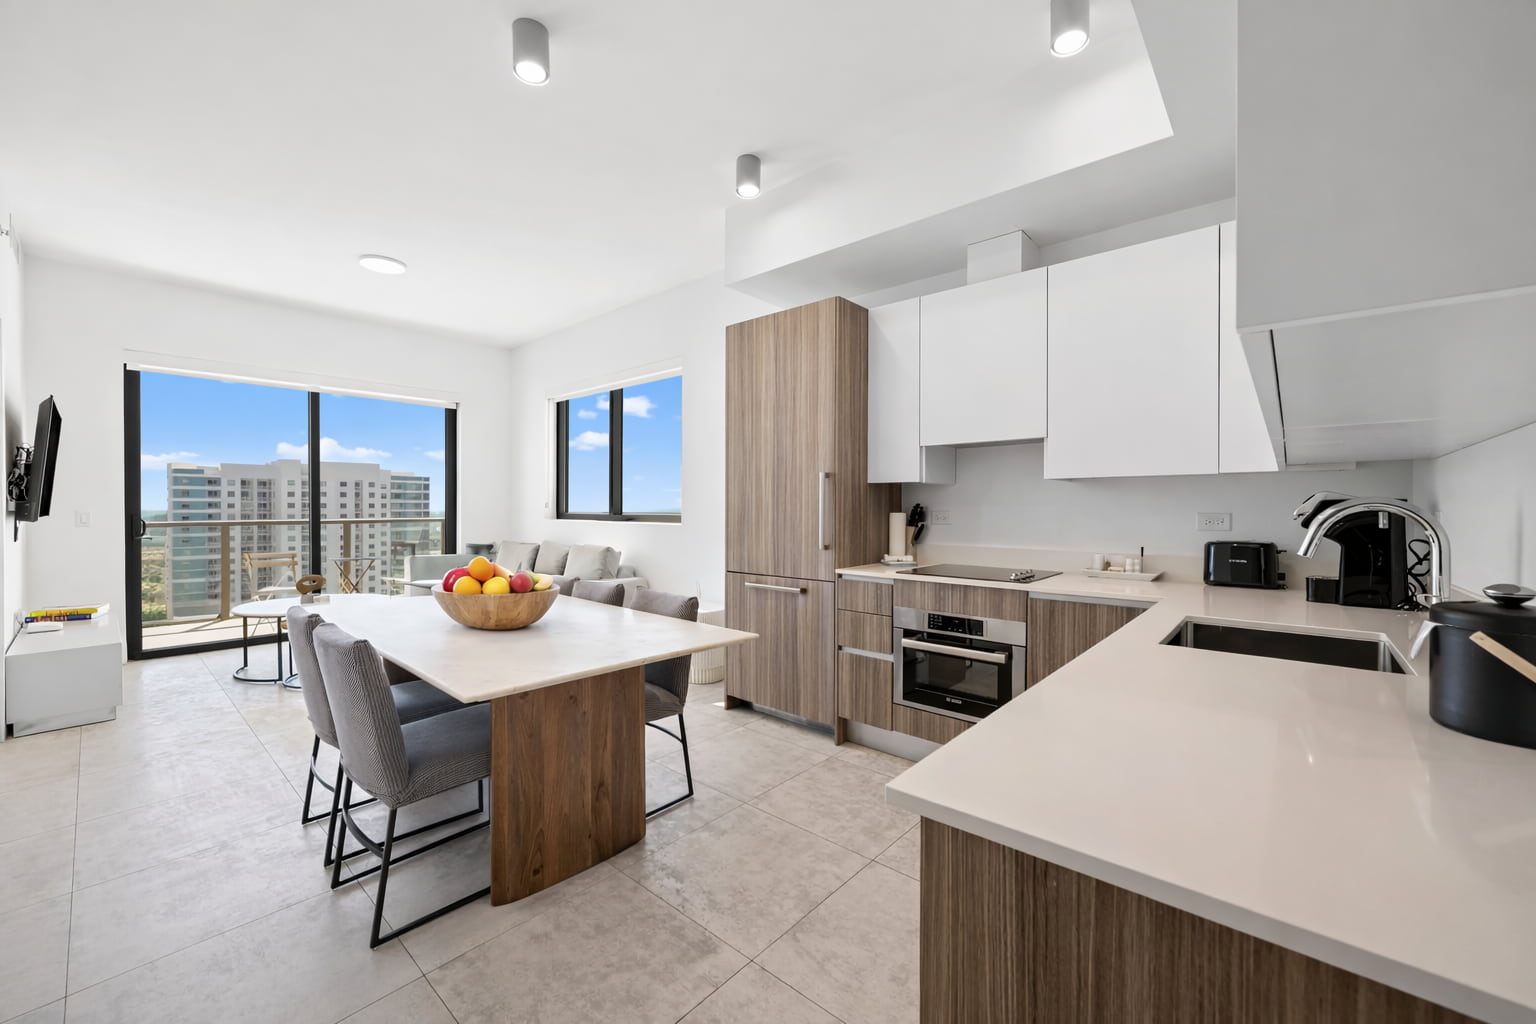
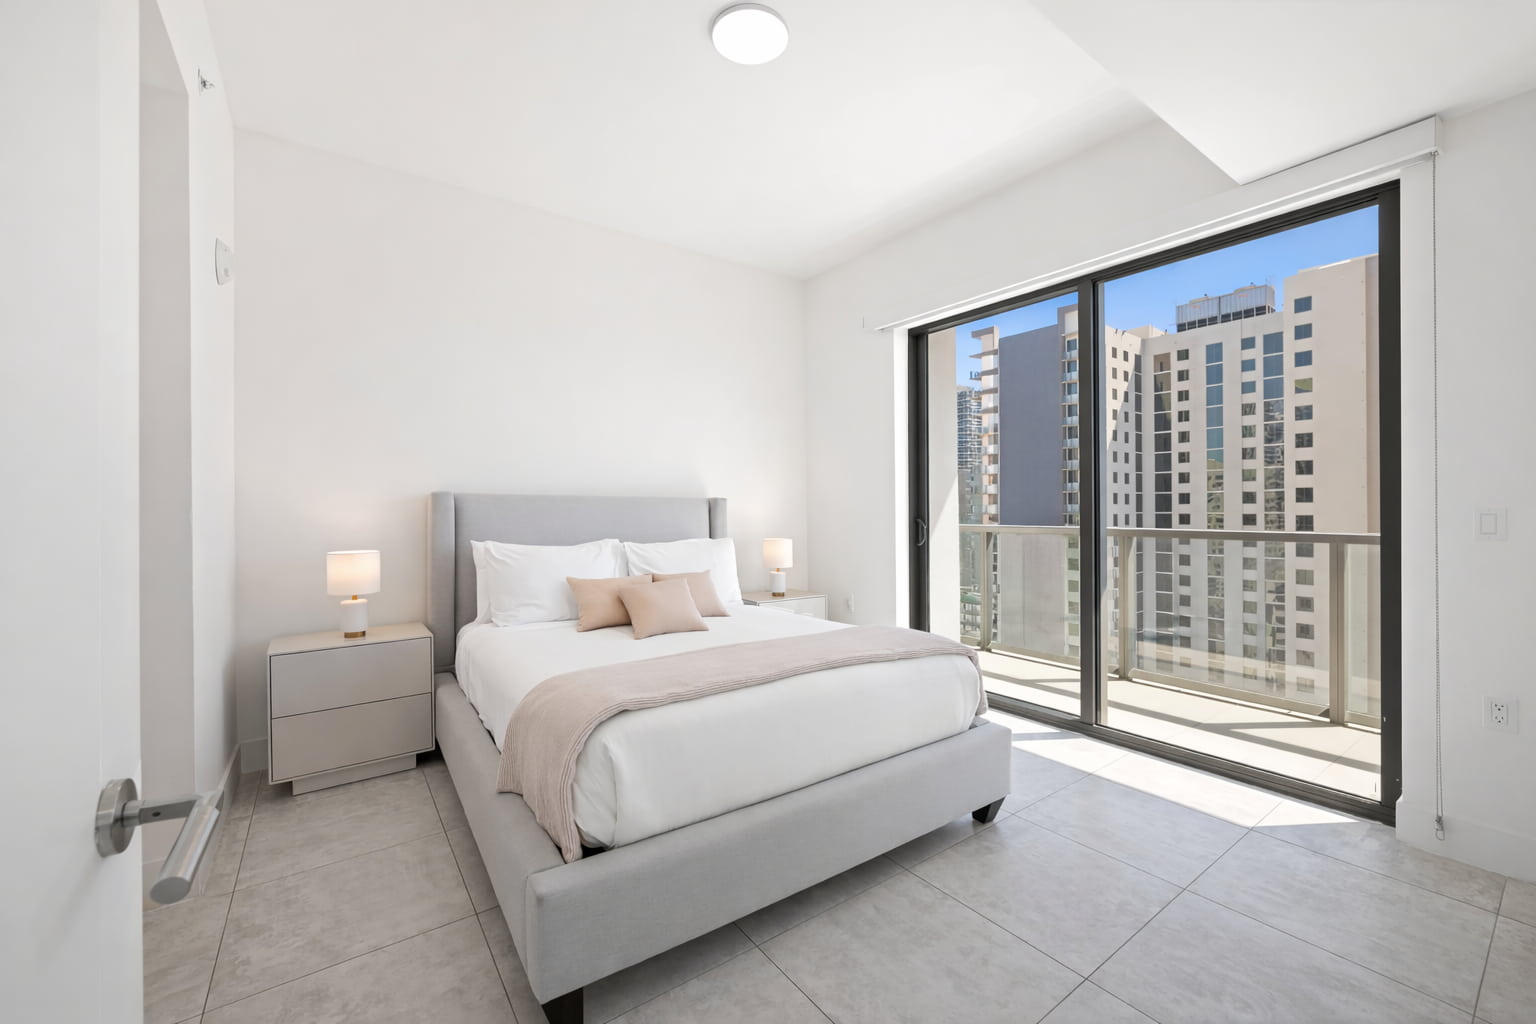
Miami, Florida, USA — 2-Bed+Den Apartment With Pool
$113,000
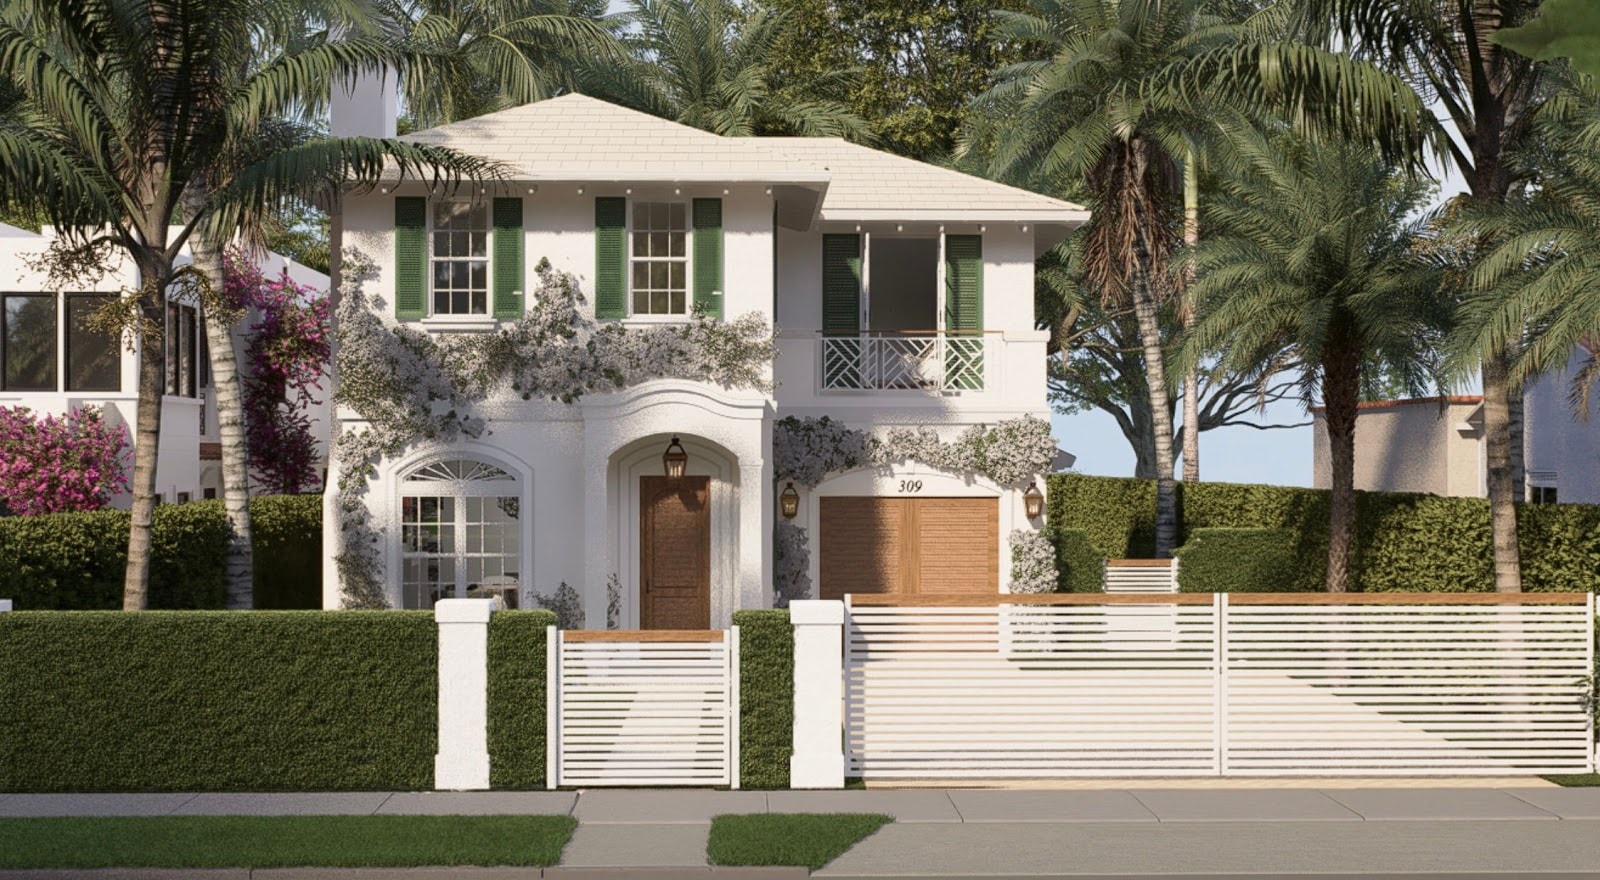
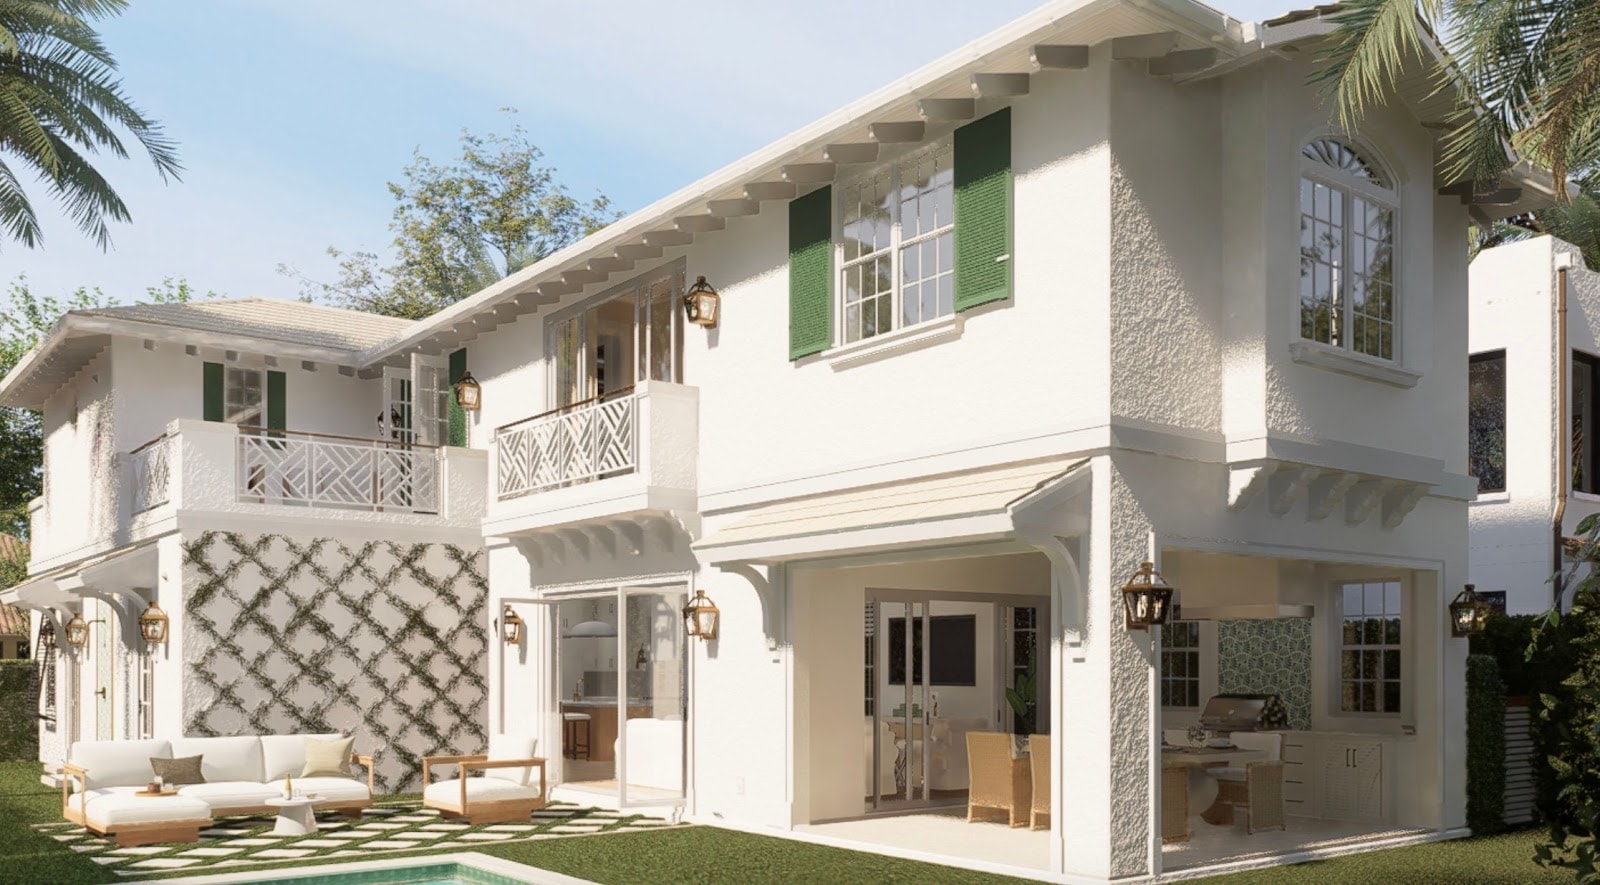
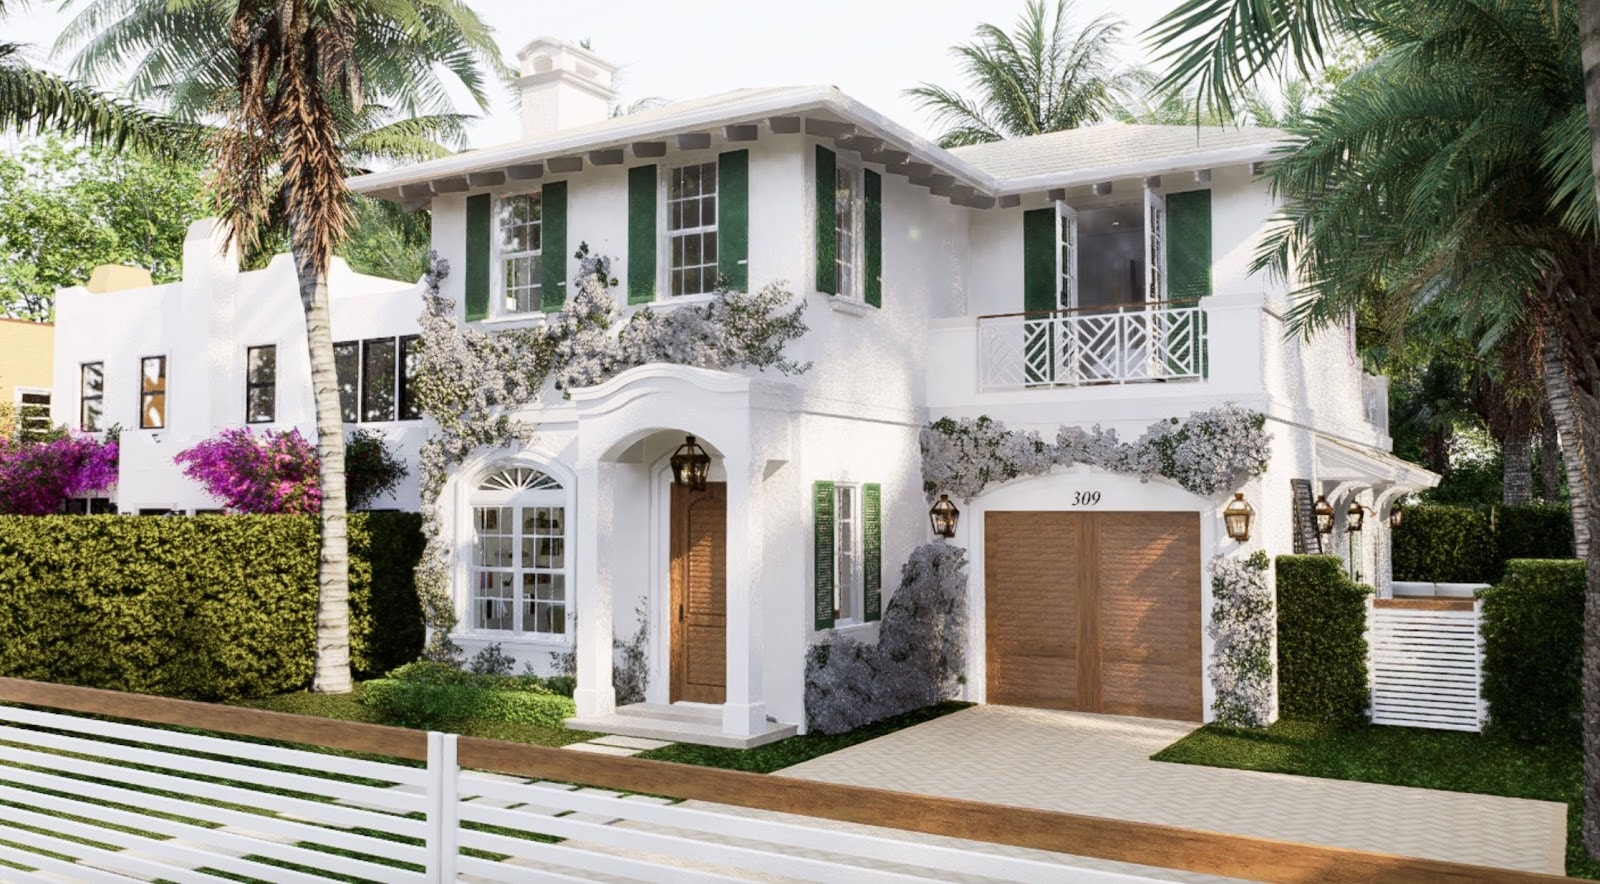
West Palm Beach, Florida, USA — 4-Bed House With Pool
$799,000
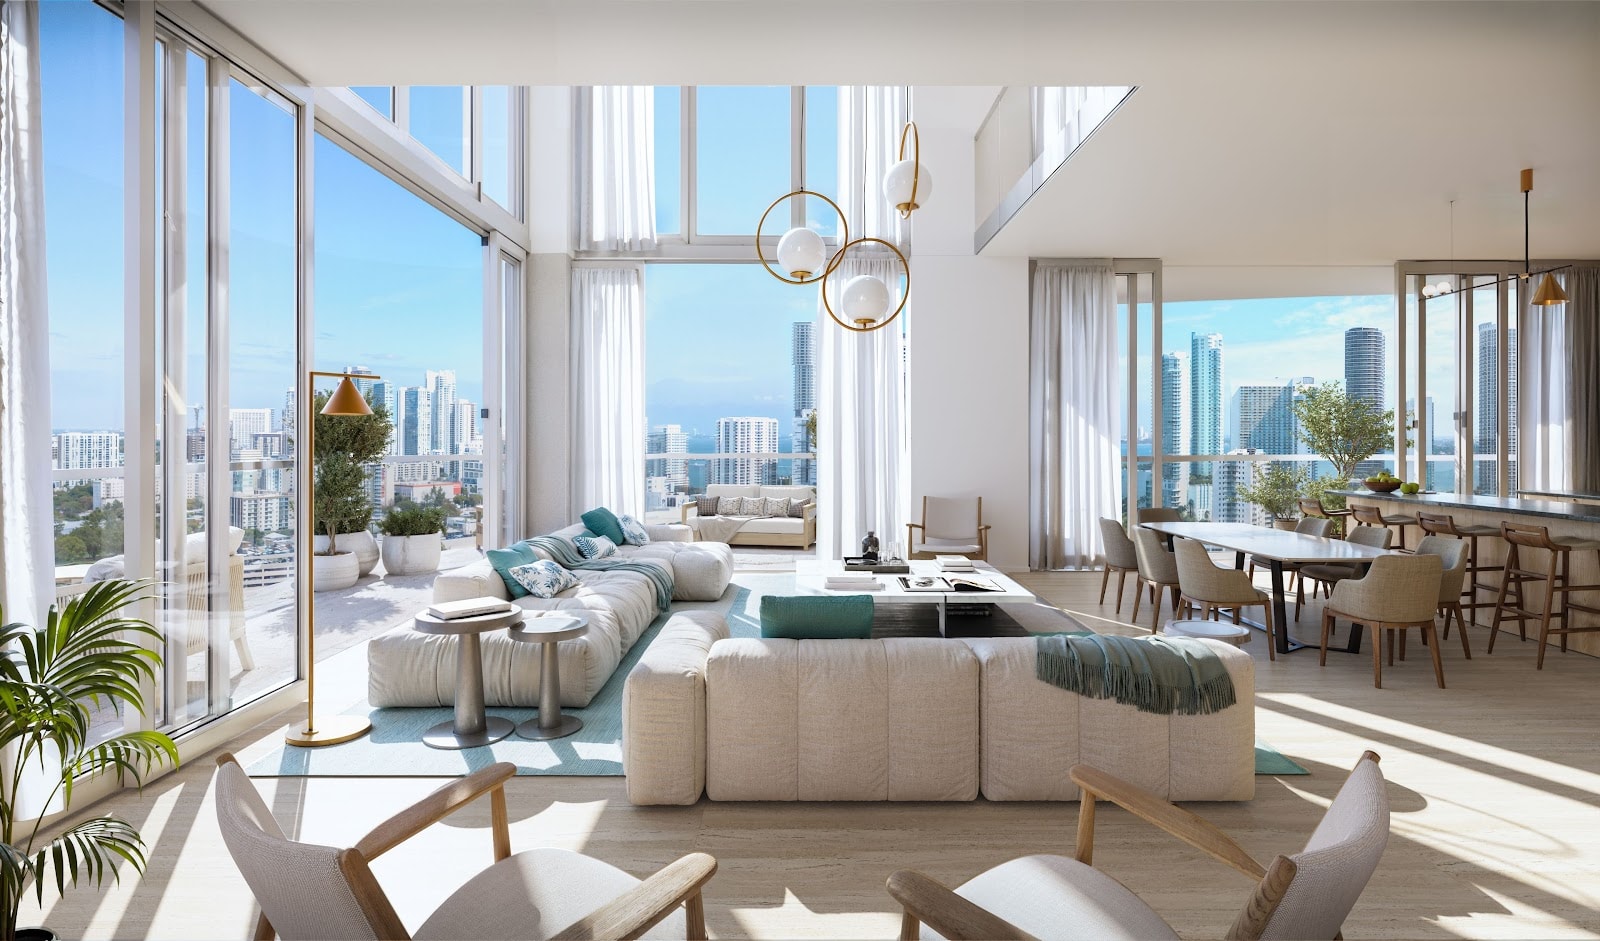
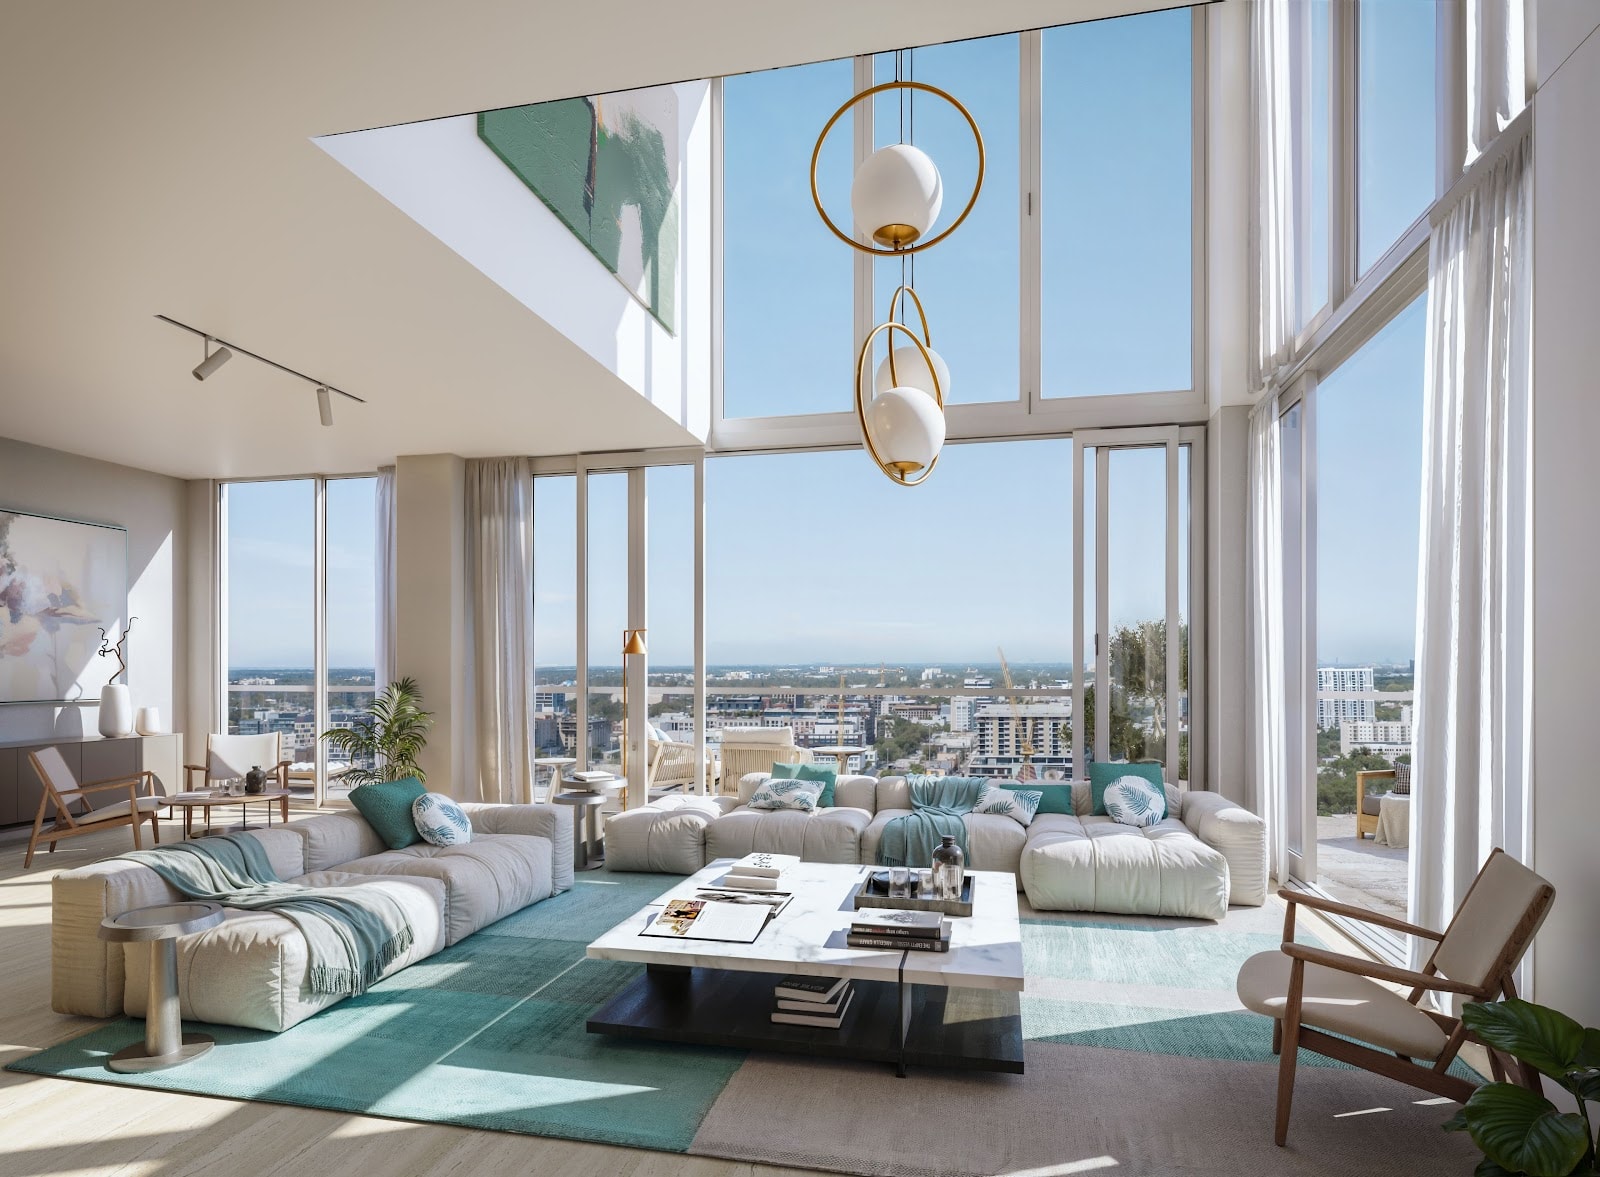
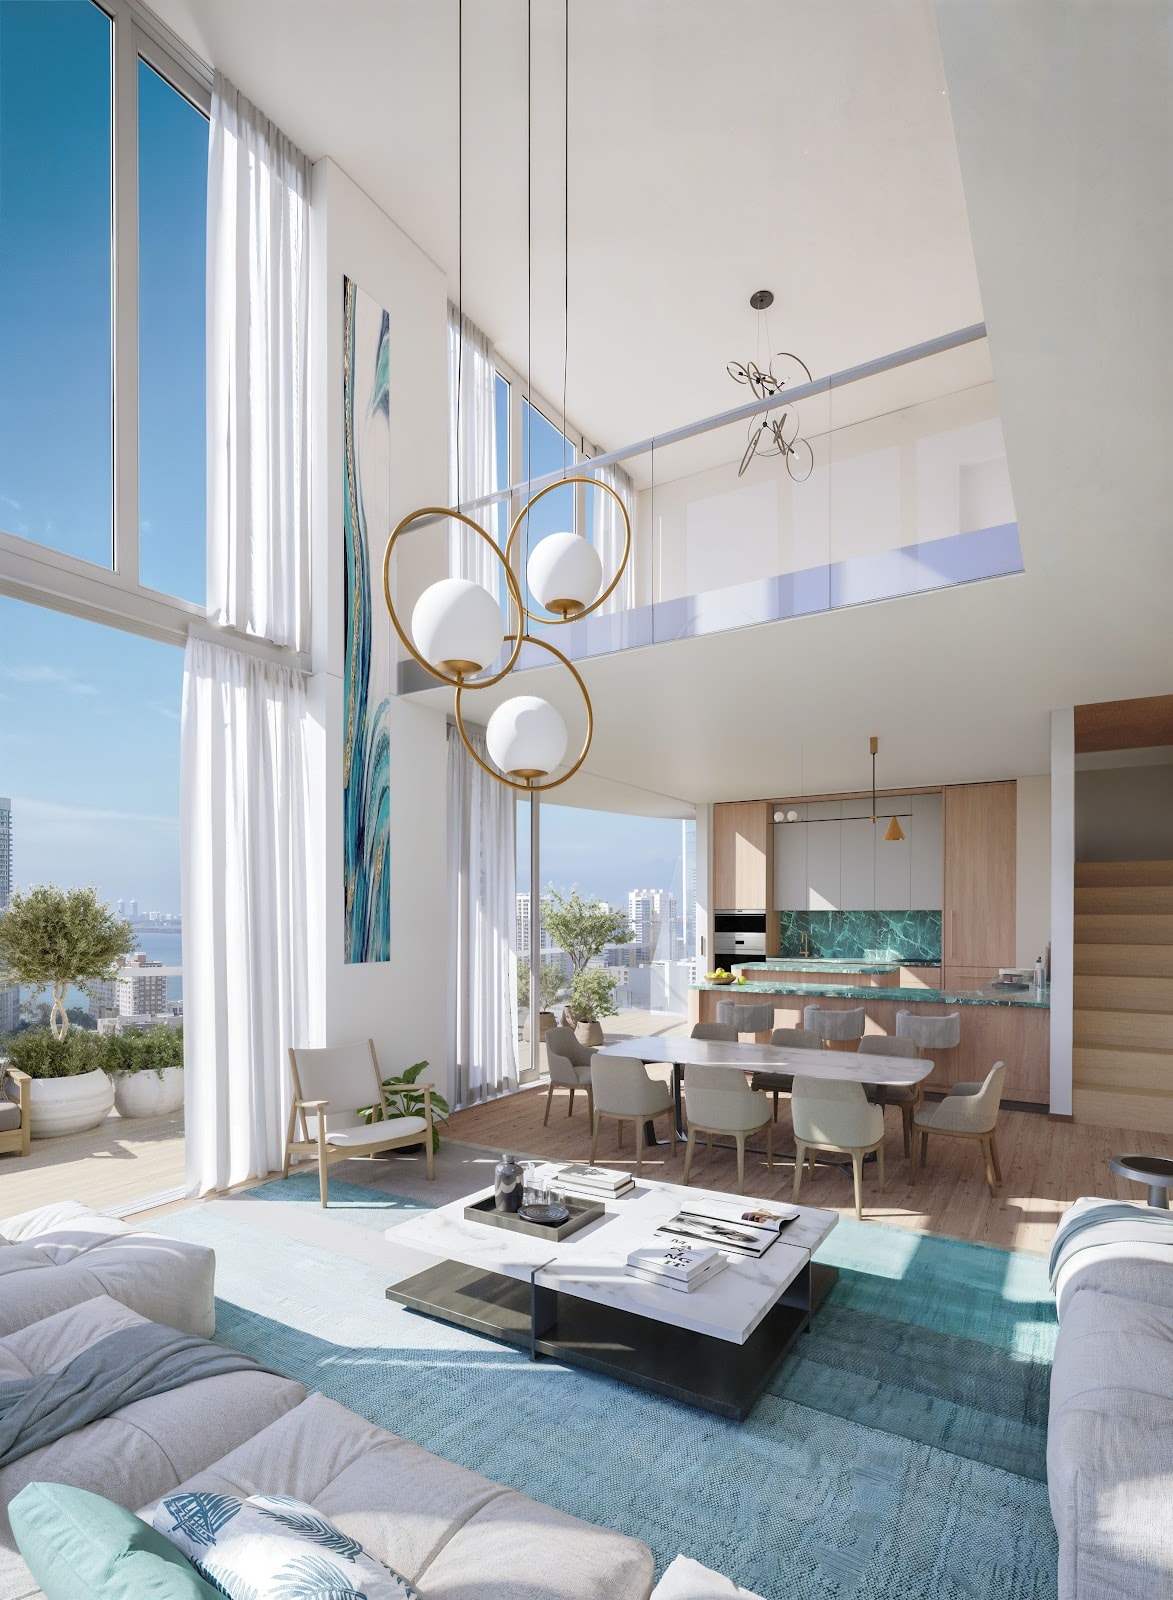
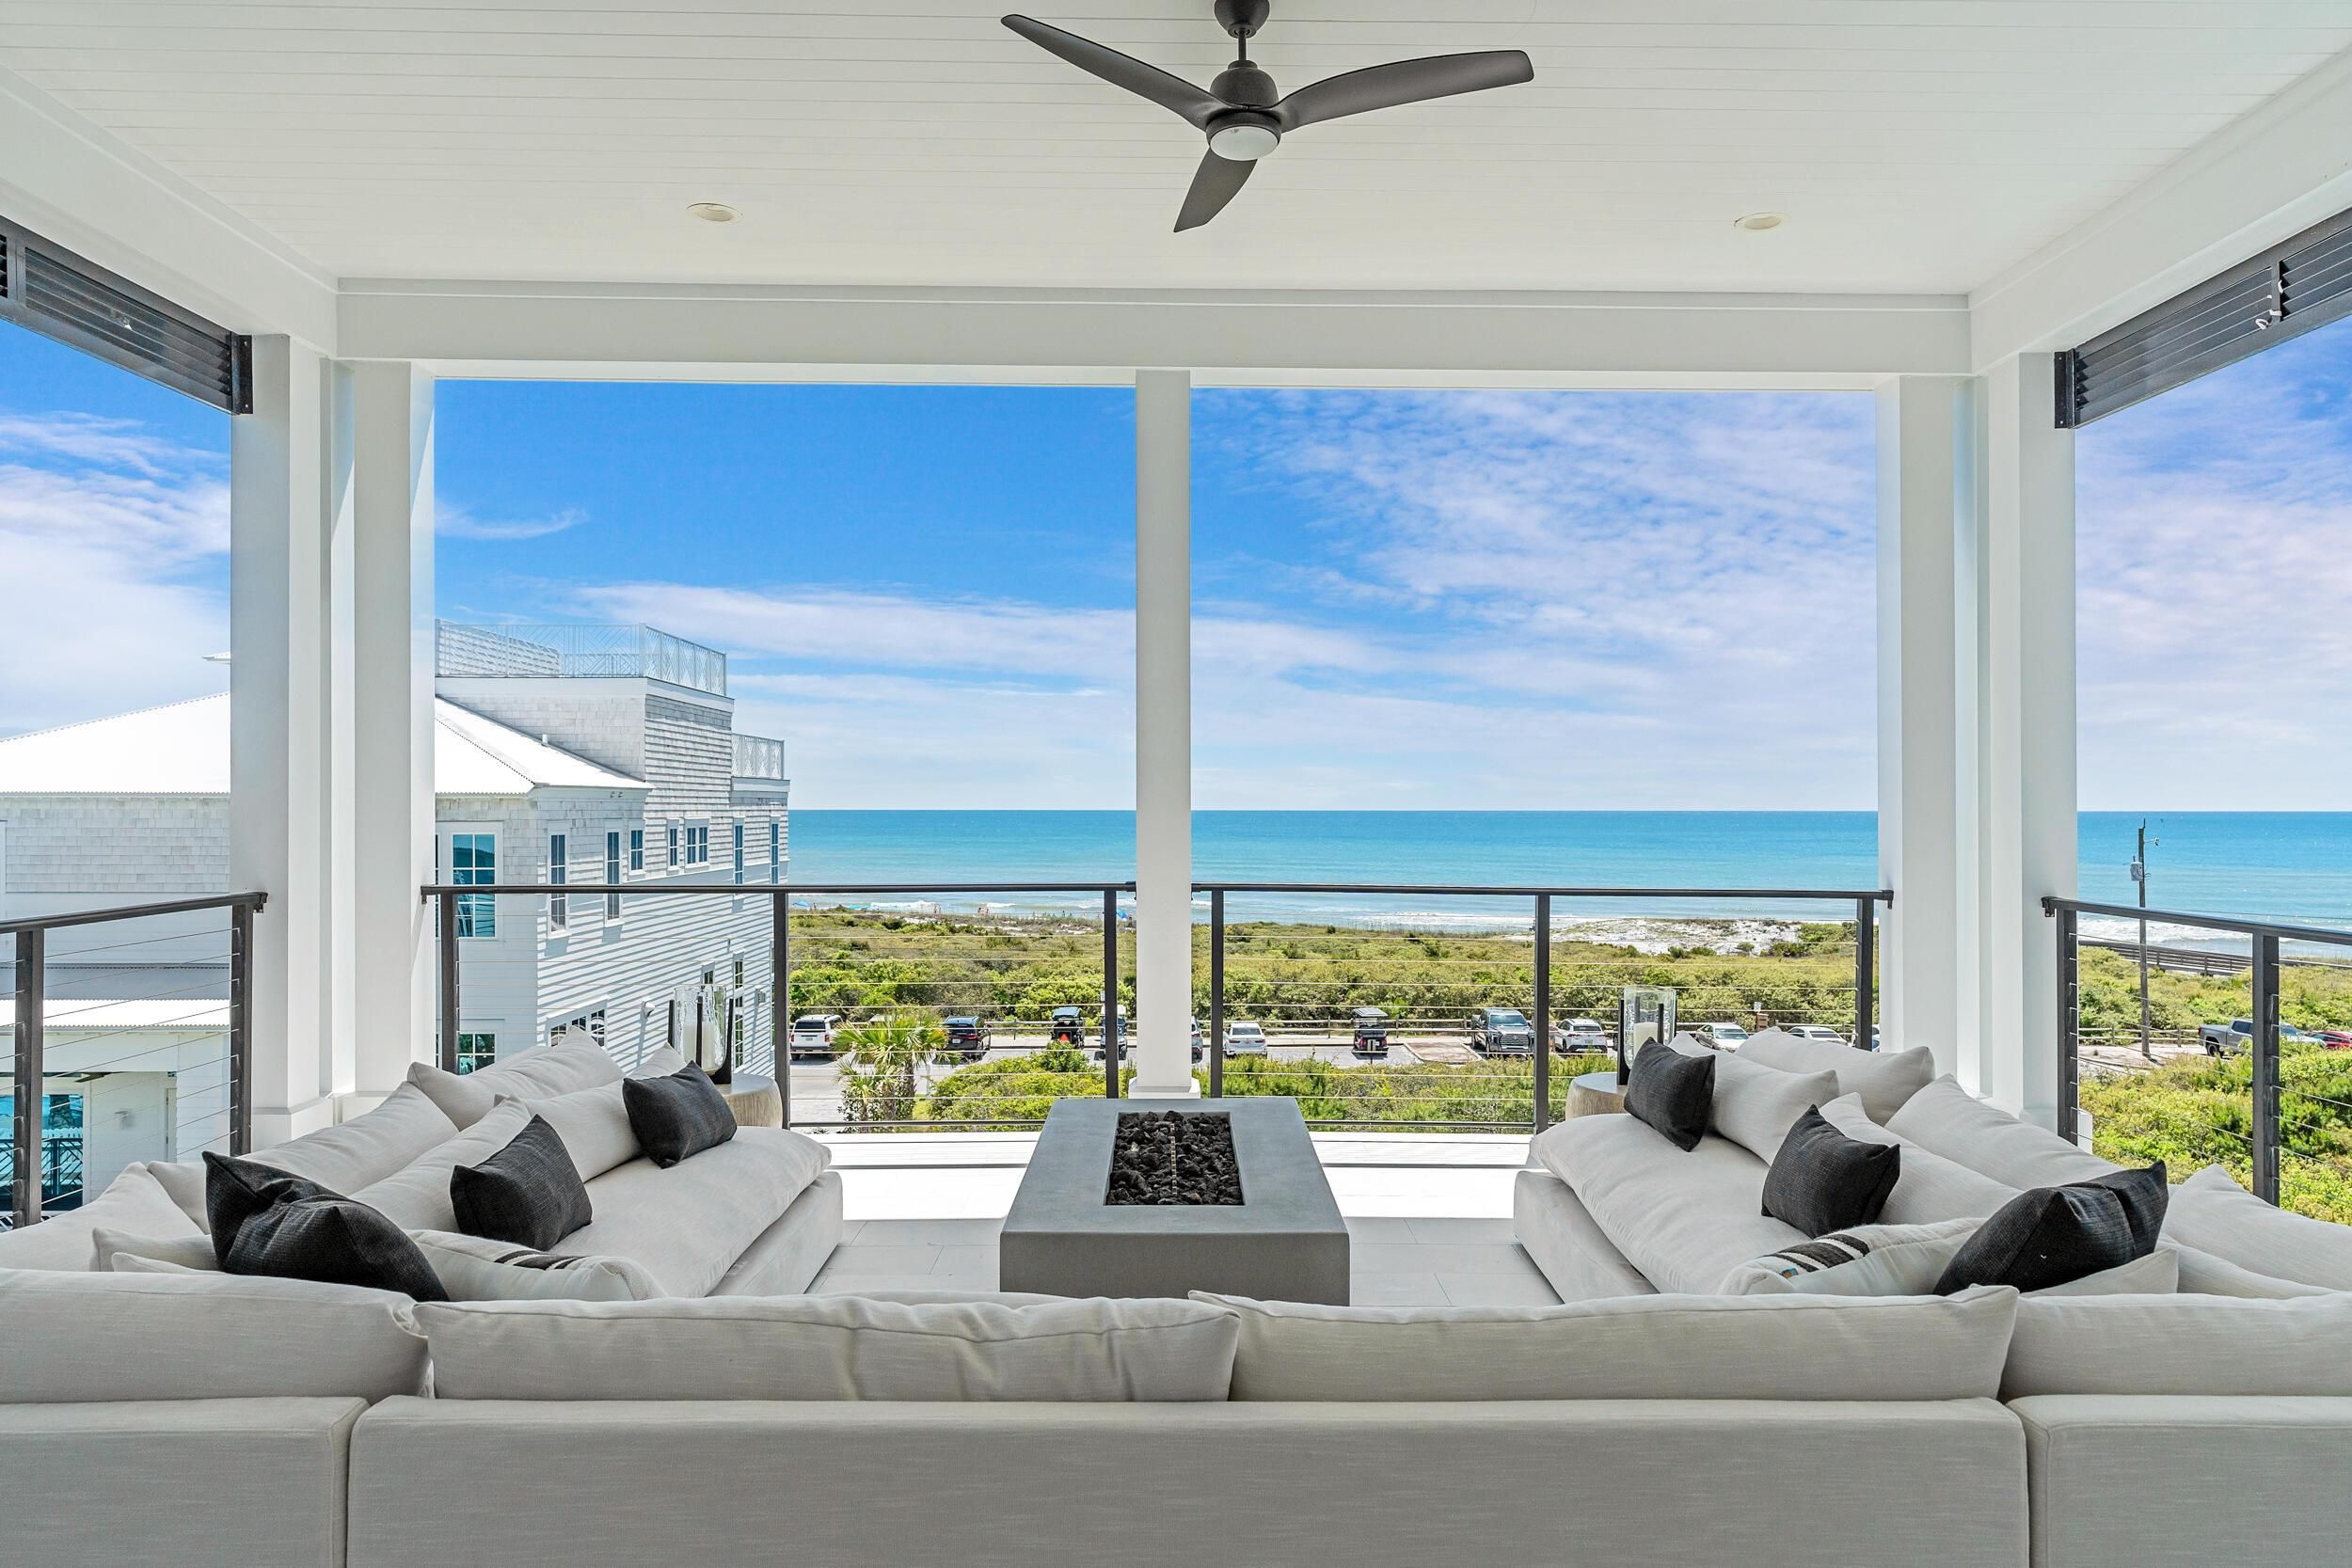
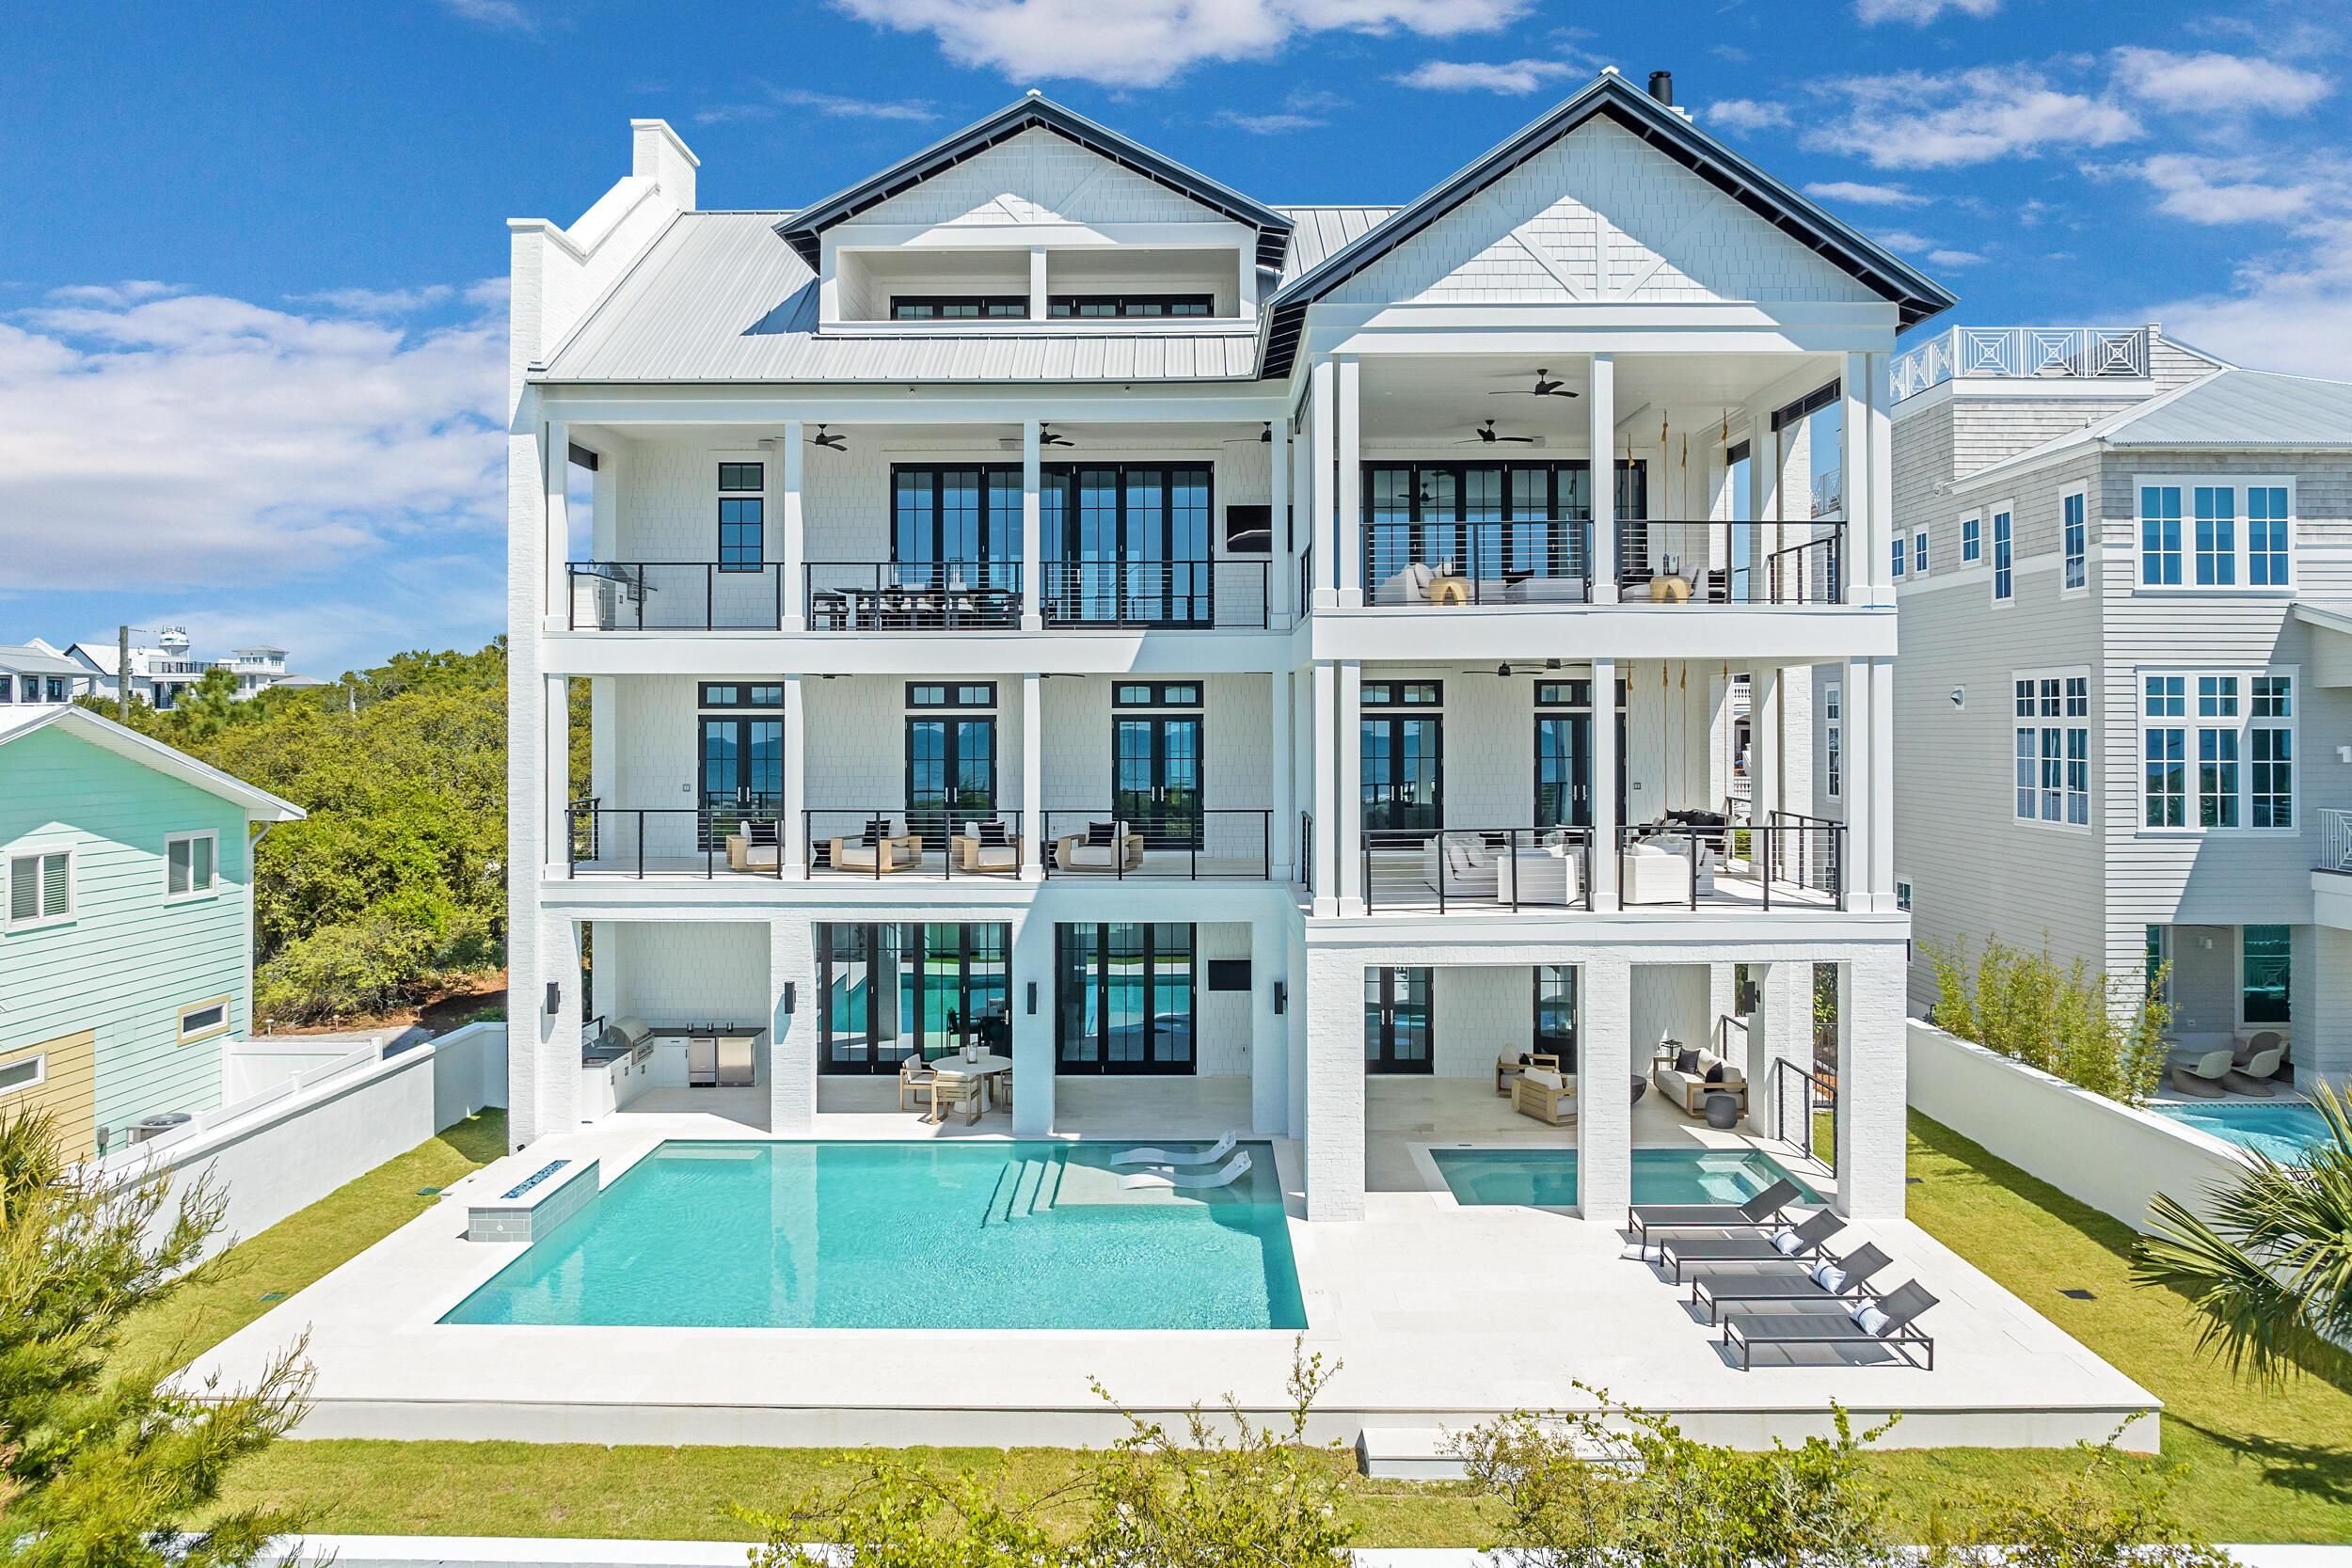
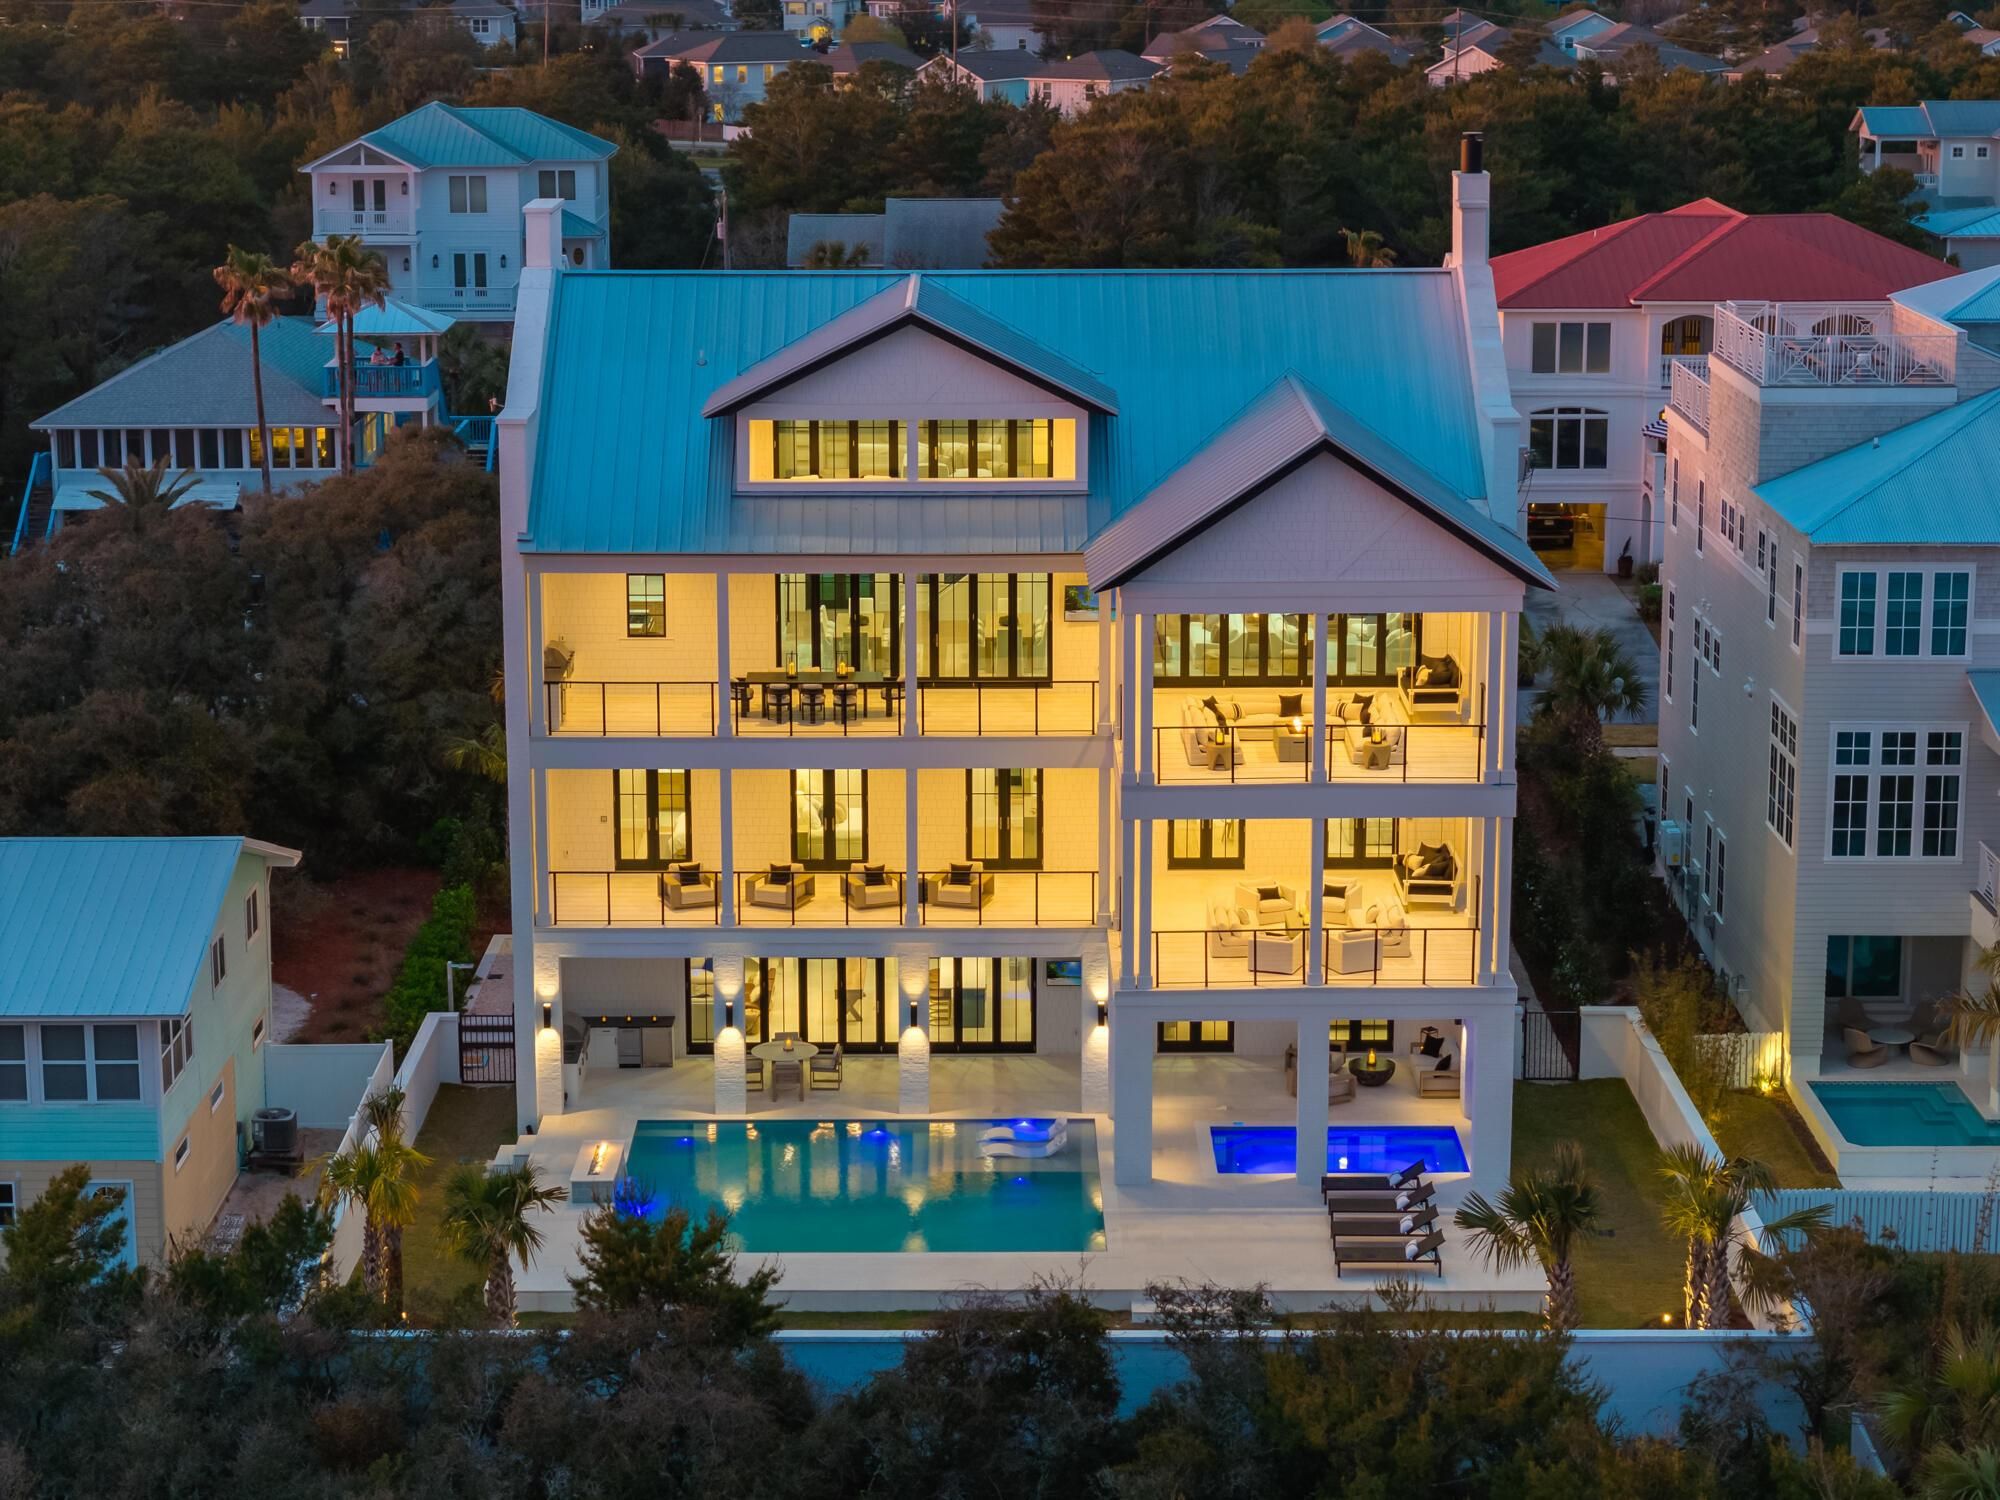
Inlet Beach, Florida, USA — 8-Bed Beachfront House With Gulf Views & Oceanfront Pool
$1,260,000
Florida's most coveted addresses, accessible through co-ownership.
Fully managed villas, apartments, penthouses and beach houses across Miami and South Beach, 30A and the Emerald Coast, the Florida Keys, Naples, Sanibel and South-West Florida and Palm Beach. Your 1/8 share of the home comes with around six weeks of personal use, a professional management team on call, and the long-term equity of the most internationally established warm-climate second-home market in the United States.
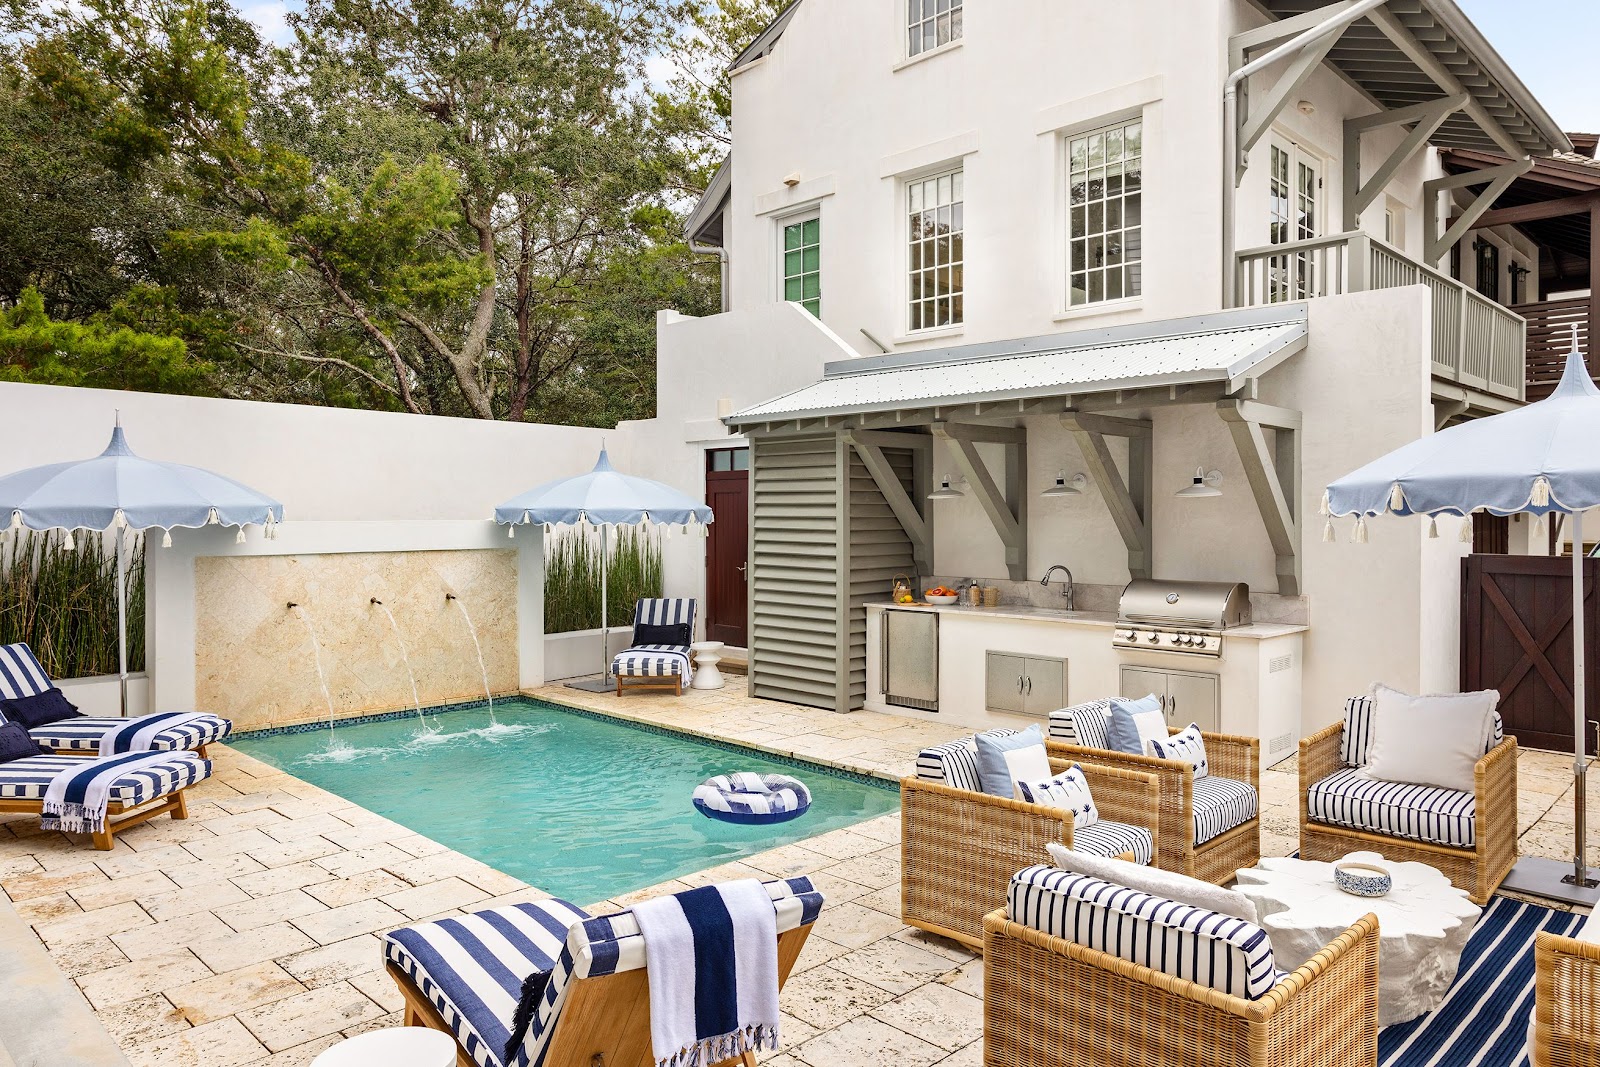
What is fractional ownership in Florida?
Fractional ownership in Florida means buying a real 1/8 share of a luxury sun-belt second home, shared with up to seven other co-owners. Each owner receives around six weeks of personal use a year, depending on the home, through a fair-rotation calendar, with all property management, maintenance, taxes and operations handled by a professional team. It is real ownership of a share of the home — not a timeshare, not a holiday club.
Why Florida?
Florida is, by some distance, the single most established warm-climate second-home market in the United States. The state has been the chosen winter destination for Northern American buyers — New Yorkers, Bostonians, Chicagoans, Toronto-and-Montreal Canadians first, with Midwesterners, Texans and increasingly European and Latin-American buyers joining over the past three decades — for more than a century, since the first railway barons ran their lines down the Atlantic coast in the 1890s and built the original resort hotels at Palm Beach, St Augustine and Miami. The state combines a coastline of more than 1,300 miles (over 2,000 km) wrapping every form of sub-tropical shore — the Atlantic surf of the Treasure Coast, the calm Gulf shallows of Naples and Sanibel, the powder-sugar white sand of the Emerald Coast on the Panhandle, the coral-reef coves of the Keys, the urban harbour of Biscayne Bay — a serious agricultural and ranching interior of citrus groves and wetlands, the working ecological landscape of Everglades National Park, and three genuinely cosmopolitan cities in Miami, Tampa and Jacksonville. No other US state offers that range of landscapes, climates and lifestyle modes inside a single road-trip radius.
Your Florida share is owned alongside up to seven other co-owners — a real share of the home, not a right to use it.
Florida's particular advantage inside the US sun-belt is the combination of tax regime, climate and accessibility that almost no other warm-weather state matches at the same time. The state has no state income tax — one of only nine US states without one — which gives it a structural pull for high-earning second-home buyers from New York, New Jersey, Massachusetts, Illinois and California who spend enough winter weeks in the state to consider tax-residence questions seriously. The Florida Department of Revenue publishes its property-tax framework openly; the state's homestead exemption for primary residents reduces assessed value by USD 50,000 and caps annual increases at 3% under the so-called "Save Our Homes" rule — a Florida-specific provision that does not extend to second-home owners but materially shapes the local property-tax market. Florida is also the only US state with year-round international air access from European hubs (London, Frankfurt, Paris, Madrid) and from Latin-American gateways (Mexico City, Bogotá, São Paulo, Buenos Aires), and the only one with a working second-home market built around direct nonstop flights from every major Northern North American city — Chicago, New York, Boston, Toronto, Montreal, Minneapolis, Detroit, Cleveland and Pittsburgh all have multiple daily nonstops to Miami, Fort Lauderdale, Tampa, Orlando and the Panhandle airports.
It is worth setting Florida in its US sun-belt competitive context. Southern California offers comparable climate and arguably higher absolute prestige at the top tier (Malibu, La Jolla, Pebble Beach) but at materially higher entry prices, on a state with one of the heaviest income-tax burdens in the country, and with structural water and wildfire risks of its own. Arizona (Scottsdale, Paradise Valley) offers excellent winter climate and no income-tax issues but lacks Florida's coastline and the international flight access. The Carolinas (Hilton Head, Charleston, Kiawah) offer southern-coastal pedigree but with a cooler winter, a shorter swimming season and no direct international air access. The US Caribbean (the Virgin Islands, Puerto Rico) is more remote, with thinner ground-services infrastructure and a more cyclical hurricane geography than Florida. Together, these comparisons help frame why Florida remains, by a meaningful margin, the highest-volume second-home state in the United States and the one with the deepest professional, legal and management infrastructure for non-resident owners.
The third structural argument for Florida is the diversity of usable lifestyles available inside a single state. A family with a 1/8 share in Rosemary Beach on the Panhandle — six hours' drive from a family with a share in Naples on the south-west coast — could be using the same state in entirely different ways at the same time, one on white-sand Gulf beaches under southern pines, the other in mangrove backwaters and shelling-grade barrier islands. A Miami penthouse owner is forty-five minutes from Key Largo and the start of the Florida Keys; a Palm Beach buyer is two hours from Orlando, three from the Keys; a Rosemary Beach owner is fifteen minutes from Seaside, twenty from Alys Beach, thirty from Destin. The state packs a remarkable amount of difference into a single 450-by-150-mile footprint — Gulf and Atlantic coasts, sub-tropical and tropical climate zones, urban skyline and barrier-island village, ranchland and reef — and a Florida share that combines proximity to several of these gives an owner a year-round US winter base rather than a single-season property. Few other states can match that range without significantly longer drive times.
One factor it is worth addressing directly is hurricane geography. Florida sits at the heart of the Atlantic hurricane basin, and the official Atlantic hurricane season runs 1 June through 30 November as tracked by the NOAA National Hurricane Center. The state has not had a year without at least one named storm crossing into its waters in living memory, and the post-2017 stretch (Irma, Michael, Ian, Idalia) has driven up insurance costs and brought building-code questions back into the foreground. For a co-ownership buyer, the practical implications are smaller than the headlines suggest but worth understanding. Property insurance is handled centrally and handled by our partner — owners do not personally arrange hurricane cover. Modern post-Andrew Florida properties (built or substantially renovated since 1994) are constructed to Miami-Dade or Florida Building Code standards that mandate impact-rated windows, hurricane straps and reinforced roofing, which materially reduces storm-damage exposure on prime inventory. And the geographical reality is that the storm risk is not uniform: the Panhandle, the Keys and the south-west Gulf coast (Sanibel, Naples, Fort Myers) sit on more exposed tracks than the south-east coast in any given decade, and a portfolio that sits on the south-east — Miami, Palm Beach — is statistically less storm-exposed than the west or the Panhandle, though every part of Florida is in the basin. We walk every buyer through this geography as part of choosing the right address. Properties on COP are vetted on construction standard, insurance availability and elevation; storm-related costs are pooled across the co-owners and managed by professionals rather than landing on an individual owner's desk.
For a co-ownership buyer thinking strategically rather than just emotionally, Florida's combination of scale, tax regime and infrastructure depth matters more than the headline glamour. The villa you buy a share of on 30A sits in a market where the buildable land between the Gulf and the protected dune-and-pine reserves is essentially capped by coastal planning rules and where the inventory of high-specification beach houses is materially finite. The Miami penthouse in Brickell or South Beach is in a market that has been the gateway for Latin-American capital for half a century and that continues to attract international and domestic flight-from-tax-state migration. The Florida Keys cabin is in a chain where the protected reef, the National Marine Sanctuary status and the Rate of Growth Ordinance (ROGO) have capped new building permits for three decades — making the existing housing stock genuinely scarce. Add the professional management and resale infrastructure that makes shared ownership transparent, insurable and resaleable, and the case for co-ownership in Florida writes itself.
One under-discussed advantage that becomes obvious once you actually start using a Florida second home is the depth of the state's professional services infrastructure for non-resident owners. A century of New York, Boston, Chicago and Toronto buyers has built up an ecosystem of specialist real-estate attorneys, property managers, CPAs, hurricane adjusters, builders and title companies across the state that smaller sun-belt alternatives cannot match. The local management companies in Miami, 30A, Naples and Palm Beach operate as a matter of routine for non-resident owners with primary homes in other states or countries; the title and escrow framework is professionalised through the state-regulated Florida Real Estate Commission, and the public record at every county clerk's office is a reliable, long-running register-of-record system. None of this is glamorous, but it is the kind of infrastructure that determines whether owning a second home from another state or country is a pleasure or a chore.
An argument worth raising separately — and the one that most decisively separates Florida from every other warm-climate US state — is the density of second-home ownership that already exists. According to US Census Bureau data, Florida has the highest absolute number of second homes of any US state by a significant margin, with a meaningful proportion of housing stock in the prime coastal counties (Palm Beach, Collier, Walton, Monroe) classified as seasonally occupied rather than primary-residence. The practical effect of this density is that the professional services ecosystem, the cultural and restaurant calendars, the airport flight schedules and even the seasonal labour market are all structurally tuned to serve non-resident owners — which is materially different from a market where second-home buyers are a minority and the local economy is calibrated for year-round residents. The cleaners, the landscapers, the hurricane-shutter installers, the pool-and-HVAC technicians, the property managers and the rental concierges who service a Florida second home are working in an economy that has been built around exactly that kind of property for two generations. The arrivals-and-departures rhythm, the seasonal preparation cadence, the post-storm response — all of it operates at industrial scale across the state, in a way that does not exist in any other US warm-climate destination. This is precisely the kind of infrastructure depth that makes co-ownership work cleanly: a managed fractional property fits naturally into a service economy designed for it, rather than being a hard-to-service exception in a residential market built around something else.
The fourth structural advantage worth naming is the transport infrastructure that makes a Florida second home practically usable rather than just nominally owned. Miami International (MIA) is the busiest international gateway in the southern United States, with direct year-round service from London, Frankfurt, Paris, Madrid, Barcelona, Amsterdam, Zurich, Rome, Lisbon and dozens of Latin American cities; Fort Lauderdale-Hollywood (FLL) covers the lower-fare and domestic-leisure market; Palm Beach International (PBI) serves the north-east coast; Key West (EYW) handles the Florida Keys; Southwest Florida International (RSW) serves Naples, Sanibel and Fort Myers; Pensacola (PNS) and Destin-Fort Walton handle the Panhandle and 30A. Most Northern US hubs are under three hours' flight time; the drive from each regional airport to the major resort towns is genuinely short (Miami to Brickell or South Beach: 20 minutes; PBI to Palm Beach: 15 minutes; RSW to Naples: 35 minutes; Pensacola or Destin to 30A: 30–45 minutes); and the year-round flight frequency means the high-frequency, short-stay use pattern that fractional ownership rewards is realistically achievable from any major Northern US or Canadian city.
Where to own in Florida
Florida's second-home market is best understood through five distinct sub-regions, each with its own architecture, microclimate, season and buyer mix. There are, of course, Florida addresses outside these five — the inland horse country around Ocala and Wellington, the Space Coast around Cocoa Beach and Cape Canaveral, the working Gulf coast around Tampa, St Petersburg and Sarasota, the Atlantic Treasure Coast around Stuart and Vero Beach, the Big Bend coast around Cedar Key and Apalachicola — and we are happy to discuss them with buyers whose interests run that direction. But the supply story for fractional ownership is concentrated in the five clusters below: Miami and Miami Beach in the south-east; 30A and the Emerald Coast on the Panhandle; the Florida Keys running south-west from Key Largo to Key West; Naples, Sanibel and the south-west coast; and the Palm Beach corridor on the north-east coast. Together they account for the overwhelming majority of international and out-of-state second-home demand in Florida.
Miami and Miami Beach
Miami is the only genuinely global city in the south-eastern United States and the gateway between North and Latin America. The metropolitan area wraps Biscayne Bay across more than a dozen distinct neighbourhoods — Brickell (the dense financial-and-residential downtown core), South Beach (the Art Deco beachfront historic district), Mid-Beach (the more residential central section of Miami Beach), Coconut Grove (the leafy bayside village south of downtown), Coral Gables (the Mediterranean-revival garden city), Key Biscayne (the island reserve just off the south coast), Bal Harbour and Surfside (the high-end northern beach communities), and the emerging arts-and-design districts of Wynwood and the Design District. The city's residential offer ranges from Brickell's glass-tower penthouses over Biscayne Bay through South Beach's Art Deco apartments around Ocean Drive to single-family bay-front homes in Coconut Grove and Coral Gables. Miami is covered in detail on its own Miami guide — this is a brief overview to position the city within the wider Florida portfolio.
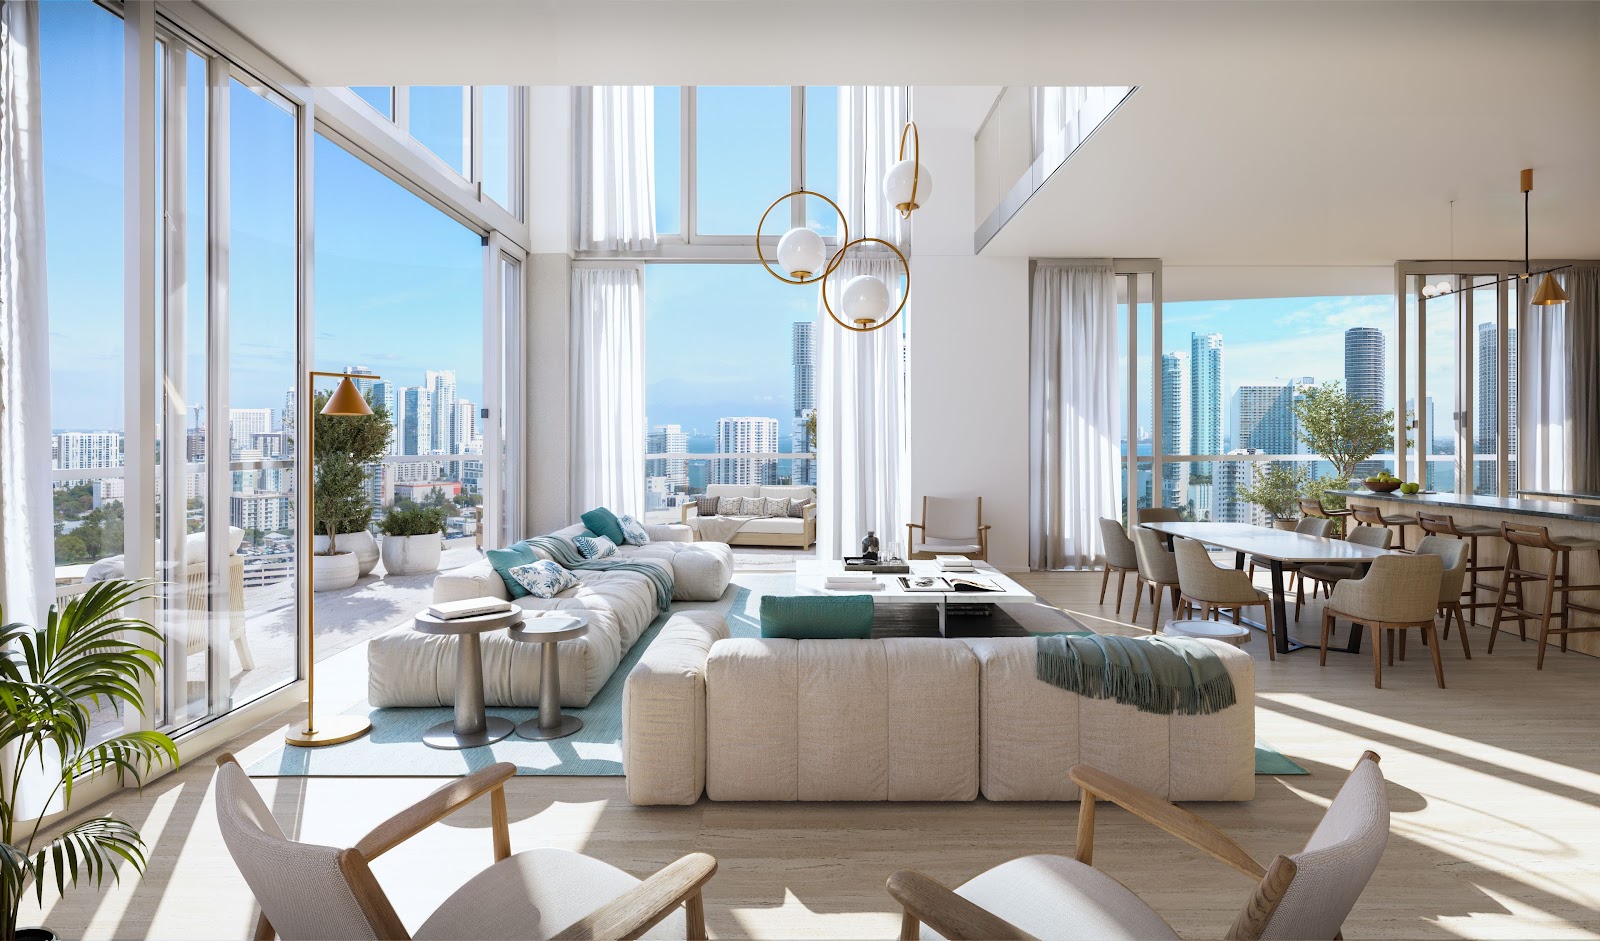
The international buyer mix in Miami is the most diverse of any US city. Latin-American buyers — Colombians, Venezuelans, Brazilians, Argentinians, Mexicans — have anchored the market since the 1980s and continue to set the tone in Brickell and the Design District; European buyers (Italian, French, Spanish, German, British, Russian) have grown sharply since the early 2000s; American buyers from the Northeast (New York, New Jersey, Massachusetts) have grown sharper still in the post-2020 migration, drawn by Florida's no-state-income-tax regime and Miami's emergence as a credible second financial city. The architectural pedigree is unusually varied: the Miami Design Preservation League protects the world's largest concentration of Art Deco buildings on South Beach; Coral Gables is one of the country's first planned Mediterranean-revival cities; the modern Brickell skyline has emerged in two decades as one of the most photographed in the Americas. Climate runs 20–25°C (high 60s°F to high 70s°F) in winter, 28–32°C (low to high 80s°F) in high summer, with the Atlantic side warmer in winter than the Gulf coast and the sea temperature above 24°C (75°F) year-round on Miami Beach. MIA is 20 minutes from Brickell, 25 from South Beach. Best for: design-led couples and professional buyers who want a genuinely global city with year-round restaurant calendars, the Latin-American cultural depth that no other US city matches, and the proximity to the Florida Keys as a weekend escape; this is the cluster covered in detail on its own pillar.
30A and the Emerald Coast
The stretch of coast known by its highway number, 30A, runs for about 30 km (18 miles) along the Gulf of Mexico in Walton County, between Destin to the west and Panama City Beach to the east, and it has emerged in the past two decades as the single most coveted small-town beach strip in the United States. The geography is unusual: a series of fifteen distinct beach towns strung along one road, each architecturally and demographically different, with the white-sand beaches of the Florida State Park system protecting the dunes between them. The signature towns west-to-east are Dune Allees and Santa Rosa Beach (the working-residential western anchor), Watercolor (the master-planned community wrapping Western Lake), Seaside (the New Urbanist village built in the 1980s that started the whole 30A phenomenon and provided the location for the film The Truman Show), Seagrove Beach (the older, leafier residential strip), Watersound and Alys Beach (the Bermudian-white New Urbanist projects of the 2000s), Rosemary Beach (the Charleston-inspired New Urbanist village at the eastern end), and Inlet Beach (the working-fishing easternmost anchor). The sand is genuinely distinctive — quartz crystal washed down from the Appalachians over hundreds of millennia — and the dune-and-pine landscape behind it is protected over thousands of acres of state and county park.
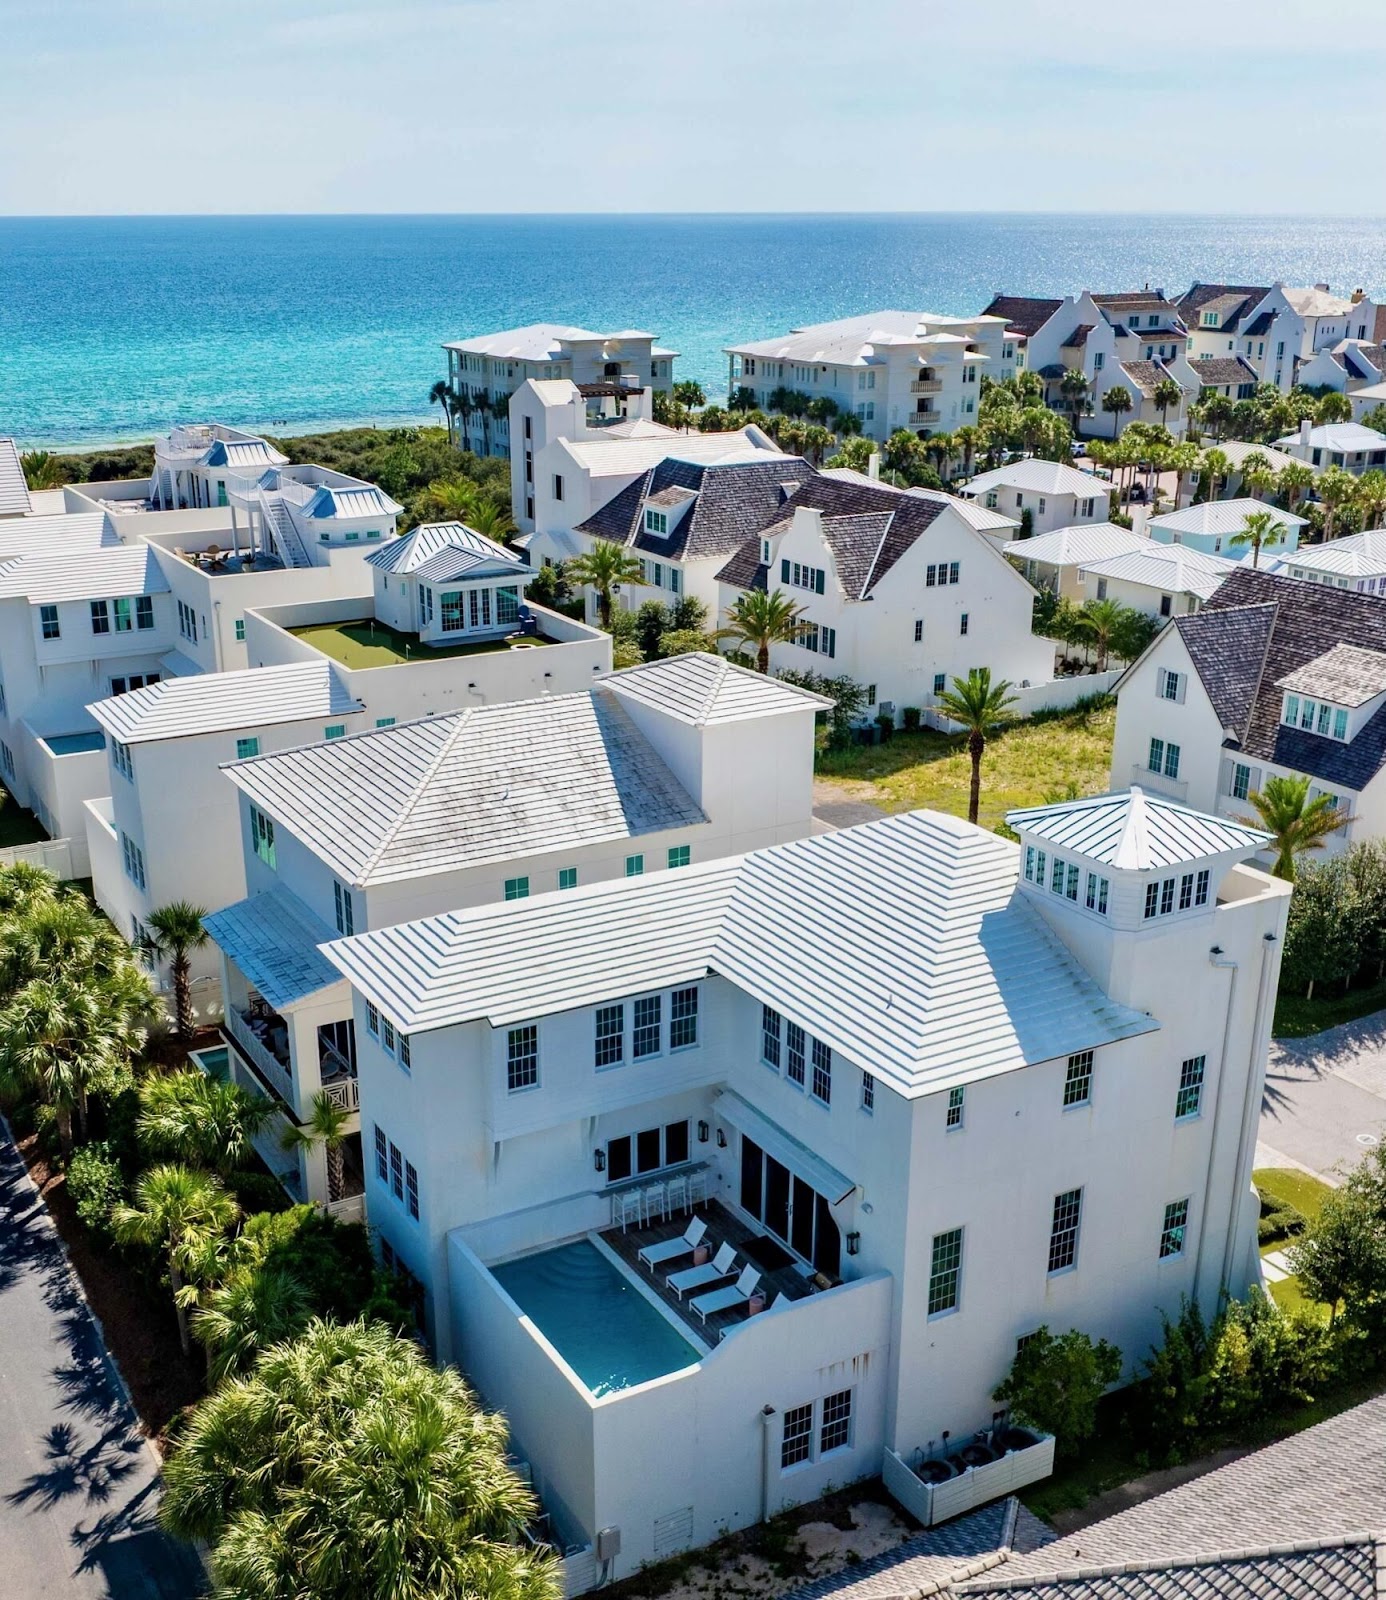
The international buyer mix on 30A is heavily American — drawn from the Atlanta, Birmingham, Nashville, Dallas, Houston and broader south-eastern US markets that have made the Panhandle their summer base for two generations, with growing Texan and Mid-western shares over the past decade. The architectural inheritance reflects the New Urbanist projects that built the most photographed villages: Seaside's pastel cottages with metal roofs and gingerbread porches, Rosemary Beach's Charleston-meets-West-Indies courtyards with deep verandas and shutters, Alys Beach's Bermudian-white limestone walls and gas-lantern courtyards, Watersound's coastal-modernist palette. The villages are walkable in a way almost no other American beach community is; bicycles outnumber cars on most streets; the central squares at Seaside and Rosemary host nightly outdoor markets, concerts and food trucks through the long summer season. Restaurants and small art-and-design shops are clustered in the village centres rather than along strip malls. Drive times from Pensacola (PNS) to 30A run 50 minutes; from Destin-Fort Walton (VPS) a shorter 30 minutes; from Northwest Florida Beaches (ECP) on the eastern Panhandle a similar 30 minutes. Climate runs warmer in summer and cooler in winter than south Florida — 11–18°C (low 50s°F to mid-60s°F) in winter to 27–32°C (low to high 80s°F) in high summer — with the Gulf water above 26°C (79°F) from mid-May through October. Best for: families with school-age children — particularly south-eastern US and Texan — who want the white-sand walkable-village rhythm, multi-generational summer holidays in the same property year after year, the New Urbanist architectural pedigree, and a long shoulder season from late March through October.
The Florida Keys
The Florida Keys are a 200-km (125-mile) chain of more than 800 islands arching south-west from the south-eastern corner of the mainland out into the Gulf of Mexico, connected by the Overseas Highway (US-1) and its 42 bridges — the longest of which, the Seven Mile Bridge between Marathon and Little Duck Key, is one of the great American road-engineering monuments. The Keys divide naturally into four sub-regions: Key Largo (the northern gateway, an hour from Miami, with the John Pennekamp Coral Reef State Park and the working diving and sport-fishing community); Islamorada (the Sport Fishing Capital of the World, a string of six islands between Tavernier and Long Key, with the most distinctive small-village atmosphere of the Upper Keys); Marathon (the working middle of the chain, with the Marathon airport and the working community); and Key West (the southernmost, the historic-district-and-conch-architecture endpoint famous for Hemingway, sunset rituals at Mallory Square and the working US Naval Air Station). The chain is protected as part of the Florida Keys National Marine Sanctuary, the third-largest marine protected area in the world; the building stock is regulated under the Rate of Growth Ordinance (ROGO), which caps annual new-permit issuance at a level well below regional demand and has produced one of the more genuinely supply-constrained property markets in the United States.
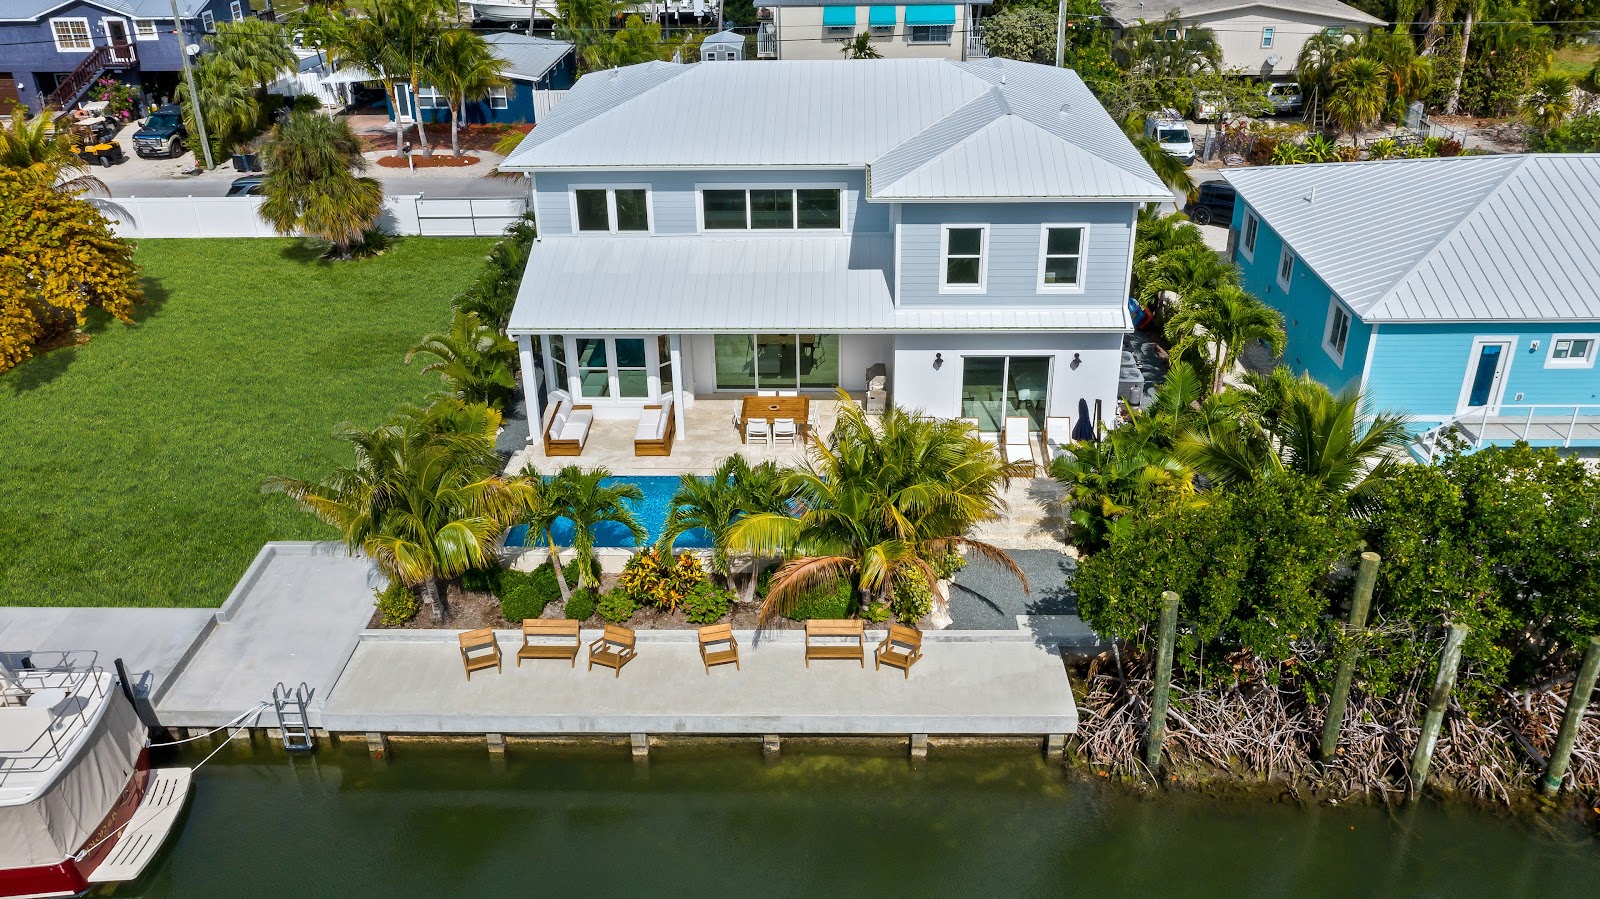
The Keys buyer mix is heavily South Floridian, Northeastern US and Texan, with a long-standing British and European cohort drawn to Key West's literary and bohemian heritage. The architectural vernacular is specific — conch houses with double verandas and metal roofs, stilted Bahamian cottages raised above flood elevation, contemporary keys-modern villas with infinity pools facing the reef. The community is much smaller and more village-scaled than mainland Florida: Islamorada and Marathon have populations under 10,000; Key West, the largest, sits at around 24,000 year-round; the entire Monroe County population (which is essentially the Keys) is under 80,000. Drive times from Miami to Key Largo run 1 hour; to Islamorada 90 minutes; to Marathon 2 hours 15 minutes; to Key West 3.5 hours, though the drive is genuinely scenic and one of the great American road journeys. Key West International (EYW) takes direct service from Miami, Atlanta, Charlotte, Dallas and several other hubs; smaller airfields at Marathon (MTH) handle regional and private aviation. Climate is the most tropical part of the United States — 21–25°C (high 60s°F to high 70s°F) in winter to 28–31°C (low to high 80s°F) in high summer — with sea temperatures above 24°C (75°F) year-round and snorkeling and diving conditions on the reef among the best in the continental US. The hurricane exposure is real and worth understanding: the Keys sit on a more active storm track than south-east mainland Florida, and the post-Irma rebuild (2017–2020) brought building codes to a higher standard than they were before. Best for: design-led couples and active families who value the diving-and-fishing lifestyle, the genuinely tropical climate, the small-village rhythm of Islamorada or Marathon, and the literary-bohemian Key West tradition for repeat short stays from Miami or further north.
Naples, Sanibel and South-West Florida
The south-west Gulf coast of Florida — anchored by Naples, Marco Island, the barrier islands of Sanibel and Captiva, and the working-and-luxury communities of Bonita Springs and Fort Myers Beach — is the quieter, calmer, more domesticated side of premium Florida. Where Miami is intense and Latin, where 30A is family-summer and walkable-village, where the Keys are reef-and-rum, Naples-and-Sanibel is the side of Florida for buyers who value the long Gulf shallows, the world-class shelling beaches, the sub-tropical landscape, the working bird-and-wildlife reserves of the Everglades and the proximity to the western edge of the Everglades watershed. Naples itself is the city, with a long established and architecturally distinctive downtown around Fifth Avenue South and Third Street South, a working Naples Pier, and one of the highest-density concentrations of golf courses and country clubs in the United States. The town's residential offer divides between the working downtown (Olde Naples), the long Gulf-front strip of Park Shore and Pelican Bay, the inland gated communities along Pine Ridge Road and along Vanderbilt Beach, and the southern enclave of Port Royal and Aqualane Shores (consistently among the most expensive residential ZIP codes in the United States).

Marco Island, 30 minutes south of Naples, is the largest of the Ten Thousand Islands at the western edge of the Everglades — a residential island that pairs Gulf-front condominium living with working backwater fishing and the proximity to the protected wilderness. Sanibel and Captiva, the barrier islands a 45-minute drive north-west of Naples, are an entirely different sub-region — protected at over 65% of land area by the J.N. "Ding" Darling National Wildlife Refuge, with strict height limits that have kept the islands free of high-rise development, and globally famous for shelling along their unusually east-west-aligned beaches. The 2022 Hurricane Ian caused significant damage to Sanibel and Fort Myers Beach; the rebuild has been substantial and the post-2022 inventory is largely to higher modern standards. The international buyer mix in south-west Florida is heavily Midwestern American (Indianapolis, Chicago, Cincinnati, Detroit, Cleveland), with strong Canadian (Ontario, Quebec) and growing German and Swiss cohorts; the community is older, calmer and more golf-oriented than the south-east coast, with a markedly higher proportion of retired and semi-retired owners. Drive times from Southwest Florida International (RSW) at Fort Myers to Naples run 35 minutes; to Marco Island 50 minutes; to Sanibel 30 minutes. Climate runs 20–25°C (high 60s°F to high 70s°F) in winter to 28–32°C (low to high 80s°F) in summer; the Gulf water is calmer and warmer in winter than the Atlantic side. Best for: empty-nesters and retirees from the Midwest and Canada, families with grandparents joining for multi-generational holidays, design-led couples drawn to the calmer Gulf-shallows rhythm, golf-and-fishing-oriented owners, and buyers who specifically prefer the quieter sub-tropical southwest over the more energetic south-east coast.
Palm Beach and the Treasure Coast
The Palm Beach corridor — running north from West Palm Beach through Palm Beach proper, north to Jupiter and Tequesta, and on up the Atlantic Treasure Coast through Hobe Sound, Stuart and Vero Beach — is the oldest established premium second-home market in Florida and one of the oldest in the United States. The town of Palm Beach was built as a winter resort for the New York and Boston Gilded Age by Henry Flagler and the Florida East Coast Railway in the 1890s; the Flagler Museum (Whitehall, the railway baron's beaux-arts mansion) remains the town's anchor cultural site. The signature Mediterranean Revival architecture of Worth Avenue, the Breakers hotel and the Mar-a-Lago estate established the visual code of "Old Florida money" that the rest of the state's premium real estate has imitated for a century. The residential sub-zones divide between Palm Beach proper (the barrier island, with its strictly residential code — no high-rise, no neon, no chain restaurants — and the long-established Mediterranean Revival mansion stock), the downtown West Palm Beach (the working mainland city, now in active redevelopment around the Norton Museum of Art), Jupiter and the northern Palm Beach county coast (the more domesticated family-residential strip), and the Vero Beach and Treasure Coast communities further north (calmer, more retired-oriented, with the smaller-town pedigree of Stuart and Vero).

The Palm Beach buyer mix is the most Northeastern American of any Florida sub-region — anchored by New York, Connecticut, New Jersey and Boston since the 1890s, with strong Philadelphia, Washington DC and Chicago cohorts and a growing post-2020 inflow of California, Texas and Midwestern buyers. The architectural pedigree is Mediterranean Revival — Addison Mizner's pre-1929 work along Worth Avenue and its surrounding streets remains the template; the post-Depression Spanish Colonial, the 1950s ranch-and-courtyard, the contemporary glass-and-stone villa of the 2010s sit alongside it on the prime streets. The town runs at a deliberately calmer pace than Miami: no neon, no high-rise on the island, no chain restaurants on Worth Avenue, an active cultural calendar (the Norton Museum, the Kravis Center for the Performing Arts, the polo at Wellington thirty minutes inland) running through the high winter season. Palm Beach International (PBI) is 15 minutes from the island; Fort Lauderdale (FLL) a 45-minute drive south; Miami 75 minutes. Climate runs 18–24°C (mid-60s°F to mid-70s°F) in winter — slightly cooler than Miami — to 27–31°C (low to high 80s°F) in summer; the Gulf Stream offshore moderates the Atlantic water temperature year-round. Best for: Northeast US empty-nesters and retired owners with deep Palm Beach family histories, design-led couples drawn to the Mediterranean Revival pedigree, cultural enthusiasts who treat the winter season's symphony, ballet and gallery calendar as the primary draw, and buyers who specifically want the calmer-and-older alternative to Miami while still on the Atlantic coast with year-round air access.
A year in Florida
Spreading owner nights that carry no set cap across a calendar year is itself a skill — and Florida is one of the more interesting destinations to plan, because the state's sub-tropical-to-tropical climate, its long winter peak season, its quieter summer, and its hurricane-aware fall give a very different shape from the Mediterranean or Alpine calendars. Below is a walk through the year as it actually unfolds on the ground across the Florida portfolio. The pattern is broadly the same across all eight co-owners of a given property, with the calendar mechanics ensuring every owner gets a fair allocation of peak weeks across a multi-year cycle. Owners with calendar flexibility — who do not insist on the same two specific weeks every year — consistently report a higher use-quality from their share than those who lock to one season alone.
Peak winter (December–March)
Florida's winter is its peak season — by some distance the most distinctive feature of owning here vs almost any other US or European destination. From December through March, the state runs at the warmest accessible point in the continental US, with daytime temperatures in the 20–26°C (high 60s°F to high 70s°F) range on the south and Atlantic coasts, sea water above 22°C (72°F) through most of the period, and reliable sunshine across the south of the state. December opens with the Christmas-and-New-Year fortnight as the highest-demand window of the year — Palm Beach, Miami, the Keys, Naples and 30A all book heavily for the holiday weeks, with restaurant booking windows in the prime addresses stretching to four to six weeks ahead. The city's polo season, the Miami Art Basel weekend in early December (the international art-world's most important week in the Americas), and the Palm Beach winter cultural calendar all stack into the same period. Owners who can be flexible on the exact week often prefer early January — the post-holiday calm, the still-warm weather, the much easier restaurant availability.
January and February are the high winter — the months Northeasterners and Midwesterners and Canadians migrate south in serious numbers. The winter horse racing at Gulfstream Park and the polo season at Wellington run through the period; the Miami restaurant scene operates at full capacity; the South Beach Wine and Food Festival lands in late February. The 30A and Panhandle coast sees its quietest months in January and February — too cool for swimming (Gulf water in the low 60s°F) but with the long-sleeve walking weather many off-season owners specifically prefer. March brings spring break — the colleges and high schools across the Northeast and Midwest run their breaks across two to four weeks somewhere between late February and mid-April, and the family-oriented coastal towns (Destin, Marco Island, Sanibel, the family side of Miami Beach) fill heavily. By late March the state is at peak season's tail end; the Atlantic water is climbing past 24°C (75°F); the Easter weekend often sits in late March or early April. The Miami Open tennis tournament runs through the same fortnight at Hard Rock Stadium, drawing the international tennis circuit. For families with school-age children, the spring-break fortnight is the heaviest single demand window of the year on 30A and the family-coastal sub-zones.
Transition spring (April–May)
April and May are the secret months of Florida ownership — the period most under-used by buyers who lock to either summer or winter and miss the genuinely best two-month window in between. The crowds disperse from mid-April onwards; the weather sits in the 23–28°C (mid-70s°F to low 80s°F) band across the entire state; the Gulf and Atlantic waters are climbing into proper swimming temperatures (24–27°C / mid-70s°F to high 70s°F by mid-May); and the restaurant scene is at its operating peak with neither the high-winter Christmas-week pressure nor the summer slow-down. The 30A coast at this point is at its photogenic best — the white sand cleared of crowds, the dune-and-pine landscape behind it in spring green, the morning bike rides between Seaside and Rosemary Beach at their most pleasant. The Florida Keys diving and fishing seasons are at their seasonal peak in April-May; the late-April Stone Crab and Lobster festival calendars across the Keys close out the winter season. The Naples and Marco Island sub-zone is at its quietest residential rhythm — the snowbirds heading north, the summer not yet settling in, the long pelican-and-sandpiper mornings on Sanibel and the Ten Thousand Islands without the December-March crowds.
For owners who can travel outside the school calendar — empty-nesters and retirees, design-led couples, the under-school-age-children cohort — the April-May fortnight in Florida is the most consistently named "favourite weeks of the year" pattern in the COP buyer feedback. Restaurants take reservations the same week; the small-town rhythms of 30A and Naples run at their most relaxed; the migratory bird seasons at "Ding" Darling and the Everglades hit their seasonal best.
Summer (June–September) and the start of hurricane season
Florida's summer pattern is well-defined and worth understanding before allocating weeks. June is the Gulf coast's secret early-summer month — warm enough for swimming everywhere in the state (Gulf and Atlantic water both above 26°C / 79°F), the school-summer holidays just beginning so the heaviest crowds still a fortnight away, the long evenings stretching past 8:30 pm on the western coasts. July and August are the high summer proper — Florida's domestic-tourism peak, when the southern US families load their cars and drive to the Panhandle, when the Cuban-American Miami summer rhythm operates at full capacity, when the Keys fishing and Latin-American flight calendars converge. The state is at its hottest and most humid — daytime temperatures in the 30–33°C (high 80s°F to low 90s°F) band across most of the state, with afternoon thunderstorms a daily near-certainty across the south Florida peninsula (the inland convection cell that builds every afternoon over the Everglades and breaks somewhere over Miami, Naples or Fort Myers between 3 and 6 pm).
The other defining feature of summer in Florida is the start of hurricane season. The official NOAA Atlantic hurricane season runs 1 June through 30 November; activity typically peaks in the second half of August through early October, with the climatological peak around 10 September. The practical effect for fractional owners is smaller than the headlines suggest: insurance is handled centrally and built into the annual budget; modern post-Andrew (1992) Florida construction is to building codes that materially reduce storm damage; and major hurricanes affecting a specific property's track in any single season remain statistically uncommon. But it does shape calendar planning. The peak hurricane window of late August through mid-October sees softer demand on the Keys, the Panhandle and the south-west coast — owners who want quieter weeks at the property and who can monitor the seven-day NHC outlook are often happy to take the period; owners with strict no-disruption preferences typically schedule outside it. The southeast coast (Miami, Palm Beach) sits on a less storm-exposed track in most decades than the Panhandle or the Keys, but every part of Florida is in the basin.
Inland and on the Panhandle, the summer rhythm is family-summer: 30A's villages at their busiest with multi-generational family rentals through July and August; Naples and Sanibel running with a quieter, more retired-oriented summer (the school-summer crowds skew Panhandle rather than Naples); Miami at its sub-tropical peak with the cultural calendar dialled back but the beach scene and the Cuban summer cuisine at full operation. The Miami summer flight schedule expands to Argentina and Brazil in their winter season, giving the city a particularly active Latin-American flavour through July and August.
Fall (October–November) and hurricane awareness
October is the meteorological transition month — the peak hurricane window winding down through the first half of the month, the school-half-term holidays from the northern US bringing a short family-travel spike in the second half. By late October the state has shifted into its long, warm fall season — daytime temperatures back in the 23–28°C (mid-70s°F to low 80s°F) band, water temperatures still above 26°C (79°F) on the south coast, the humidity dropping noticeably, the restaurant-and-cultural calendar quietly re-opening for the winter season ahead. The Atlantic hurricane season officially closes on 30 November; in practice, late-season storms after mid-October are uncommon and the second half of November is one of the most reliable warm-weather windows of the year.
November is many seasoned Florida owners' favourite month. The temperatures sit in the 22–27°C (low 70s°F to high 70s°F) band day-after-day; the water is still warm enough for swimming everywhere south of Tampa Bay; the high-winter crowds have not yet arrived; the restaurant scene is at full operation but easy on bookings; and the migratory-bird and wildlife seasons hit their seasonal peak in the Sanibel, Everglades and Treasure Coast reserves. Thanksgiving week is the season's first significant family-travel demand window — the Northeast US, Midwest and Canadian families load up for the four-day weekend, and the family-coastal sub-zones (Naples, 30A, the family side of Miami Beach) fill heavily. By the first week of December the winter season has effectively begun and the calendar pattern transitions back to peak.
Who buys in Florida, and why
The buyer mix in Florida is the most diverse of any US state — by a meaningful margin — and the structural drivers behind it have not changed materially in fifty years. New York and Northeast buyers have anchored the state's premium second-home market since Henry Flagler's railway in the 1890s and remain the single largest cohort across Palm Beach, Miami and the Atlantic coast; the post-2020 acceleration of migration from high-tax Northeastern states to Florida has reinforced rather than displaced that flow. Midwestern American buyers — Chicago, Indianapolis, Cincinnati, Detroit, Minneapolis, Cleveland — dominate the south-west Gulf coast (Naples, Sanibel, Marco Island) and the Treasure Coast (Stuart, Vero Beach), drawn by direct flight access and a calmer rhythm than the south-east. Latin-American buyers — Colombians, Venezuelans, Brazilians, Argentinians, Mexicans — concentrate in Miami, Brickell, Coral Gables and Key Biscayne, where multilingual professional services, Spanish-speaking schools and the cultural-and-business depth of the city make it a natural North American base. South-eastern US buyers — Atlantans, Birminghamians, Nashvillians, Charlotteans, Texans, Houstonians, Dallasans — dominate the Panhandle and 30A, with multi-generational family connections going back two or three decades. Canadian buyers are the second-largest foreign cohort after Latin America, concentrated on the Gulf coast and the central east coast. European buyers — British, German, Italian, French, Swiss, Scandinavian — have grown sharply over the past decade, particularly in Miami, the Keys and Naples, with the British presence strongest in Palm Beach and the German presence strongest on 30A.
The age-and-life-stage profile is in some respects more revealing than the geographical breakdown. The largest single buyer cohort across the COP Florida portfolio is in the 55–70 age band — owners whose primary income is established or in winding-down mode, whose children are at university or beyond, who are thinking actively about the warm-state-residency question, and whose long-run thinking on the second home runs to the next 20–25 years. The second-largest cohort is the 40–55 age band — typically dual-income professional couples with school-age children, who use their share around school holidays (winter break, spring break, summer) and value the operational simplicity of a fully managed property in a state where remote-ownership friction is otherwise non-trivial. The third and fastest-growing cohort is the 30–45 age band — younger professional couples (some pre-children, some with young children) who are using the share as a winter pied-à-terre for a Northern US primary home and who value the flexibility of a fractional structure that does not commit them to a single property forever.
Within those groups, Florida co-ownership tends to suit a small number of well-defined buyer profiles:
- Northeast US and Canadian snowbirds — owners from New York, Boston, Toronto, Montreal, New Jersey, Connecticut, Massachusetts, Ontario and Quebec who use their share predominantly in the December-through-March winter window, often combining a Christmas week with a two-or-three-week January-February pattern and a spring-break return. The 55–70 cohort is the heart of this demographic.
- Midwestern retirees and pre-retirees — owners from Chicago, Indianapolis, Cincinnati, Detroit, Minneapolis, Cleveland and Pittsburgh who concentrate in the south-west Gulf coast (Naples, Marco Island, Sanibel) and use their share in long winter blocks rather than short summer trips. The fully managed model is the central appeal — the operational simplicity of arriving with no preparation and leaving with no shutdown is what makes the structure work for owners who would otherwise have to fly their own help south or manage remote staff.
- International buyers building a North American base — Europeans (British, German, Italian, Swiss, Scandinavian) and Latin Americans (Colombian, Argentinian, Brazilian) who want a US toehold for family, business or tax-residency reasons. Miami is the single most common cluster for this cohort, with Palm Beach and 30A as the secondary markets.
- Multi-generational families — four- and five-bedroom houses on 30A, Marco Island, Sanibel and the Keys that sleep grandparents, parents, children and partners in the same week. The fractional model handles extended-family calendar coordination better than a whole-ownership model, particularly when the family spans multiple states or countries with different school calendars and where the property would otherwise sit empty for forty weeks a year.
- Design-led couples choosing Miami, Palm Beach or 30A — owners who treat the architectural pedigree of the Mediterranean Revival Palm Beach mansion, the Art Deco Miami Beach apartment or the New Urbanist Rosemary Beach courtyard as the primary destination, who book repeat shorter stays around the calendar's quieter rhythms, and who value the cultural depth of the city or village over the sand alone.
- Tax-residency-minded buyers from high-tax states — a growing cohort of New York, New Jersey, California, Massachusetts and Illinois residents using their Florida share as part of a long-running shift toward establishing Florida domicile, working alongside their tax counsel on the day-count and supporting-evidence questions that the state's no-state-income-tax regime rewards. The COP team can point this cohort to qualified Florida tax counsel; we do not give tax advice, and our partner sets out the tax position for your country before you buy.
- Active-and-outdoor owners — divers and snorkelers choosing the Keys for reef access, sport fishermen choosing Islamorada or Marathon, golfers choosing Naples or Palm Beach, sailors choosing the Atlantic Intracoastal or the Gulf coast, and birders and naturalists choosing the Everglades-and-Sanibel side of the state for the migratory seasons.
A pattern worth highlighting is the multi-region buyer — Florida owners who hold a second COP share elsewhere. The most common combination is Florida plus a summer-cool destination — a Miami or Palm Beach winter share paired with an Aspen, Vail, Lake Tahoe or French Alps summer share for July and August, when Florida is at its hottest and the alpine destinations at their most beautiful. The second-most-common is Florida plus another sun-belt destination — a 30A or Naples share paired with a California, Mexico or Caribbean share — for owners building a portfolio of warm-climate options to use across the year. Less common but increasingly observed is the Florida-plus-Europe pattern (a Miami or Keys winter share plus a Mediterranean summer share in Mallorca, the Côte d'Azur or the Italian Lakes). The fractional model makes that portfolio strategy practical: two 1/8 shares across complementary climates cost less than a single whole property at either of the addresses individually, and the management relationship across the portfolio is unified, which removes the multi-jurisdiction friction.
What unites these otherwise quite different buyer profiles is the underlying calculation: the second-home weeks each of them actually uses in a year are within the around six weeks a 1/8 share delivers, the operational overhead of running a Florida property remotely is non-trivial in any of the major sub-zones (and notably higher than in many alternative states because of the hurricane-insurance regime, the building-and-pool maintenance load in a sub-tropical climate, and the year-round HVAC and humidity management), and the resale liquidity of a fractional share inside a managed portfolio is — in our experience across the COP network — markedly higher than the resale liquidity of a whole property at the same address. Florida is a market where the maths of fractional ownership lines up almost perfectly with the use pattern of the buyer, and where the operational realities of remote ownership are otherwise heavy enough to make the managed model materially more attractive than direct ownership.
Practicalities: getting there and what you own
Florida airports and ground access
Florida is the most internationally connected state in the southern United States, with seven major commercial airports and a dense secondary network of regional fields covering the state. Miami International (MIA) is the largest, with direct year-round service from London (Heathrow), Frankfurt, Paris (CDG), Madrid, Barcelona, Amsterdam, Zurich, Rome, Lisbon, Helsinki, Istanbul, Tel Aviv, Dubai and Doha among others, plus comprehensive Latin-American coverage (Mexico City, Bogotá, Lima, Quito, Caracas, Santiago, Buenos Aires, São Paulo, Rio de Janeiro, Panama City) and every major North American gateway. Fort Lauderdale-Hollywood (FLL) handles the lower-fare and domestic-leisure traffic into south Florida; Palm Beach International (PBI) serves the north-east coast; Southwest Florida International (RSW) at Fort Myers serves Naples, Sanibel, Marco Island and Fort Myers Beach; Key West International (EYW) handles the Keys; Pensacola International (PNS) and Northwest Florida Beaches (ECP) serve the Panhandle and 30A. Most Northern US hubs are under three hours' flight time from a Florida airport; most European hubs are nine to ten hours from MIA; most Latin-American gateways are three to six hours.
Drive times from each regional airport to the major sub-zones are short. MIA to Brickell or South Beach: 20 minutes. MIA to Coral Gables, Key Biscayne or the Design District: 15–25 minutes. MIA to Key Largo: 1 hour 15 minutes. FLL to Palm Beach: 45 minutes. PBI to Palm Beach island: 15 minutes. PBI to Jupiter or Tequesta: 25 minutes. RSW to Naples: 35 minutes. RSW to Marco Island: 50 minutes. RSW to Sanibel or Captiva: 30 minutes. PNS to 30A (Rosemary Beach to Seaside): 50 minutes. VPS / Destin to 30A: 30 minutes. ECP to Rosemary Beach or Inlet Beach: 30 minutes. EYW to Key West Old Town: 10 minutes. Most owners pre-arrange a private transfer rather than self-driving, particularly when arriving late or with multiple bags; the professional transfer companies across the state are well established. Florida is also easily accessible by interstate driving: I-95 runs the entire Atlantic coast from Jacksonville to Miami, I-75 runs from the Georgia border to Naples and into the Everglades, and the Florida Turnpike provides the inland north-south spine.
Whole-property vs 1/8 share: the comparison
The case for a fractional structure in Florida is most clearly seen in the side-by-side comparison against both whole ownership and long-term rental — the three ways most buyers actually consider holding a Florida second home.
| Whole second home | COP 1/8 fractional share | Long-term rental | |
|---|---|---|---|
| Upfront commitment | Full property value | ~1/8 of the property value | First/last/deposit only |
| Equity in the asset | Full appreciation | ~1/8 of appreciation | None |
| Hurricane insurance | Owner-arranged, full premium every year | Pooled across co-owners, handled by our partner | Landlord-arranged, built into rent |
| Personal use | Up to 52 weeks (most use 6–10) | Around six weeks a year, fairly rotated | Defined by lease |
| Operations burden | Owner-managed or hired staff | Fully included | Landlord-managed |
The comparison most buyers find most telling is what you actually get for your capital. Owning a whole home outright ties up the full purchase price in a property most owners use for a few weeks a year, and leaves you to organise everything yourself. A 1/8 share gives you the same calibre of home, around six weeks a year, real equity and a professional team that takes care of everything in between.
What you actually own — the legal share
The legal nature of a Florida co-ownership share is one of the questions buyers should understand fully before purchase. You own a real share of the home — an eighth, a quarter — not a right to use it. You can sell it, pass it on to your heirs, and it grows in value with the house.
The practical effect is that you hold a real share of the home — not a timeshare, not a points membership, not a usage right. You can sell it through our partner's resale process or to a qualifying outside buyer; you can leave it to your children under your home jurisdiction's inheritance rules; and it grows in value with the house.
How fractional ownership works in Florida
The mechanics of fractional ownership in Florida are framed by four things that work together: the legal set-up arranged by our partner for each home, the Florida property-tax regime that applies to all real estate including the state's distinctive homestead exemption and "Save Our Homes" cap (and how those rules apply differently to second-home owners), the state's hurricane-insurance market that shapes the largest single line item in the annual budget, and the county-level recording system that handles registration of the underlying property at each county clerk's official records. The set-up is specific to each home, the property tax and insurance are handled within the shared annual budget, and the county clerk gives the underlying real estate its documentary clarity — together they make for a clear, predictable ownership experience.
What you own: a real share of the Florida home
You own a real share of the home — an eighth, a quarter — not a right to use it. You can sell it, pass it on to your heirs, and it grows in value with the house. Big decisions, such as selling the home or major works, are decided together by the co-owners.
Property tax basics: county assessments, homestead exemption, the Save Our Homes cap
Florida operates a relatively straightforward property-tax framework by US standards, and almost all of the routine compliance is handled on the co-owners' behalf rather than by the individual owner. County property tax — the annual ad valorem tax assessed by the local county property appraiser — is the primary line, calculated on the just-value assessment as set by the property appraiser, and falling within a typical range of 1.0%–2.0% of assessed value depending on the county and the millage rate (Miami-Dade, Monroe, Collier, Lee, Walton, Palm Beach and the other Florida counties each set their own millage). County tax is handled by our partner, so individual owners never deal with the county property appraiser or tax collector directly.
The Florida homestead exemption is one of the most distinctive features of the state's property-tax system and worth understanding even though it does not apply to second-home owners. Under Florida law, a property serving as a primary residence and registered with the county property appraiser receives a homestead exemption that reduces the assessed value by up to USD 50,000 for property-tax purposes, plus the "Save Our Homes" cap that limits annual increases in assessed value to the lesser of 3% or inflation. These benefits apply only to Florida primary residences, not to second homes; a fractional share of a second home falls outside the homestead regime entirely. The practical effect is that non-resident second-home owners — including fractional properties — typically face higher assessed-value growth year-over-year than Florida primary residences, with no Save-Our-Homes shelter. This is a structural cost worth factoring into the annual budget, and one modelled in the annual budget on a continuing basis.
Florida has no state income tax — one of the structural advantages of the state for high-earning second-home buyers from high-tax states like New York, New Jersey, Massachusetts, California, Connecticut and Illinois who spend enough Florida weeks to consider tax-domicile questions seriously. The state's property-transfer tax (documentary stamp tax on deeds and intangible tax on mortgages) is paid at conveyance and is built into the closing structure. Federal capital-gains tax on resale applies as it would on any US real estate; our partner sets out the tax position for your country before you buy. The Florida tourism development tax, where applicable to rental nights, is handled centrally. The point worth making here is that the Florida tax regime is, overall, among the most favourable in the United States for second-home ownership — particularly for buyers whose primary state has a heavy income tax — and the management team makes the routine compliance straightforward.
Hurricane insurance, building codes and the Florida construction reality
Insurance is the largest single line item in the Florida annual budget and worth understanding in some detail. The state has experienced significant insurance-market dislocation since 2017, with several private carriers either withdrawing entirely or pulling back from the most exposed coastal markets, and the state-run Citizens Property Insurance Corporation — the writer of last resort — now carrying a meaningful share of the state's residential coverage. For an individual second-home owner, this has meant annual premium increases of double-digit percentages year-over-year through the late 2010s and into the 2020s, with non-renewals a real risk on older or more storm-exposed buildings. For a professionally managed co-owned home procuring insurance at scale across multiple sub-zones, the procurement is materially more efficient — pooled risk across the portfolio, professional broker relationships, and the buying power that single-owner properties cannot match.
The Florida Building Code — substantially upgraded after Hurricane Andrew in 1992 and again after the 2004-2005 hurricane season — is one of the strictest building codes in the United States and is particularly strict in the high-velocity hurricane zone covering Miami-Dade and Broward counties. Modern post-1994 Florida properties are constructed to standards including impact-rated windows and doors, hurricane straps and clips tying roof to wall to foundation, reinforced roofing, and elevation requirements in flood-prone zones. These standards have measurably reduced storm damage on prime modern inventory: properties built to the Miami-Dade high-velocity code performed materially better in Hurricane Irma (2017) and the subsequent storms than older buildings or properties in other jurisdictions. The checks when a property is listed includes construction-standard review, elevation review and insurance availability — properties that do not meet defensible standards are not brought in.
A specific item buyers often ask about is the flood-zone designation under the Federal Emergency Management Agency (FEMA) flood-map system. Florida's coastal and low-lying inland properties are mapped into flood zones (Zone X for minimum risk, Zone AE for 1%-annual-chance flooding, Zone VE for coastal high-velocity flooding subject to wave action), with the zone designation driving the requirement for federally backed flood insurance through the National Flood Insurance Program (NFIP) or a private equivalent. Properties on the Gulf coast at Sanibel, the Atlantic coast at Palm Beach and the Florida Keys are commonly in VE or AE zones; properties further inland or on higher ground sit in X zones. The NFIP enrolment and the annual flood-premium payment are handled as part of the routine insurance budget; the per-owner flood-premium impact is materially smaller than it would be for a single-owner second home, since the premium is shared across the co-owners. Properties we list are reviewed for their flood-zone designation, the elevation of the finished floor above base flood elevation, and the historical flood-claim record at the address — factors that materially affect both insurability and long-term resale value.
Inheritance and Florida probate
Directly held Florida real estate is subject to Florida probate on the death of the owner, which can be a slow and procedurally heavy process — Florida is one of the states where inherited real estate routinely sits in probate for twelve to twenty-four months before clearing to the heirs. For a non-Florida resident dying with a Florida property, the situation is more complex still — the property typically requires ancillary probate in Florida alongside the primary probate in the deceased's home state, with associated cost and delay. Your share passes to your heirs as part of your estate, and our partner sets out exactly how this works for your country before you buy.
The professional management model and how the calendar works
Once the purchase completes, a professional management company takes over all operational responsibility for the Florida property. Your personal weeks — with no set cap on total nights for a 1/8 share — are allocated through a fair-rotation calendar that mixes peak weeks (the Christmas-New Year fortnight, the Easter and spring-break window, the long July-and-August weeks where applicable, the Thanksgiving week) with shoulder-season and quieter weeks across the year. Owners pre-book several months ahead; the unused weeks are either held for the owner pool or, where the property's structure allows, rented to the broader market with the income flowing back to the co-owners. Service-charge collection, building maintenance, hurricane preparation, insurance management, property-tax payment, year-round HVAC and humidity management, pool and garden care, the linen-and-cleaning between stays, the welcome arrival, the on-call concierge — all sit with the management company. The deep professional services ecosystem across the state — a century old in Palm Beach and Miami, three decades old on 30A, two decades old in Naples and the Keys — means that the routine practical realities of owning a Florida property remotely are handled by professionals who have been catering to non-resident owners for generations.
Resale: how to exit, typical timelines, the professional process
When you decide to exit your Florida share, a professional resale process is in place, run by our partner, so you can sell your share without having to sell the whole house — whereas whole-property resales in the Florida prime tier typically take 12–24 months on the open market. Shares sell: hundreds of shares in homes like these have already been resold—in just over three months on average, and nearly three in four for more than the owner paid. After a typical first-12-months holding period you set the price, and your co-owners get the first chance to buy. The buyer pool is already aware of the property. For owners who want maximum control over the price and process, an open-market sale to any qualifying buyer remains an option — but most owners find the established process faster and cheaper.
The full mechanics of fractional ownership across all jurisdictions — usage calendars, exit procedures, rental income treatment, insurance, the transfer on death, the relationship with the management company — are covered in our co-ownership explained guide. For specific Florida property availability, browse the listings in the property grid above, or join our list for new-property alerts as they come to market.
Your ownership at a glance
- Real ownership of the home — a real 1/8 share of the home: transferable, inheritable, and it grows in value with the house. Not a timeshare, not a points membership, not a usage right.
- Professional management included throughout — pre-arrival preparation, linen and cleaning between every stay, year-round HVAC and humidity management, gardening and pool care, hurricane preparation and post-storm checks, county property tax and insurance management, and the on-call concierge are all handled for you.
- Clear, supported resale through our partner's resale process — the existing audience of co-ownership buyers means your share has an organised market from day one, with our partner's resale process letting you sell your share without selling the whole house, rather than facing the 12–24 months a comparable whole Florida property might sit on the open market.
Still deciding which Florida region?
Many readers arrive on this page already half-decided — they want Florida, but not yet which Florida. The choice between Miami, 30A, the Keys, Naples and Palm Beach is rarely about budget alone; the major sub-regions sit in different price bands but each has entry-level and prime tiers, and a 1/8 share at a quieter address in one cluster often costs less than a similar share at a more prestigious address in another. The decisive question is usage pattern. How will you actually spend your weeks across a calendar year? The right answer for most buyers is one most have not previously articulated, because the question rarely arises until ownership becomes concrete. Our team has spent years inside the Florida second-home market and can walk you through the regional differences — climate, calendar, owner mix, day-to-day rhythm, hurricane geography — before you commit to a cluster. Below is the framework we walk through with buyers who reach the same fork, with deliberate over-simplification — most owners actually end up combining elements from more than one — but useful as a starting point.
Choose Miami or Miami Beach if you want a genuinely global city, year-round restaurant calendars, the Latin-American cultural depth that no other US city matches, the Art Deco architectural pedigree of South Beach or the contemporary high-rise pedigree of Brickell, and the proximity to the Florida Keys as a weekend escape. Miami works hardest for design-led couples and professional buyers — particularly Latin-American, European and Northeast US — who value the city's pace, the international flight access, the cultural depth, and the year-round usability that no rural Florida sub-region can quite match. Unlike a traditional timeshare, which locks you into one fixed week year after year, a Miami share gives you the city in its most distinctive seasons — December's Art Basel weekend, January's calmer cultural calendar, May's pre-summer warm shoulder — across rotating weeks.
Choose 30A and the Emerald Coast if you want a family-summer New Urbanist beach village, the white-sand walkable rhythm of Rosemary Beach, Seaside or Alys Beach, the long shoulder season from late March through October, and the multi-generational family-vacation pedigree that has built up across the south-eastern US over two generations. 30A is the natural choice for families with school-age children — particularly south-eastern US and Texan — who want the children to come back to the same village year after year and who value the New Urbanist architectural and planning pedigree alongside the powder-quartz sand.
Choose the Florida Keys if you want a genuinely tropical climate at the closest accessible point in the continental United States, the diving-and-fishing lifestyle of Islamorada or Marathon, the literary-bohemian Key West tradition, and the smaller-village rhythm that the Rate of Growth Ordinance has kept genuinely small. The Keys work hardest for design-led couples and active families who value the reef-and-fishing access, who use the property in shorter weekend-and-week trips from Miami or further north rather than long single holidays, and who are comfortable with the hurricane-exposed geography in exchange for the genuine year-round warmth.
Choose Naples, Sanibel or South-West Florida if you want the quieter Gulf-coast alternative to the south-east, the long shallow swimming margins of the Ten Thousand Islands or the shelling beaches of Sanibel, the golf-and-tennis-and-fishing residential rhythm of Olde Naples and Marco Island, and the proximity to the Everglades and the working ecological reserves of the south-west. South-west Florida is the natural choice for Midwestern and Canadian empty-nesters and retirees, multi-generational families with grandparents joining for extended winter visits, and design-led couples who specifically value the calmer Gulf-shallows rhythm over the more energetic south-east coast.
Choose Palm Beach and the Treasure Coast if you want the oldest established premium second-home market in Florida, the Mediterranean Revival architectural pedigree of Worth Avenue and its surrounding streets, the deliberately calm pace of the island (no neon, no high-rise on the island, no chain restaurants on Worth Avenue), the active winter cultural calendar (the Norton Museum, the Kravis Center, the polo at Wellington), and the Northeast-US-with-Old-Money-pedigree owner mix that makes Palm Beach the most socially distinctive sub-region in the state. Palm Beach works hardest for Northeast US empty-nesters and retirees with deep family histories in the town, design-led couples drawn to the architectural pedigree, cultural enthusiasts treating the winter symphony-and-gallery calendar as the primary draw, and buyers who specifically want the calmer-and-older alternative to Miami while still on the Atlantic coast with year-round air access.
The portfolio approach is worth at least mentioning. A meaningful proportion of Florida co-ownership owners hold more than one share — either elsewhere in Florida (a Palm Beach winter base paired with a 30A summer house, a Miami pied-à-terre paired with a Keys weekend cabin) or further afield (a Florida winter share paired with an Aspen or Vail summer share, a Miami share paired with a French Alps or Mallorca summer share, a 30A share paired with a Newport Beach or Lake Tahoe non-winter share). For owners building a multi-region portfolio with COP, you have one team across every destination — the same advisors, the same calendar mechanics, the same resale process across every property you own. (For a wider orientation across the state's regions, seasons and culture, the official Visit Florida tourism site is a useful starting reference.) Two 1/8 shares — a Florida winter-sun home plus a summer-cool mountain or Mediterranean share, say — give an owner roughly 90 days of use across a calendar year, drawn from genuinely different lifestyle modes, at a combined annual carry that is still a fraction of what a single whole property at either address would cost. Unlike a traditional timeshare — where the structural design locks you to a single week in a single building, with no equity, no transferability and a maintenance fee that compounds for life — the fractional structure is built for exactly this kind of multi-property, multi-region portfolio.
Whichever way the decision goes, the deeper exploration starts on the cluster and parent pages:
- Explore the USA →
- Explore Miami →
- Explore 30A and the Emerald Coast →
- Explore the Florida Keys →
- Explore Palm Beach →
If you would like to talk through which Florida region best fits your family's actual use pattern — rather than the brochure version of it — join our list and we will be in touch with relevant new-property alerts and an introduction to the team. Our specialists can walk you through the climate differences across the five clusters, the realistic flight options from your home city, the hurricane geography of each sub-region against the property's specific construction standard, the realistic mix of personal-use weeks and rental weeks across a calendar year, and how a Florida share fits inside any wider portfolio you may already be building elsewhere in the United States or internationally.
Questions & Answers
Florida Fractional Ownership — Frequently Asked Questions
Fractional co-ownership in Florida gives you a real 1/8 share of a luxury Florida property — oceanfront on Miami Beach, a waterfront home in the Florida Keys, a resort villa in 30A's Emerald Coast, or a furnished condo above Biscayne Bay. The legal set-up is arranged by our partner for each home and walked through with you before you buy. Your 1/8 share is genuine property equity — around six weeks of Florida sunshine per year at 1/8 the full purchase cost.
Your 1/8 share gives you around six weeks per year. Florida is a genuine year-round destination — winter (December–March) attracts domestic snowbirds and international visitors escaping cold climates, while summer draws families and beach holidaymakers. A structured calendar manages peak winter and holiday allocations through a fair rotating priority system.
Yes — many of our Florida properties welcome short-term rental of unused weeks, and it is an easy way to earn from the weeks you are not using. Your unused weeks can be listed on short-term rental platforms, with income paid directly to you after the platform fee — particularly rewarding in high-demand locations.
Each Florida property listing shows whether short-term rental is available for that home, in line with local rules.
Florida has been one of the USA's fastest-appreciating property markets, driven by population growth (net in-migration of ~365,000 people per year), no state income tax (attracting wealth migration from high-tax states), year-round sunshine, and consistently strong tourism. Miami luxury and the Florida Keys have seen exceptional price growth; 30A's Emerald Coast has emerged as a premium destination commanding top-tier vacation rental premiums.
Selling is simple. When you decide to move on, your Florida fractional share is marketed to buyers already looking for fractional co-ownership.
Our partner's resale process handles the sale for you, so you sell your share without the whole house having to be sold. After a typical first-12-months holding period you can sell whenever you choose, at the price you set — your co-owners get the first chance to buy. Hundreds of shares in homes like these have already been resold — in just over three months on average, and nearly three in four for more than the owner paid.
Browse COP's Florida listings, review the 1/8 share price and submit an enquiry.
Get in Touch
Speak to an expert
Tell us what you're looking for and we'll be in touch.